Tag

home

Browsing


In this episode of “The Houzz Guest,” host Dorcas Adewole sits down with third-generation builder and real estate developer Matt Panella to discuss how natural disasters are changing the way homes are built. Drawing on his family’s decades of building experience in Central California, Panella, who uses Houzz Pro, shares practical ways to help protect homes from wildfires, highlighting smart upgrades like ember-resistant vents and flame-retardant siding. He also offers advice on vetting contractors, spotting red flags and keeping remodeling projects on track. To wrap up the episode, Panella tackles real-world remodeling questions in a rapid-fire Design Dilemmas segment, covering topics including structural insulated panels, or SIPs, and deck repairs.

Watch or listen to this episode on Houzz, YouTube, Spotify and Apple Podcasts. New episodes drop every Tuesday.

See show notes


This article was originally published by a www.houzz.com . Read the Original article here. .


The housing market has changed greatly since the COVID-19 pandemic, along with consumer spending behaviors. During this period, housing demand surged, home prices appreciated rapidly, inflation increased, supply-chain disruptions happened, and mortgage rates moved from historic lows to elevated levels. These changes raise important questions about whether home buyer spending patterns have changed and how long the spending boosts associated with a home purchase last.

Using pooled Consumer Expenditure Survey (CES) microdata from 2020 to 2023, we find buyers of newly built and existing single-family detached homes generate almost the same increase in spending during the first year after purchase, about $8,750 and $8,674, respectively. The key difference is not the amount of additional spending, but its composition. Buyers of newly built homes spend more on furnishings, while buyers of existing homes spend more on property alterations and repairs. For both groups, most appliance purchases occur during the first year after buying a home.

Spending Attributable to Home Buying

Because these socio-economic characteristics also influence spending, comparing group averages alone overstates the effect of the home purchase itself. Therefore, it is worthwhile to estimate how much additional spending is associated with purchasing a home after taking these differences into account[1].  We then use the results to compare predicted spending for similar households under different homeownership situations.

Table 1 shows how purchasing a newly built home affects household spending after accounting for differences in household characteristics. The estimates compare the same household under two scenarios: if it purchases a newly built home and if it does not move. The Year 1, Year 2, and Year 3 columns show the predicted annual spending of a typical newly built home buyer in the first three years after purchasing a home, while the “If Not Moving” column shows the predicted spending for the same household had it remained in its current home in one year. The differences shown in parentheses represent the additional spending associated with buying a newly built home compared to a nonmoving counterpart.

If the typical new home buyer does not move, it is predicted to spend about $2,722 per year on appliances, $2,354 on furnishings, and $9,660 on property alterations and repairs. During the first year after purchasing a newly built home, spending increases in all three categories. The largest increase is in furnishings, where predicted spending rises to $7,236, about $4,882 more than for an otherwise identical non-moving homeowner. Appliance spending also increases substantially to $4,475 (+$1,752). Property alterations and repair spending rises to $11,776 (+$2,116), although this increase is not statistically significant.

The spending boost changes over time. Appliance spending is concentrated in the first year after purchase and returns close to the non-moving level thereafter. Furnishing spending also peaks in the first year but remains moderately higher in the second and third years, suggesting that households continue furnishing their homes over time. In contrast, property alterations and repair spending shows little evidence of a lasting increase. This pattern is consistent with newly built homes requiring fewer repairs and replacements, so post-purchase property alterations projects are generally more discretionary.

Table 2 presents a similar comparison for households with characteristics typical of an existing home buyer. During the first year after purchase, a typical buyer of existing homes spends significantly more than otherwise identical homeowners who does not move on appliances, furnishings, and property alterations and repair projects. The largest increase occurs in property alterations and repairs, with predicted annual spending of $13,882, approximately $5,498 more. A typical buyer of existing homes also spends more on furnishings (+$1,973) and appliances (+$1,202).

Typical existing home buyers spend more on appliances primarily during the first year after purchase. Furnishing expenditures decline after the first year but remain modestly elevated through the third year. Property alterations and repair spending exhibits the greatest persistence. Even in the second and third years after purchase, buyers of existing homes continue to spend substantially more on property alterations and repairs. This sustained spending reflects that existing homes often required renovations, repairs, and deferred maintenance that are completed over time after purchase.

[1] Tobit regression is used in this statistical analysis, because many households reports no spending in a given category.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


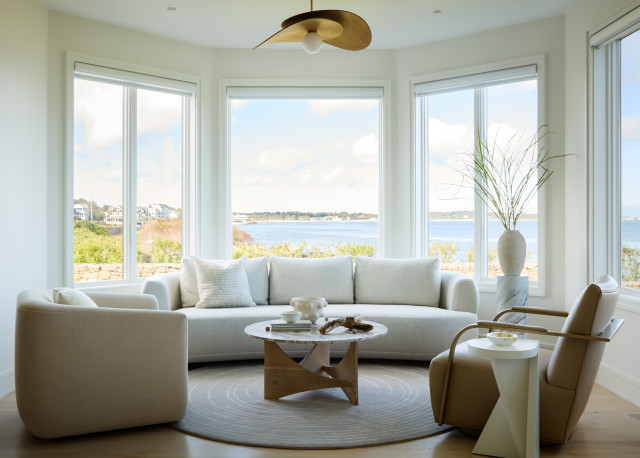
This Boston couple knew the moment they purchased this property on Rhode Island’s Narragansett Bay that it would become the family’s permanent summer retreat. After spending a few years enjoying the location with their two college-aged children, they decided to remodel the 25-year-old house to better suit their lifestyle and aesthetic. “She’s from California and wanted the indoor-outdoor lifestyle she had there,” interior designer Trevor Fulmer says. “They wanted to blend traditional New England and more modern Southern California styles.”

A new pool, spa, outdoor kitchen, dining area and lounge patio give the family plenty of comfortable gathering space outside, while large new sliding glass doors and a pass-through kitchen window create seamless transitions between indoors and out. Inside, Fulmer made cosmetic updates throughout the home, layering distinctive textures into the warm neutral palette his clients desired. The result is an inviting coastal retreat where nothing feels too precious and the homeowners can relax with family and friends.


This article was originally published by a www.houzz.com . Read the Original article here. .


Affordability challenges continued to weigh on the new-home market in June, as elevated mortgage rates, rising inflation and broader economic uncertainty kept many prospective buyers on the sidelines.

Sales of newly built single-family home rose 1.6% in June to a seasonally adjusted annual rate of 628,000, up from an upwardly revised May estimate, according to newly released data from the U.S. Department of Housing and Urban Development and the U.S. Census Bureau. The pace of new home sales is down 5.6% from a year earlier.

New home sales are down 5.2% on a year-to-date basis, as housing demand remains lackluster amid affordability challenges. At the regional level, only the Midwest has seen gains for new home sales thus far in 2026.

Builders continue to use incentives to support sales, with NAHB survey data showing that 62% of builders offered some form of incentive in June.

New home sales are gaining some momentum at the more affordable range of the market, with homes priced below $300,000 accounting for 23% of June sales, up from 16% a year earlier. However, that price point is generally only achievable in markets with lower development and construction costs, particularly with respect to lower state and local regulatory costs.

A new home sale occurs when a sales contract is signed, or a deposit is accepted. The home can be in any stage of construction: not yet started, under construction or completed. In addition to adjusting for seasonal effects, the June reading of 628,000 units is the number of homes that would sell if this pace continued for the next 12 months.

New single-family home inventory in June was virtually unchanged at 485,000 units, down 0.2% from May, and down 3.2% compared to a year ago. This represents an elevated 9.3 months’ supply at the current building pace. According to NAHB analysis, due to rising resale single-family inventory and elevated new construction inventory, combined new and existing home inventory stands at just above a 5.2 months supply, the highest level since the fall of 2014.

The median new home sale price in June fell 3.3% from May to $398,300, and was down 2.7% from a year ago, largely due to builder price cuts and some geographic shift in mix to the more affordable Midwest.

Regionally, on a year-to-date basis, new home sales are up 2.6% in the Midwest but fell in the other three regions, with declines of 4.7% in Northeast, 4.9% in the South and 10.1% in the West.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


At the start of 2026, most home builders predicted that high mortgage rates and hesitancy among buyers would be their toughest challenges this year. They weren’t wrong: the 30-year mortgage rate averaged 6.49% in June and housing demand has weakened, as reflected by flat mortgage applications in the first half of the year. As a result, new home sales are 7% behind this time last year and builders have put the brakes on production, starting 5% fewer homes than in the first half of 2025. Amid this tough business environment, when companies need to find efficiencies and economies of scale, the industry is experiencing increased levels of consolidation activity. So far in 2026 for example, Taylor Morrison was acquired by Berkshire Hathaway; Tri Pointe Homes by Sumitomo Forestry; and United Homes Group by Stanley Martin Home.

To better understand the extent of this phenomenon across a representative sample of builders in the country, the NAHB/Wells Fargo Housing Market Index survey asked about merger and acquisition (M&A) activity in August 2025 and again in June 2026. Results reveal an uptick in the share of builders reporting increased M&A activity in their local markets, from 14% in August 2025 to 21% in June 2026. More than 40% of builders, however, report no changes in consolidation trends in the markets where they operate. 

A second finding also points to somewhat higher levels of M&A activity in the industry: the share of builders who have been approached for acquisition and/or merger doubled between August 2025 and June 2026, from 9% to 18%. As a result, the segment who have not been approached at all dropped from 87% to 78% during this period.

When asked about future plans for growth, most builders (61%) plan to expand organically in their existing markets. Only small minorities plan to expand by acquisition (6%) or to be acquired by another company (5%). For additional details, please consult the full survey report.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


Buying a home typically generates a wave of consumer spending beyond the purchase of the home itself. Following a home purchase, households often buy appliances and furnishings and undertake remodeling and repair projects to make the home fit their needs and preferences. This spending supports many businesses and industries, extending the economic impact of home buying.

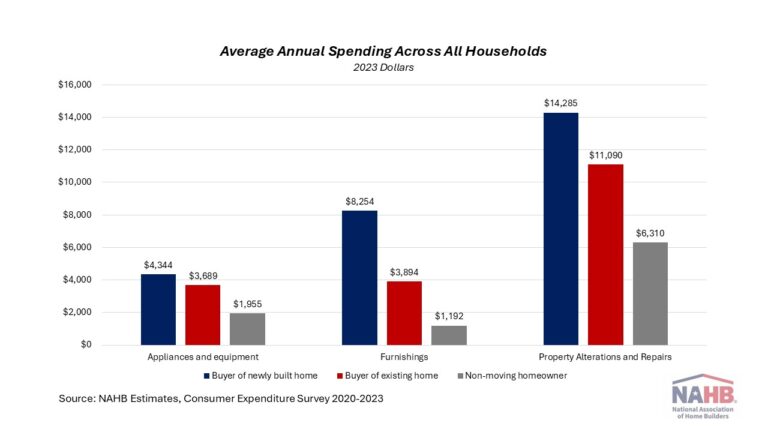
NAHB analysis of Consumer Expenditure Survey data from 2020 through 2023 shows that buyers of both newly built and existing single-family detached homes spend substantially more than homeowners who did not move. As shown in chart below, buyers of newly built homes spend an average of $26,882 on appliances, furnishings, and remodeling and repairs during the first year after purchasing a home, nearly three times the $9,457 spent by non-moving homeowners. Meanwhile, buyers of existing homes spend an average of $18,673 during the first year after purchasing a home, approximately twice the amount spent by non-moving homeowners.

Appliances

Among all households, buyers of newly built homes spend an average of $4,344 on appliances during the first year after purchasing a home, compared with $3,689 for buyers of existing homes and $1,955 for non-moving homeowners. The largest appliance expenditure among buyers of newly built homes includes refrigerators and home freezers, televisions, clothes washers and dryers, computers, and lawn equipment. This pattern may partly reflect differences in which appliances are already included with a newly built home and which items buyers must acquire separately. Most newly-constructed homes include essentials like stoves, ovens, and dishwashers. However, refrigerators and/or freezers and laundry appliances are often optional upgrades.

Televisions, while not among the most expensive appliances, rarely come with new homes. As a result, buying television sets for multiple rooms in the new house can add up to the high level of spending, reflecting the high frequency of these purchases by new home buyers rather than a particularly high cost of the item. Buyers of existing homes exhibit a similar spending pattern, although average expenditures are somewhat lower.  However, spending on clothes washers and dryers is higher for buyers of existing homes ($481) than for buyers of newly built homes ($387).

Furnishings

Recent home buyers also spent considerably more on furnishings than non-moving homeowners Among all households, buyers of newly built homes spend an average of $8,254, more than twice the $3,894 spent by buyers of existing homes and approximately seven times the $1,192 spent by non-moving homeowners.

Compared with buyers of existing homes, buyers of newly built homes spend more on nearly every major furnishing category. The largest furnishing expenditure among buyers of newly built homes is for bedroom furniture (about $1,204) and sofas ($1,178), followed by blinds, shades, and other window coverings ($1,089). The corresponding expenditures for buyers of existing homes are $385, $1,010, and $183, respectively, while non-moving homeowners spend only $111, $208, and $31.

Spending on dining room and kitchen furniture also differs substantially across homeowner groups. Buyers of newly built homes spend $702, compared with $399 for buyers of existing homes and $47 for non-moving homeowners. These differences reflect the need to furnish an entire home after a purchase, particularly for buyers of newly constructed homes with few window treatments.

Property Alterations and Repairs

Property alterations and repair projects account for the largest share of home buyer spending. During the first year after purchasing a home, buyers of newly built homes spend an average of $14,285 on property alterations and repairs, compared with $11,090 for buyers of existing homes and $6,310 for non-moving homeowners. While both groups of home buyers spend substantially more than non-moving homeowners, the composition of their property alterations expenditures differs considerably.

The composition of property alterations and repair spending differed between the two home buyer groups. Buyers of newly built homes allocate relatively more spending to projects that customized or expanded the property, including landscaping, patios, walkways, fences, driveways, swimming pools, and finishing basements, attics, or porches.

Buyers of existing homes, by contrast, invest more spending into updating, replacing, or repairing existing components. Major categories included room property alterations, heating and air-conditioning systems, flooring, painting, and roofing. The results, therefore, suggest that buyers of newly built homes tend to focus more on customization and additions, while buyers of existing homes tend to focus more on renovation and replacement.
This article was originally published by a eyeonhousing.org . Read the Original article here. .


Over half of new single-family homes built in 2025 were two or more stories, according to the recent release of the Census Bureau’s Survey of Construction (SOC). After increasing in 2024, the share of homes started with two or more stories fell in 2025. However, the gap between one-story and two-or-more-story shares has been relatively stable since 2021, with only small year-to-year fluctuations.

Nationwide, the share of new homes with two or more stories fell from 52.5% in 2024 to 51.4% in 2025, while the share of new homes with one story rose from 47.5% to 48.6%. Despite the decline, more than half of new homes built nationally in 2025 were two or more stories, though this share varied significantly across the nation.

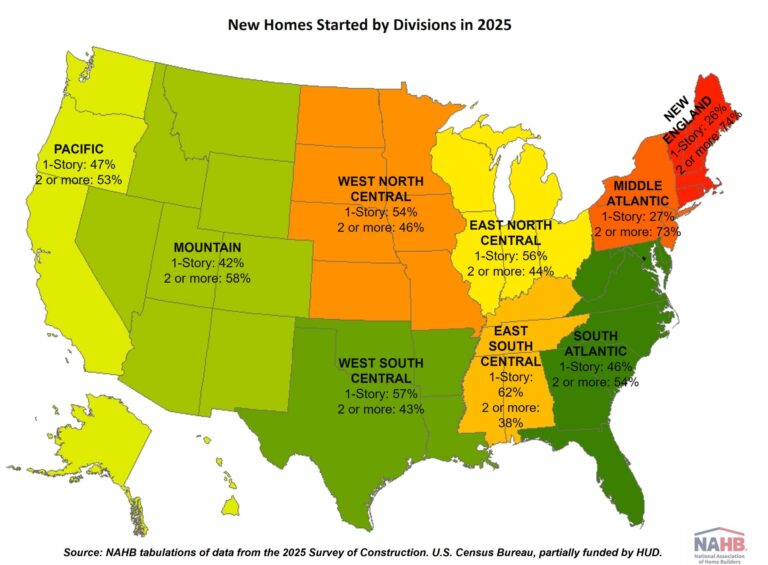
As shown below, new homes started in the Midwest and the South generally favored single-story homes, while the Northeast and the West had higher shares of two or more stories. In the Midwest, single-story homes accounted for 55.7% of new homes started in the East North Central division and 54.3% in the West North Central division. In the South, single-story shares reached 61.7% in East South Central and 56.6% in West South Central. The South Atlantic division was the exception, with two or more story homes still the majority (54.2%).

Outside the Midwest and the South, single-story shares were lowest in New England (25.7%) and the Middle Atlantic (26.5%), while the Pacific (47.5%) and Mountain (41.9%) divisions were higher.  

Compared with 2024, single-story shares rose in the East North Central and East South Central divisions to multi-year highs, while shares in the West North Central and West South Central divisions fell to multi-year lows.

In the Northeast, where two-or-more-story homes are more common, New England rebounded and the Middle Atlantic declined further. Two divisions in the West have moved in opposite directions over the past few years. The single-story share in the Pacific has increased in seven of the last eight years, from 32.7% in 2017 to 47.5% in 2025. However, the Mountain division saw the reverse, falling from a peak of 50.7% in 2020 to 41.9% in 2025.

Looking specifically at new homes with three or more stories, the national share edged up to 5.2%, compared to 5.0% in 2017. The small increase over the past eight years has been concentrated in New England (from 7.2% to 14.1%) and the Middle Atlantic (from 14.0% to 15.1%), while the share has doubled in Mountain division (from 3.0% to 6.6%). New homes with three or more stories were less common in the Midwest and South, accounting for less than 3% of new homes started in most divisions, except the South Atlantic at 5.0%.


This article was originally published by a eyeonhousing.org . Read the Original article here. .

Pin It