Author

realtykast_fmyriy

Browsing


The Producer Price Index for final demand was up 0.3% in October, after rising 1.4% in September. Compared to a year ago, final demand prices were up 6.5%.

The price of goods used in new residential construction (including energy) was unchanged over the month and up 9.8% from last year, while the price of services was up 0.7% over the month and up 11.3% from last year. Combining goods and services, the price index for inputs to new residential construction was up 0.3% in October and 10.4% higher than last year.

The goods component has a larger importance to the inputs to residential construction price index, representing around 60% of the total. On a monthly basis, the price of input goods to new residential construction was unchanged in October after rising 1.7% in September.

The input goods to residential construction index can be further broken down into two separate components, one measuring energy inputs with the other measuring remaining goods. The latter of these two components simply represents building materials used in residential construction, which makes up around 93% of the goods index.

Energy input prices fell 3.3% in October and were 64.8% higher than a year ago. Building material prices were up 0.5% in October and up 5.8% compared to one year ago. Energy prices fell monthly as No. 2 diesel fuel prices fell 4.6% over the month but was a substantial 115.2% higher than a year ago. Outside of energy products, particleboard and fiberboard prices rose 5.4% over the month and were up 13.9% from a year ago. Softwood veneer and plywood prices were up 3.6% over the month and 24.5% higher than a year ago.

Prices for service inputs to residential construction rose 0.7% in October. On a year-over-year basis, service input prices were up 11.3%. The price index for service inputs to residential construction can be broken out into three separate components: a trade services component, a transportation and warehousing services component, and a services excluding trade, transportation, and warehousing component (other services).

The most significant component is trade services (around 60%), followed by other services (around 29%), and finally transportation and warehousing services (around 11%). The largest component, trade services, was up 13.2% from a year ago. The price of transportation and warehousing services has risen 24.6% from a year ago, while prices for other services were up 3.0% over the year.


This article was originally published by a eyeonhousing.org . Read the Original article here. .
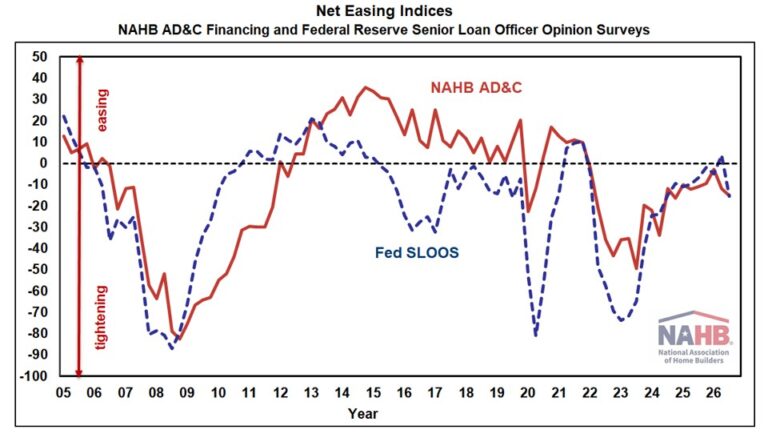

Credit conditions on loans for residential Land Acquisition, Development & Construction (AD&C) were still tightening in the third quarter of 2026, according to NAHB’s quarterly survey on AD&C Financing. The net easing index derived from the survey posted a third-quarter reading of -15.3 (the negative number indicating net tightening). This marks the nineteenth consecutive quarter during which residential builders and developers have reported tightening credit conditions.

The NAHB survey agrees closely with the third-quarter results reported by lenders in the Federal Reserve’s survey of senior loan officers, as the net easing index constructed from the Fed survey posted a third-quarter reading of -15.5. Although lenders previously reported a slight easing in 2026 Q2, lenders have generally agreed with builders and developers that credit conditions have been tightening since the beginning of 2022. The Fed survey’s net easing index was in negative territory (indicating net tightening) for 18 of the past 19 quarters.

More details from the Fed’s survey of lenders—including measures of demand and net easing for residential mortgages—appeared in a previous post.

Meanwhile, measures on the cost of AD&C credit exhibited a combination of relatively small quarter-to-quarter changes, signaling no clear trend in either direction. The average contract interest rate declined from  8.09% in the second quarter to 7.83% in the third quarter on loans for land development, but increased for the other three categories of loans tracked in the NAHB AD&C survey: from 7.77% to 8.08% on loans for land acquisition, from 7.28% to 7.72% on loans for speculative single-family construction, and from 7.01% to 7.27% on loans for pre-sold single-family construction.

However, the initial points charged by lenders declined on all four categories of AD&C loans in the third quarter: from 1.05% to 0.86% on loans for land acquisition, from 1.05% to 0.97% on loans for land development, from 0.85% to 0.71% on loans for speculative single-family construction, and from 0.71% to 0.51% on loans for pre-sold single-family construction.

Those changes left the average effective interest rate (taking both contract rate and initial points into account) essentially unchanged at 11.83% (compared 11.82% in the second quarter) on loans for speculative single-family construction. The average effective rate increased from 10.43% to 10.55% on loans for land acquisition, but declined from 12.59% to 11.69% on loans for land development, and from 11.67% to 11.47% on loans for pre-sold single-family construction.

The NAHB AD&C survey also revealed that 32% of respondents who built single-family homes during the third quarter of 2026 financed some of their homes with a construction-to-permanent (one-time-close) loan made to the ultimate home buyer. On average, 58% of the homes these respondents built were financed in this manner.

While the market for residential mortgages has been showing signs of stress recently—including a recent decline in mortgage applications and increase in delinquencies—it is important not to overlook the role access to AD&C credit plays in helping builders and developers expand the supply of affordable housing.

More detail on credit conditions for residential builders and developers is available on NAHB’s AD&C Financing Survey web page.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


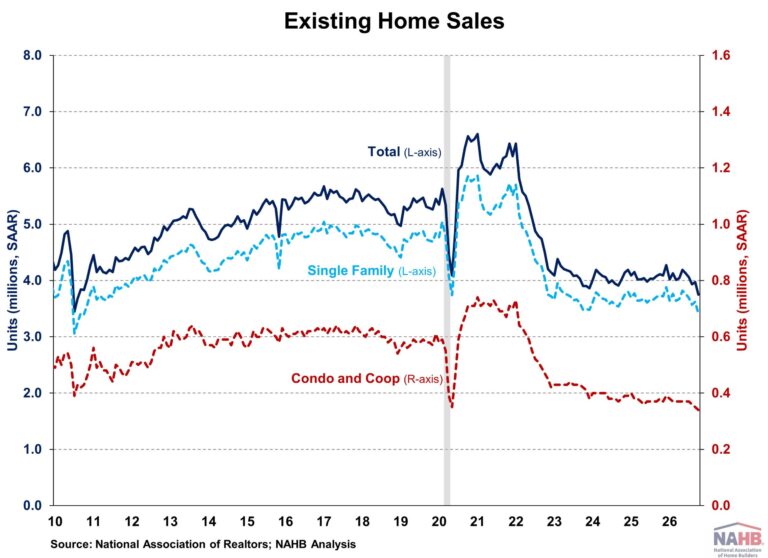
After a brief rebound last month, existing home sales plummeted to a 16-year low in October. With mortgage rates back above 7% since mid-September and home prices still elevated, buyers continued to stay on the sidelines. Sales declined across all four regions, with the West hitting a record low while the Midwest and South fell to decade lows. As buyers wait for rate relief, homes are sitting on the market longer, resulting in for-sale inventory climbing close to pre-pandemic levels.

Total existing home sales, including single-family homes, townhomes, condominiums, and co-ops, fell 5.5% to a seasonally adjusted annual rate of 3.75 million in October, according to the National Association of Realtors (NAR). This marked the lowest level since August 2010. On a year-over-year basis, sales were 8.8% lower than a year ago.

The existing home inventory level was 1.59 million units in October, up 1.3% from September and 4.6% from a year ago. At the current sales rate, October unsold inventory sits at a 5.1-months’ supply, up from 4.7-months in September and 4.4-months a year ago. This was the highest months’ supply since November 2015. Inventory between 4.5 to 6 months’ supply is generally considered a balanced market.

Homes stayed on the market for a median of 35 days in October, up from 33 days in the previous month and 34 days in October 2025.

The first-time buyer share was 29% in October. The share was down from 31% in September and 32% from a year ago.

The October all-cash sales share was 29% of transactions, up from 27% last month but unchanged from October 2025. All-cash buyers are less affected by changes in interest rates.

The October median sales price of all existing homes was $416,700, up 0.4% from last year. This marks the 40th consecutive month of year-over-year increases. The median condominium/co-op price in October was up 0.3% from a year ago at $365,100. Recent gains for home inventory will put downward pressure on resale home prices in most markets in 2026.

Existing home sales in October were mixed across the four major regions. Sales fell in the West (-9.7%), South (-6.5%) and Midwest (-3.2%), while unchanged the Northeast. On a year-over-year basis, sales decreased in all four regions, ranging from 4.1% in the Northeast to 14.5% in the West.

The Pending Home Sales Index (PHSI) is a forward-looking indicator based on signed contracts. The PHSI fell from 71.2 to 66.0 in September, the lowest level since NAR began tracking in 2001. On a year-over-year basis, pending sales were 11.3% lower than a year ago according to the National Association of Realtors’ data.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


Demand for all types of residential mortgages was significantly weaker, while lending standards for most were essentially unchanged in the third quarter of 2026, according to the recent release of the Senior Loan Officer Opinion Survey (SLOOS). For commercial real estate (CRE) loans, lending standards for construction & development were moderately tighter, while multifamily loans were modestly tighter. Compared to the previous quarter, demand for construction & development and multifamily loans was also significantly weaker.

The Federal Reserve held their key short-term interest rate (i.e., Fed Funds) steady at a target range of 3.75% to 4.00% during their October meeting, after a 25 basis point rate hike in September. Since Chairman Warsh has begun presiding over the Fed, the phrase “The Committee will deliver price stability” has appeared in all four press release statements after each Federal Open Market Committee (FOMC) meeting. This is signaling a more hawkish direction for monetary policy, especially given current inflation levels. As a result, NAHB is forecasting a rate hike during the December meeting which will precipitate a lengthy pause.

Residential Mortgages

In the third quarter of 2026, four of seven residential mortgage loan categories saw a positive net easing index for lending conditions: Non-Qualified Mortgage (QM) jumbo, QM jumbo, non-QM non-jumbo, and QM non jumbo non-GSE-eligible.  An additional two (Government and GSE-eligible) recorded a neutral reading (i.e., near 0). Subprime was the only residential mortgage loan category to record a negative value (-20.0), the lowest reading since the first quarter of 2023.

All seven residential mortgage loan categories reported significantly weaker demand in the third quarter of 2026, with six having a net percentage of -30% or lower. The average net easing index value (-32.2) across all seven residential mortgage categories is the lowest since Q4 2023 (-49.0).

Commercial Real Estate (CRE) Loans

For the CRE loan categories, multifamily and construction & development loans registered net easing indices of -8.8 and -15.5 , respectively, in the third quarter of 2026. x In both cases, this represented the lowest reading in two years.  

The net percentage of banks reporting stronger demand was -25.9% and -22.8% for construction & development and multifamily loans, respectively, with a negative number indicating weaker demand. Both CRE categories experienced their lowest net demand percentages in over two years.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


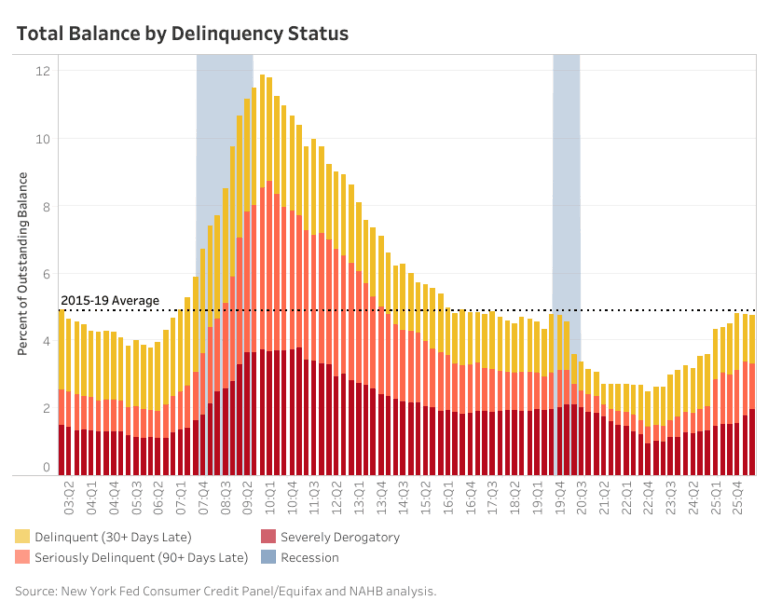
Household debt delinquency rates increased in the third quarter of 2026 as the share of delinquent balances and the transition to seriously delinquent debt increased. According to the latest Quarterly Report on Household Debt and Credit from the Federal Reserve Bank of New York, about 5.0% of outstanding household debt balances were in some stage of delinquency, an increase of 0.3 percentage points (pp) from the previous quarter. Total household debt balances that were seriously delinquent (at least 90 days delinquent) also edged up slightly from 3.3% in the second quarter to 3.4%.

The deterioration occurred across several consumer loan categories. The serious delinquency rate for auto loans increased 0.2 pp to 5.7%, while mortgage delinquency rate increased 0.1 pp to 1.1%. In contrast, the serious delinquency rate for credit cards edged lower to 12.9%, although credit cards continued to have the highest rate among the major debt categories.

Student loans displayed continued deterioration. The share of student loan balances that were seriously delinquent increased to 10.9%, from 10.6% in the second quarter. This marked a further increase in the proportion of student loan debt classified as seriously delinquent following the resumption of delinquency reporting.

The flow of balances newly entering a serious delinquency stage showed a more mixed picture. Overall, 2.6% transitioned into serious delinquency during the third quarter, unchanged from the previous quarter. The share of student loan balances transitioning into serious delinquency declined to 7.7%, from 7.8% in the previous quarter. This followed a much sharper decline in the second quarter, when the transition rate dropped from 10.9% to 7.8%.

Credit card transitions also improved slightly. The share of credit card balances newly entering serious delinquency decreased to 6.9%, from 7.0% in the second quarter, marking the third consecutive quarterly decline.

Mortgage transitions, however, continued to move in the opposite direction. The share of mortgage balances newly entering serious delinquency increased to 1.6%, from 1.5% in the previous quarter. This category has been gradually trending upward in recent years, indicating continued deterioration in mortgage credit performance. Auto loan transitions remained relatively steady at 3.0%.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


Consumer credit growth accelerated in the third quarter of 2026, with both revolving and nonrevolving credit increasing at their fastest quarterly rates since 2022. Total outstanding consumer credit reached $5.22 trillion, continuing an upward trend that has strengthened over the past year. The acceleration comes amid elevated borrowing costs, although interest rates on both auto loans and credit cards continue to edge lower. 

According to the Federal Reserve’s G.19 Consumer Credit Report, total outstanding U.S. consumer credit reached $5.22 trillion in the third quarter of 2026. This marked a 4.21% increase at a seasonally adjusted annual rate (SAAR) from the second quarter, the highest quarterly increase since 2022. Compared to a year ago, total outstanding credit increased 3.01%, the highest growth rate in three years. 

Nonrevolving Credit  

Nonrevolving credit, which is primarily made up of student and auto loans (the G.19 report excludes mortgage loans), reached $3.86 trillion (SA) in the third quarter of 2026. This marks a 4.22% increase (SAAR) from the previous quarter, the highest quarterly increase since 2022. Additionally, nonrevolving credit rose 2.57% compared to one year ago, continuing the upward trend over the last five quarters.  

Student loans make up the largest share of nonrevolving credit, accounting for 49% of the total. In the third quarter of 2026, outstanding student loan credit reached $1.88 trillion (NSA), up 2.81% from a year earlier. 

The other large component of nonrevolving credit is auto loans. Auto loans reached a level of $1.59 trillion (NSA), showing a year-over-year increase of 1.89%, the largest increase in the last ten quarters. Auto loan rates for a 60-month new car stood at 7.54% (NSA) for the third quarter of 2026, 10 basis points lower than a year ago. Auto loan rates have continued to decline year-over-year for the last eight quarters but remain higher than pre-pandemic levels. 

Revolving Credit 

Revolving credit, which is primarily made up of credit card balances, rose to $1.37 trillion (SA) in the third quarter of 2026. This represents a 4.21% increase (SAAR) from the previous quarter and a 4.25% increase year-over-year. 

Although credit card rates have hovered near historic highs since Q4 2022, they have shown modest year-over-year declines over the past seven quarters. The average credit card rate held by commercial banks (NSA) stood at 21.19% in the third quarter of 2026, a drop of 20 basis points from a year earlier.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


In this episode of The Houzz Guest, host Dorcas Adewole sits down with Kevin O’Connor, longtime host of PBS home renovation series This Old House and Ask This Old House — which is celebrating its 25th anniversary season — to discuss how homeowners who plan to stay put should approach their next remodeling projects. O’Connor, who first appeared on Ask This Old House as a homeowner seeking advice, explains why thinking of your home in terms of “a decade or four” changes how you prioritize projects. He points to small maintenance issues, such as a water leak or a knocking furnace, that can become major problems if ignored. He also shares which projects are fine to DIY, which are best left to a pro and how to stretch a tight budget while working with a professional.

To wrap up the episode, O’Connor tackles three real-world design dilemmas from the Houzz community, offering advice on how to tell whether a house is “old,” where to save and splurge on a budget renovation, and whom to call first on a major remodel.

Watch or listen to The Houzz Guest on Houzz, YouTube, Spotify and Apple Podcasts.

See show notes