Tag

Affordability

Browsing


Single-family housing starts declined in September as builders faced higher financing, building material costs, and ongoing labor shortages.

Overall housing starts decreased 5.2% in September to a seasonally adjusted annual rate of 1.22 million units, according to a report from the U.S. Department of Housing and Urban Development (HUD) and the U.S. Census Bureau. This pace reflects the number of housing units builders would begin over the next 12 months if September’s activity were sustained.

Within the total, single-family starts decreased 4.6% to an 859,000 seasonally adjusted annual rate, the lowest level in a year. However, single-family starts were up 2.6% compared to September 2025. On a year-to-date basis, single-family starts are down 4.0%, reflecting continued challenges facing home builders. Given recent volatility, the three-month moving average provides a clearer signal, falling to 878,000 units.

Multifamily starts, which include apartment buildings and condominiums, decreased 6.7% from August to September to an annualized 362,000 pace. The three-month moving average for multifamily construction has trended lower to 415,000 units, and activity is 24.9% lower compared to year-earlier levels.

Regionally, on a year-to-date basis, combined single-family and multifamily starts were 8.3% higher in the Northeast, 0.3% lower in the South, 2.0% lower in the Midwest, and 6.3% lower in the West. Single-family starts declined across all four regions, reflecting ongoing challenges amid elevated construction costs and persistent housing affordability pressures.

The total number of housing units under construction stood at 1.28 million in September, down 3.3% from a year earlier. Single-family homes under construction stood at 587,000 units, a 2.8% year-over-year decline. Multifamily units under construction slowed to 693,000 units, down from peaks above 1 million units in December 2023 and 3.6% lower than a year ago.

Single-family completions slowed to an annualized rate of about 840,000 units, down 11.0% from a year earlier. Multifamily completions for buildings with five or more units declined 20.4% year over year to a 339,000-unit pace. On a year-to-date basis, total completions across both sectors was down 12.5%.

Looking ahead, overall permits edged down 0.2% in September to an annualized rate of 1.4 million units. Single-family permits declined 4.0% to an 845,000-unit rate and are down 4.8% compared to September 2025. Multifamily permits increased 6.1% to an annualized 555,000 pace but are down 0.2% from a year earlier. Looking at regional permit data on a year-to-date basis, total permits were 10.6% higher in the Northeast, 2.2% higher in the Midwest, but 3.2% lower in the South. Permit activity in the West was unchanged. For single-family permits, the Midwest was the only region to post an increase, rising 1.2%, reflecting relative strength in that region’s residential construction market.


This article was originally published by a eyeonhousing.org . Read the Original article here. .
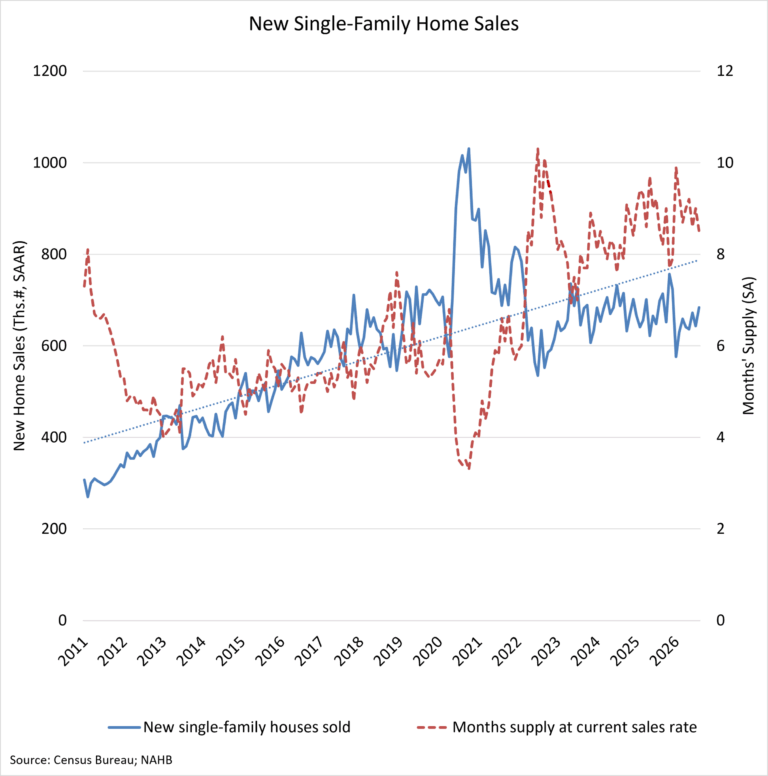

New home sales improved in August, but the monthly gain masked continued weakness in the broader new-home market. Elevated mortgage rates and ongoing affordability challenges continue to constrain demand, with new home sales remaining below last year’s pace and year-to-date sales lower than in 2025.

Despite the monthly increase, housing affordability remains a significant challenge for prospective buyers. The average 30-year fixed mortgage rate reached 6.95% in mid-September, its highest level since January 2025, according to Freddie Mac.

Sales of newly built single-family homes increased 6.4% in August to a seasonally adjusted annual rate of 684,000, following an upwardly revised July estimate, according to the U.S. Department of Housing and Urban Development and the U.S. Census Bureau. This represented a 2.0% decline from a year earlier. A new home sale is recorded when a contract is signed, or a deposit is accepted, regardless of the stage of construction. The seasonally adjusted annual rate reflects the pace of sales that would occur over a 12-month period if current conditions persist.

New single-family home inventory in August was unchanged from July at 483,000 units but fell 2.0% from a year ago. At the current sales pace, the months’ supply of new homes stood at an elevated 8.5 months, about the same level as a year ago. A five- to six-month inventory level generally indicates a balanced market.

Combined new and existing home inventory has edged higher in recent months, with the total months’ supply reaching 5.3 months. Inventory conditions in the existing home market have gradually improved in recent months. Moderating prices across both markets have helped support buyer demand amid ongoing affordability concerns.

At the end of August, there were 112,000 completed, ready-to-occupy homes available for sale on a non-seasonally adjusted basis. Completed homes accounted for approximately one-quarter of total inventory, while homes under construction made up 54%. The remaining share of homes sold in August had not yet started construction at the time the sales contract was signed.

Home prices remained relatively stable despite the slowdown in sales activity, reflecting incentives provided by builders. The median new home sale price was $393,700, up 0.4% from July but down 5.8% compared to a year ago. Homes priced between $300,000 and $499,999 accounted for half of all new home sales, while 22% of sales were priced below $300,000, underscoring ongoing affordability challenges for entry-level buyers. The remaining 26% of sales were priced above $500,000. It is worth noting that the share of homes priced below $300,000 has increased in recent months, while the share priced over $500,000 has decreased.

Regional performance was mixed in August. The Midwest posted the strongest monthly gain in sales, rising 84.9% from July, followed by the South, which was up 6.9%. In contrast, sales declined in both the Northeast and West, with the Northeast experiencing the sharpest drop, falling 36.1% from the previous month. The West was down 15.2%.

Compared with August 2025, the Midwest and the South recorded year-over-year gains, with sales increasing 22.5% in the Midwest and 3.4% in the South. Sales declined 20.7% in the Northeast and 26.8% in the West.

On a year-to-date basis, regional trends were similarly uneven. New home sales were unchanged in the Northeast. Meanwhile, sales were down 0.6% in the Midwest, 1.0% in the South, and 10.0% in the West.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


Elevated borrowing costs, rising inflation and broad economic uncertainty continue to curb buyer demand and hold back new home sales.

Sales of newly built single-family homes declined 10.5% in July to a seasonally adjusted annual rate of 607,000, following a sharply upwardly revised June estimate, according to newly released data from the U.S. Department of Housing and Urban Development and the U.S. Census Bureau. The pace of new home sales was 6.3% lower than a year earlier per the July data. The July sales pace was the slowest since January of this year. Mortgage rates increased from 6.1% to above 6.6% from January to July.

NAHB surveys show that a majority of builders continue to offer sales incentives, including mortgage rate buydowns, to support new home sales. Despite these efforts, the single-family home building market is on track for a second consecutive annual decline in 2026. New home sales are down more than 4% on a year-to-date basis. Nonetheless, NAHB surveys show community builders continue to outperform the broader market.

New single-family home inventory in July rose to 488,000 units, up 1.9% from June, and down 1.6% compared to a year ago. This represents an elevated 9.6 months’ supply at the current building pace, the highest measure since January.

While overall new single-family inventory increased in July, the composition of that inventory continues to change. The number of completed, ready-to-occupy new single-family builds has fallen from a non-seasonally adjusted 132,000 at the start of 2026 to 114,000 in July, as builders slowed the pace of construction. Homes in inventory and under construction have increased from 247,000 in January to 262,000 in July. And homes not started construction but available for purchase increased from 96,000 in January to 119,000 in July.

Combined new and existing home inventory continues to rise, per NAHB estimates. Summing new and existing single-family homes available for sale, and adjusting by the weighted sales rate for each housing market, combined new and existing home months’ supply inventory increased to a slightly above balanced level of 5.3 in July. As noted on the graph below, this marks the highest combined months’ supply measure since late 2014.

The median new home sales price in July fell 2.3% from June to $393,800 and was down 0.9% from a year ago. The new home sales market is showing relative strength at the higher end of the market. The market share of new home sales priced above $800,000 increased from 5% a year ago to 8% in July. 

Regionally, on a year-to-date basis, new home sales are up 8.8% in the Northeast but fell in the other three regions, with declines of 6.4% in Midwest, 3.7% in the South and 6.4% in the West.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


After three consecutive quarters of modest improvement, housing affordability worsened in the second quarter as higher mortgage rates, rising construction costs and economic uncertainty weighed on the market, according to the latest data from the National Association of Home Builders (NAHB)/Wells Fargo Cost of Housing Index (CHI).

The CHI results from the second quarter of 2026 show that a family earning the nation’s median income of $106,800 needed 34% of its income to cover the mortgage payment on a median-priced new home. Low-income families, defined as those earning only 50% of median income, would have to spend 67% of their earnings to pay for the same new home.

The percentage of a family’s income needed to purchase a new home rose from 32% in the first quarter of 2026 to 34% in the second quarter, driven by a more than 30-basis point rise in the average mortgage rate and a 2% increase in the median price of a new home. The low-income CHI also rose 65% to 67% over that period.

The figures are higher for the purchase of existing homes in the U.S. A typical family would have to pay 36% of their income for a median-priced existing home while a low-income family would need to pay 71% of their earnings to make the same mortgage payment.

The U.S. data for the percentage of earnings needed to purchase a new home in the second quarter is based on a national median new home price of $410,700 and median income of $106,800. The second quarter median new home price is up 2% from $403,200 in the first quarter. Meanwhile, the corresponding price for an existing home rose much more sharply (8%) in the second quarter to $434,900 from $404,300 in the previous quarter. The average 30-year mortgage rate moved higher from 6.20% in the first quarter to 6.51% in the second quarter.

CHI is also available for 175 metropolitan areas, calculating the percentage of a family’s income needed to make the mortgage payment on an existing home based on the local median home price and median income in those markets.

In eight out of 175 markets in the second quarter, the typical family is severely cost-burdened (must pay more than 50% of their income on a median-priced existing home). In 77 other markets, such families are cost-burdened (need to pay between 31% and 50%). There are 90 markets where the CHI is 30% of earnings or lower.

The Top 5 Severely Cost-Burdened Markets

San Jose-Sunnyvale-Santa Clara, Calif., was the most severely cost-burdened market on the CHI, where 82% of a typical family’s income is needed to make a mortgage payment on an existing home. This was followed by:

San Francisco-Oakland-Fremont, Calif. (71%)
Urban Honolulu, Hawaii (70%)
San Diego-Chula Vista-Carlsbad, Calif. (68%)
Naples-Marco Island, Fla. (60%)

Low-income families would have to pay between 121% and 164% of their income in all five of the above markets to cover a mortgage.

The Top 5 Least Cost-Burdened Markets

By contrast, Decatur, Ill., was the least cost-burdened market on the CHI, where typical families needed to spend just 16% of their income to pay for a mortgage on an existing home. Rounding out the least burdened markets are:

Elmira, N.Y. (17%)
Peoria, Ill. (18%)
Springfield, Ill. (20%)
Davenport-Moline-Rock Island, Iowa-Ill. (20%)

Low-income families in these markets would have to pay between 31% and 39% of their income to cover the mortgage payment for a median-priced existing home.

Visit nahb.org/chi for tables and details.


This article was originally published by a eyeonhousing.org . Read the Original article here. .
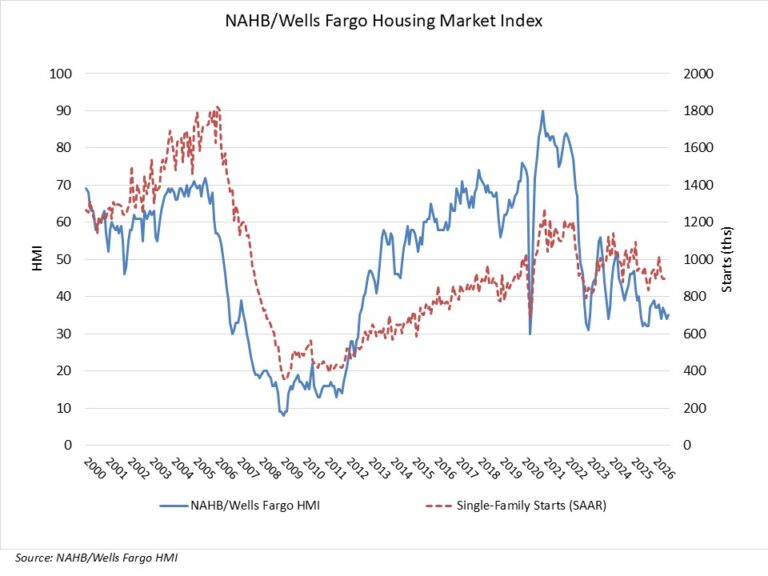

Builder sentiment remains muted from economic and geopolitical uncertainty, elevated mortgage rates and rising construction costs.

Builder confidence in the market for newly built single-family homes inched up one point to 35 in August, according to the National Association of Home Builders (NAHB)/Wells Fargo Housing Market Index (HMI).

August marked the 16th straight month that at least 30% of builders reported cutting prices to support demand, as well as the 16th consecutive month with the HMI below 40. Custom home builders continue to report stronger market conditions than spec builders, reflecting better conditions at the higher end of the market. Smaller, less dense markets are also outperforming larger metropolitan areas, and smaller builders report relatively stronger conditions than larger builders.

Rising gas and diesel prices are pushing up material costs, and spec home building remains weak as many prospective buyers stay on the sidelines. However, the Midwest remains a bright spot for the home building industry, with new home sales up in that region more than 2% so far in 2026.

The latest HMI survey also revealed that 35% of builders cut prices in August, down from 37% in July, and unchanged from June (35%). The average price reduction was 6% in August, the same rate as the previous month. The use of sales incentives was 63% in August, unchanged from the previous month.

Derived from a monthly survey that NAHB has been conducting for more than 40 years, the NAHB/Wells Fargo HMI gauges builder perceptions of current single-family home sales and sales expectations for the next six months as “good,” “fair” or “poor.” The survey also asks builders to rate traffic of prospective buyers as “high to very high,” “average” or “low to very low.” Scores for each component are then used to calculate a seasonally adjusted index where any number over 50 indicates that more builders view conditions as good than poor.

The index measuring current sales conditions increased two points to 39, while the indexes for future sales expectations and prospective buyer traffic held steady at 43 and 23, respectively.

Looking at the three-month moving averages for regional HMI scores, the Northeast fell one point to 44, the Midwest held steady at 45, the South fell two points to 31 and the West was unchanged at 27.

The HMI tables can be found at nahb.org/hmi.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


Affordability challenges continued to weigh on the new-home market in June, as elevated mortgage rates, rising inflation and broader economic uncertainty kept many prospective buyers on the sidelines.

Sales of newly built single-family home rose 1.6% in June to a seasonally adjusted annual rate of 628,000, up from an upwardly revised May estimate, according to newly released data from the U.S. Department of Housing and Urban Development and the U.S. Census Bureau. The pace of new home sales is down 5.6% from a year earlier.

New home sales are down 5.2% on a year-to-date basis, as housing demand remains lackluster amid affordability challenges. At the regional level, only the Midwest has seen gains for new home sales thus far in 2026.

Builders continue to use incentives to support sales, with NAHB survey data showing that 62% of builders offered some form of incentive in June.

New home sales are gaining some momentum at the more affordable range of the market, with homes priced below $300,000 accounting for 23% of June sales, up from 16% a year earlier. However, that price point is generally only achievable in markets with lower development and construction costs, particularly with respect to lower state and local regulatory costs.

A new home sale occurs when a sales contract is signed, or a deposit is accepted. The home can be in any stage of construction: not yet started, under construction or completed. In addition to adjusting for seasonal effects, the June reading of 628,000 units is the number of homes that would sell if this pace continued for the next 12 months.

New single-family home inventory in June was virtually unchanged at 485,000 units, down 0.2% from May, and down 3.2% compared to a year ago. This represents an elevated 9.3 months’ supply at the current building pace. According to NAHB analysis, due to rising resale single-family inventory and elevated new construction inventory, combined new and existing home inventory stands at just above a 5.2 months supply, the highest level since the fall of 2014.

The median new home sale price in June fell 3.3% from May to $398,300, and was down 2.7% from a year ago, largely due to builder price cuts and some geographic shift in mix to the more affordable Midwest.

Regionally, on a year-to-date basis, new home sales are up 2.6% in the Midwest but fell in the other three regions, with declines of 4.7% in Northeast, 4.9% in the South and 10.1% in the West.


This article was originally published by a eyeonhousing.org . Read the Original article here. .
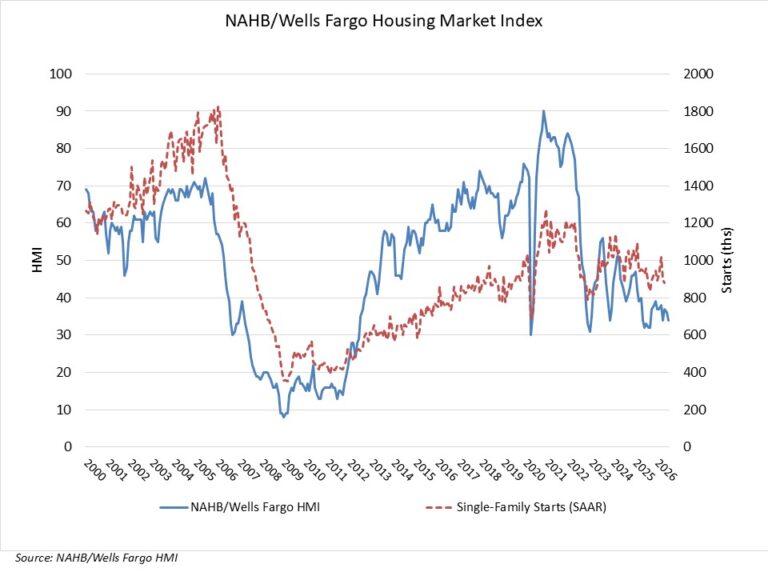

Economic uncertainty and persistent affordability challenges driven by rising material prices, high land costs, and elevated mortgage rates continue to weigh on builder sentiment.

Builder confidence in the market for newly built single-family homes fell two points to 34 in July, down from an upwardly revised reading of 36 in June, according to the National Association of Home Builders (NAHB)/Wells Fargo Housing Market Index (HMI). Sentiment has remained below 40 for 15 consecutive months, the longest such stretch since 2012.

With the HMI below 40 for 15 straight months, affordability remains the home building industry’s primary challenge, as elevated mortgage rates, costly land, rising material prices, and persistent skilled labor shortages continue to affect the market. Looking ahead, the newly enacted 21st Century ROAD to Housing Act is a positive step that will help expand housing supply and lower overall housing costs, although more policy change is needed at the state and local level.

The latest HMI survey also revealed that 37% of builders cut prices in July, up from 35% in June and 32% in May. The average price reduction was 6% in July, the same rate as the previous month. The use of sales incentives was 63% in July, up slightly from 62% in June, and marking the 16th consecutive month this share has reached 60% or higher.

Derived from a monthly survey that NAHB has been conducting for more than 40 years, the NAHB/Wells Fargo HMI gauges builder perceptions of current single-family home sales and sales expectations for the next six months as “good,” “fair” or “poor.” The survey also asks builders to rate traffic of prospective buyers as “high to very high,” “average” or “low to very low.” Scores for each component are then used to calculate a seasonally adjusted index where any number over 50 indicates that more builders view conditions as good than poor.

All of the HMI sub-indices posted declines in July. The HMI index gauging current sales conditions fell one point to 37, the index measuring future sales dropped two points to 43 and the index charting traffic of prospective buyers posted a two-point decline to 23.

Looking at the three-month moving averages for regional HMI scores, the Northeast rose one point to 45, the Midwest increased two points to 45, the South fell one point to 33 and the West dropped one point to 26. The HMI tables can be found at nahb.org/hmi.


This article was originally published by a eyeonhousing.org . Read the Original article here. .
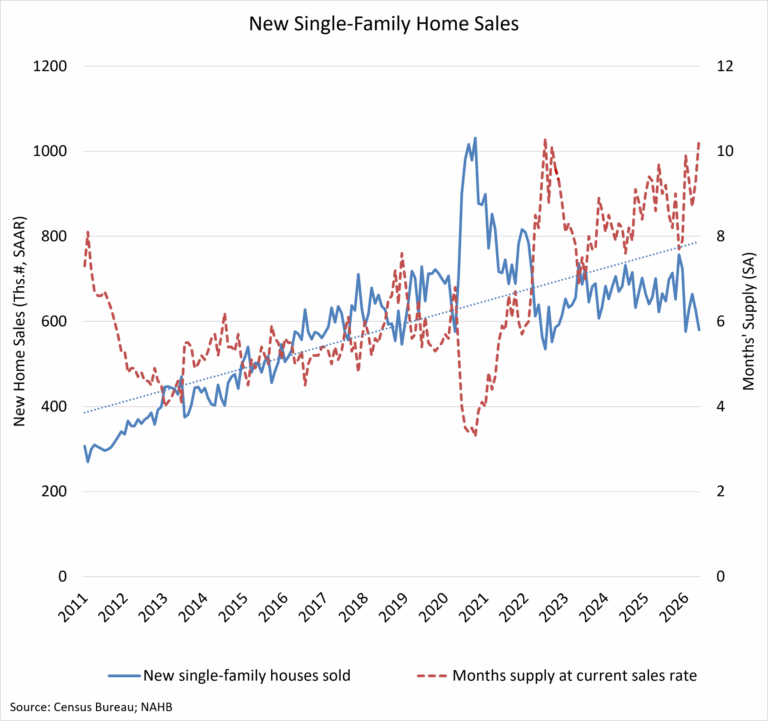

Elevated mortgage rates, rising inflation and economic uncertainty kept many buyers out of the market in May as consumers and builders continue to deal with challenging affordability conditions. While monthly sales activity softened, builders continue to operate in a market characterized by cautious buyers and persistent financing constraints.

Sales of newly built single-family homes fell 7.3% month-over-month in May to a seasonally adjusted annual rate of 580,000 units, according to the U.S. Department of Housing and Urban Development and the U.S. Census Bureau. This represented a 6.8% decline compared to a year earlier. A new home sale is recorded when a contract is signed, or a deposit is accepted, regardless of the stage of construction. The seasonally adjusted annual rate reflects the pace of sales that would occur over a 12-month period if current conditions persist.

New single-family home inventory totaled 496,000 units in May, up 2.3% from the prior month but down 1.4% from a year earlier. At the current sales pace, the months’ supply of new homes stood at an elevated 10.3 months, above the 9.7 months recorded one year ago. A five to six-months inventory level is generally considered to indicate a balanced market.      

Combined new and existing home inventory has edged higher in recent months, with the total months’ supply reaching 5.2 months. Inventory conditions in the existing home market have gradually improved in recent months. Moderating prices across both markets have helped support buyer demand amid ongoing affordability concerns.

At the end of May, there were 115,000 completed, ready-to-occupy homes available for sale on a non-seasonally adjusted basis, unchanged from a year earlier. Completed homes accounted for one-quarter of total inventory, while homes under construction made up 53%. The remaining 24% of homes sold in May had not yet started construction at the time the sales contract was signed.

Home prices remained relatively stable despite the slowdown in sales activity. The median new home sale price was $424,900, up 2.0% from April and essentially unchanged from a year ago. Homes priced between $300,000 and $499,999 accounted for half of all new home sales, while only 15% of sales were priced below $300,000, underscoring ongoing affordability challenges for entry-level buyers. The remaining 35% of the homes were priced above $500,000.

Regional performance was mixed in May. The Midwest posted the strongest monthly gain in sales, rising 16.2% from April, while the Northeast recorded a modest 3.0% increase. In contrast, sales declined in both the South and West, with the West experiencing the sharpest drop, falling 26.9% from the previous month.

Compared with May 2025, the Northeast was the only region to record a year-over-year gain, with sales increasing 17.2%. Sales declined 3.7% in the Midwest, 5.4% in the South, and 17.0% in the West.

On a year-to-date basis, regional trends were similarly uneven. New home sales increased 4.2% in the Midwest and 1.9% in the Northeast compared with the same period last year. Meanwhile, sales were down 8.2% in the South and 11.4% in the West, indicating that housing market weakness remains concentrated in the nation’s largest home building regions.


This article was originally published by a eyeonhousing.org . Read the Original article here. .
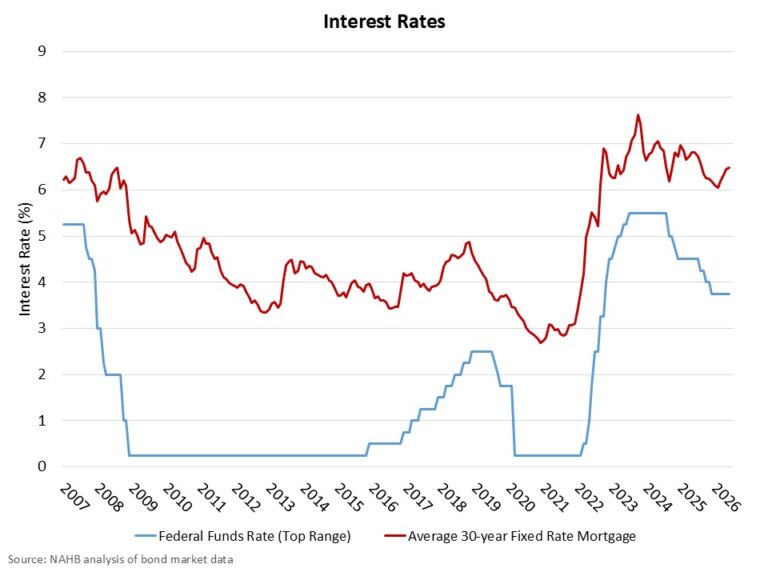

Builder sentiment remains subdued as rising material costs, elevated mortgage rates and ongoing affordability challenges continue to strain the housing market.

Builder confidence in the market for newly built single-family homes fell two points to 35 in June, according to the National Association of Home Builders (NAHB)/Wells Fargo Housing Market Index (HMI). This is the 14th straight month that sentiment has remained below 40, a streak not seen since 2011-2012 during the foreclosure crisis.

Costly and inefficient regulatory policy is clearly impeding the ability of builders to increase the housing supply. According to a new NAHB study, government regulation, taxes, fees and other costs add more than 26% to the price of an average single-family home. Easing permitting bottlenecks, density limits and inefficient zoning rules would help reduce costs and support the housing growth the nation needs.

The latest HMI survey also revealed that 35% of builders cut prices in June, up from 32% in May. The average price reduction was 6% in June, the same rate as the previous month. The use of sales incentives was 62% in June, up slightly from 61% in May, and marking the 15th consecutive month this share has reached 60% or higher.

Derived from a monthly survey that NAHB has been conducting for more than 40 years, the NAHB/Wells Fargo HMI gauges builder perceptions of current single-family home sales and sales expectations for the next six months as “good,” “fair” or “poor.” The survey also asks builders to rate traffic of prospective buyers as “high to very high,” “average” or “low to very low.” Scores for each component are then used to calculate a seasonally adjusted index where any number over 50 indicates that more builders view conditions as good than poor.

The HMI index gauging current sales conditions fell two points to 38 in June, the index measuring future sales held steady at 45 and the index charting traffic of prospective buyers remained unchanged at 25.

Looking at the three-month moving averages for regional HMI scores, the Northeast rose two points to 44, the Midwest held constant at 43, the South fell two points to 33 and the West dropped one point to 27. The HMI tables can be found at nahb.org/hmi.

Discover more from Eye On Housing

Subscribe to get the latest posts sent to your email.


This article was originally published by a eyeonhousing.org . Read the Original article here. .
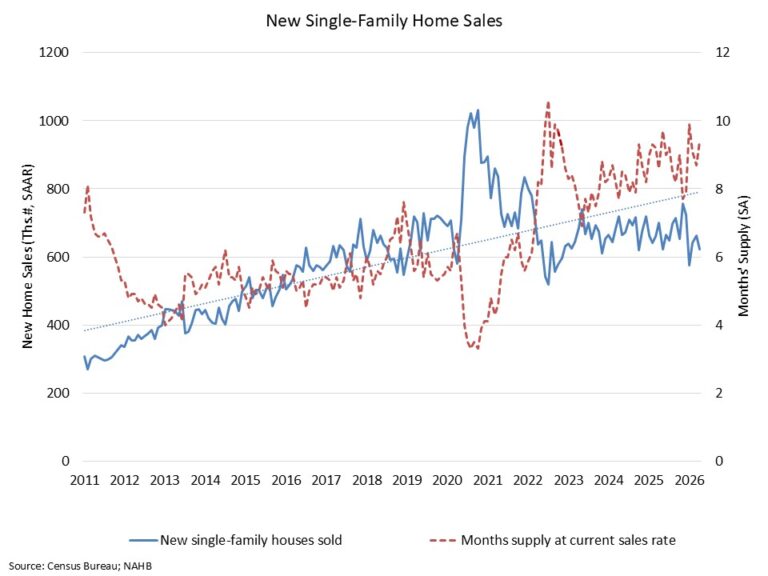

Elevated mortgage rates, higher inflation and economic uncertainty kept more buyers on the sidelines in April as ongoing affordability challenges continue.

Sales of newly built single-family homes fell 6.2% in April to a seasonally adjusted annual rate of 622,000, according to data from the U.S. Department of Housing and Urban Development and the U.S. Census Bureau. The pace of new home sales is down 11.3% from a year earlier.

Mortgage interest rates increased from a monthly average of 6.18% in March to 6.33% in April per Freddie Mac, dampening homebuyer demand. Rates moved higher again in May to just above 6.4% as oil prices and short-term inflation expectations increased.

New home sales are on track to decline in 2026 as mortgage rates are expected to remain elevated in the months ahead. The Midwest remains a bright spot, with sales up 7.3% year to date, compared with declines in the rest of the country. The Midwest benefits from relative advantages for homebuyer affordability.

A new home sale occurs when a sales contract is signed, or a deposit is accepted. The home can be in any stage of construction: not yet started, under construction or completed. In addition to adjusting for seasonal effects, the April reading of 622,000 units is the number of homes that would sell if this pace continued for the next 12 months.

New single-family home inventory in April rose to 489,000 units, up 1.7% compared to the previous month. This represents an elevated 9.4 months’ supply at the current building pace. Completed, ready-to-occupy inventory accounted for 122,000 homes in April, up 6.1% from a year ago but down from the cyclical peak of 128,000 in January.

The median new home sale price was $422,500, up 8.0% from March and up 2.2% from a year ago.

Regionally, on a year-to-date basis, new home sales are up 7.3% in the Midwest. New home sales are down 9.7% in the Northeast, 7.6% in the South and 9.5% in the West.


This article was originally published by a eyeonhousing.org . Read the Original article here. .
Pin It