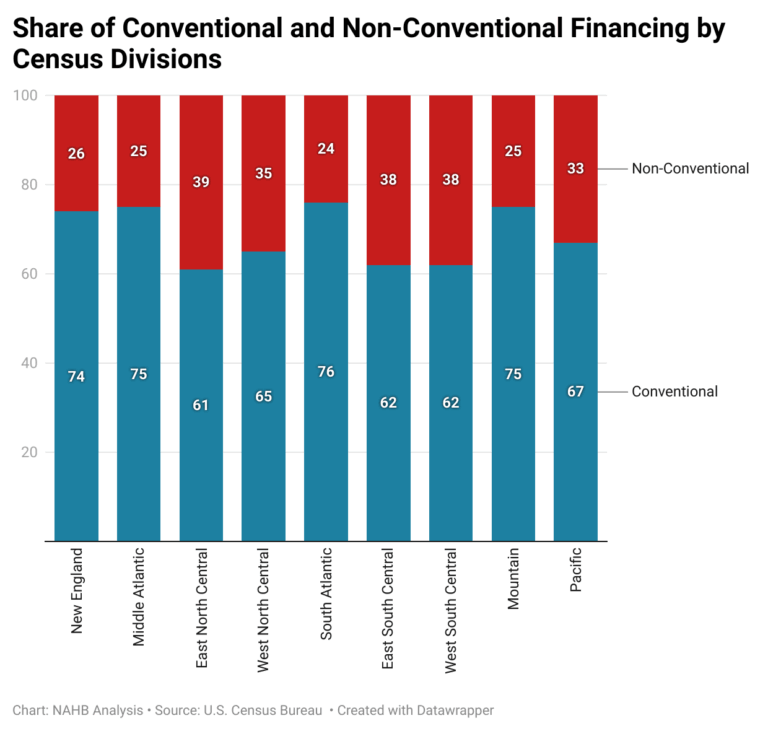
Nationwide, the share of non-conventional financing for new home sales accounted for 32.4% of the market, according to NAHB analysis of the 2025 Census Bureau Survey of Construction (SOC) data. This was 1.7 percentage points higher than the 2024 share of 30.7%. As in previous years, conventional financing dominated the market, accounting for 67.6% of sales, although this was down from 69.3% in 2024.
Non-conventional forms of financing (as opposed to conventional mortgage loans) include loans insured by the Federal Housing Administration (FHA), VA-backed loans, cash purchases, and other types of financing, such as financing through the Rural Housing Service, Habitat for Humanity, loans from individuals, or state- or local government mortgage-backed bonds. The reliance on non-conventional financing varied across the United States, with 43% of new home sales using non-conventional financing in the Pacific division, compared with just 18% of new single-family home sales in the Middle Atlantic division.
Nationwide, cash purchases and FHA-backed loans each represented the largest shares of non-conventional financing for new home purchases, accounting for 13% of all new home sales. Meanwhile, VA-backed loans accounted for a 4% market share in 2025, while other financing accounted for 2%.
Cash purchases led non-conventional financing in six of the nine Census divisions. The New England division recorded the highest share, where 32% of new home sales were cash purchases, followed by 20% in the East North Central division, 18% in the East South Central division, 15% in the Mountain division, 13% in the Middle Atlantic division, and 10% in the West North Central division.
FHA-backed loans accounted for the largest share of non-conventional financing in the Pacific division, representing 25% of new home sales, followed by the West South Central division at 21%. In contrast, no new homes sold in the New England division used FHA-backed loans.
VA-backed loans were most prevalent in the Mountain division, accounting for 9% of new home sales. Notably, in the New England and Middle Atlantic divisions, no homes were sold using VA-backed loans in 2025.
Other financing, such as the Rural Housing Service, Habitat for Humanity, loans from individuals, and state- or local government mortgage-backed bonds, accounted for the largest share in the East South Central division, where it represented 4% of new home sales. By comparison, the Mountain division reported the lowest share at just 1%.
This article was originally published by a eyeonhousing.org . Read the Original article here. .