Tag

Cost

Browsing


Material costs increased by 6.7% over the previous year, according to results from the survey for the July 2026 NAHB/Wells Fargo Housing Market Index (HMI).

A large majority (72.9%) of the builders responding to the survey reported that their cost of materials for the same house increased by up to 15% over the past year (at the time of the survey in early July). The most common response (28.4% of builders) was that material prices increased by 5% to 9.99%, followed by 22.4% who indicated a less than 5% change, and 22.1% who indicated 10% to 14.99%.

The median was an annual increase of 6.7% in material costs for the same house. This matches  the 6.7% annual increase in in the price of goods (including energy) used in new residential construction reported by NAHB in its recent post on the July Producer Price Index. If energy is excluded, the PPI for goods used in new residential construction increased by 5.0% over that period.

Not all builders experienced the same increase, however. According to the HMI survey, the median annual increase in material prices declines regularly with the size of the builder: from a high of 9.1% for builders who started 5 or fewer homes in 2025, down to only 1.8% for builders with 100 or more starts.

Several reasonable explanations for this tendency exist. For example, larger builders may have greater ability to stockpile materials when they anticipate price increases. Larger builders may also have longer-term contracts with suppliers, locking in current prices for an extended period. Finally, larger builders may be more likely to have special relationships with certain suppliers, allowing them to negotiate deferred price increases.

The price of materials is important, but it is only one of several factors creating housing affordability challenges in the U.S. Others include relatively high mortgage rates, shortages of skilled construction labor, and several different types of regulatory costs.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


Credit conditions on loans for residential Land Acquisition, Development & Construction (AD&C) were still tightening in the second quarter of 2026, according to NAHB’s quarterly survey on AD&C Financing. The net easing index derived from the survey posted a second-quarter reading of -12.0 (the negative number indicating net tightening). This marks the eighteenth consecutive quarter that residential builders and developers have reported tightening credit conditions.

In contrast, the similar net easing index based on the Federal Reserve’s survey of lenders moved slightly above zero, with a second-quarter reading of +3.7. This is the first time lenders reported easing credit conditions while builders and developers were simultaneously reporting tightening since NAHB began comparing the two series in 2013.

More details from the Fed’s survey of lenders—including measures of demand and net easing for residential mortgages—appeared in a previous post.

Among NAHB builders and developers who reported tighter credit conditions in the second quarter, 53% reported that one of the ways lenders tightened was by requiring personal guarantees or collateral not related to the project—putting the entire business, rather than just an individual project, at risk. Tied for second place on the list of common ways lenders were tightening (each reported by 47% of builders and developers) were increasing the interest rate, lowering the loan-to-value or loan-to-cost ratio, and refusing to make relationship loans.

Also in the second quarter, NAHB builders and developers generally reported a rising cost of credit, albeit with a few exceptions. The average contract rate increased on two of the four categories of loans tracked in the AD&C survey: from 7.42% to 7.77% on loans for land acquisition, and from 7.27% to 8.09% on loans for land development. Meanwhile, the contract rate actually declined at least slightly on the other two: from 7.31% to 7.28% on loans for speculative single-family construction, and from 7.19% to 7.01% on loans for pre-sold single-family construction.

On loans paid off as quickly as is typical in single-family construction, however, the initial points charged on the loans can be a particularly strong driver of overall credit cost. In the second quarter of 2026, average initial points increased on all four categories of AD&C loans: from 0.50% to 1.05% on loans for both land acquisition and land development, from 0.62% to 0.85% on loans for speculative single-family construction, and from 0.55% to 0.71% on loans for pre-sold single-family construction.

Those changes left the average effective interest rate (taking both contract rate and initial points into account) essentially unchanged at 11.67% (compared 11.68% in the first quarter) on loans for pre-sold single-family construction. On the other three types of AD&C loans, the average effective rate increased: from 9.36% to 10.43% on loans for land acquisition, from 10.15% to 12.59% on loans for land development, and from 11.22% to 11.82% on loans for speculative single-family construction. On all four categories of AD&C loans, the average effective rate in the second quarter of 2026 was over 0.6 percentage points higher than it had been at the end of 2025.

The role of elevated mortgage rates and their adverse effect on housing affordability have received considerable attention lately—for example, in Eye on Housing’s recent post on tepid existing home sales. Mortgage rates are not the only way the cost of credit affects housing markets, however. Access to AD&C credit at a reasonable cost plays an important role in enabling builders and developers to expand the supply of affordable housing.

More detail on credit conditions for residential builders and developers is available on NAHB’s AD&C Financing Survey web page.


This article was originally published by a eyeonhousing.org . Read the Original article here. .

A new NAHB study shows that, on average, regulations imposed by government at all levels account for $131,734, or 26.4%, of the final price of a new single-family home built for sale. Of this amount, $46,795 is due to a higher price for the finished lot, attributable to regulations imposed during the lot’s development. The remaining $84,939 is the result of regulatory costs imposed on the builder during construction, after the builder purchases the finished lot.

The individual line items in the above figure range from under $2,000 per home for the pure cost of delay during the construction phase of the project, to more than $40,000 for changes in building codes over the past 10 years.

Results show that the cost of regulation climbed at its fastest rate between consecutive surveys. The current estimate of $131,734 is over 40% higher than the $93,871 figure from the 2021 study, and more than double the NAHB’s initial estimate of $65,224 back in 2011.

The estimate of $46,795 in regulatory costs incurred during lot development is based largely on the “Land Developer Survey on Regulatory Costs” conducted by NAHB in March of 2026. The $84,939 estimate of regulatory costs during the construction phase is based largely on questions in the March 2026 survey for the NAHB/Wells Fargo Housing Market Index (HMI). Data from the two surveys were combined with information on average construction times, interest rates, profit margins etc. to produce estimates of regulatory costs as a percentage—either of the price of a lot purchased by a builder, or of the builder’s narrowly defined cost of construction. The percentages were then converted to dollars using the January 2026 average new home price of $499,500 from the first release of the U.S. Census Bureau’s New Residential Sales report. For more information on the methodology, including both survey questionnaires and a complete documentation of all other information incorporated into the estimates, please consult the full study.

Regulatory costs are one of several factors, including record increases of tariff rates on building materials, ongoing skilled labor shortage, a dearth of available lots and tighter lending conditions, currently limiting the supply of housing—particularly housing for the entry-level market, where additional inventory is most needed.


This article was originally published by a eyeonhousing.org . Read the Original article here. .
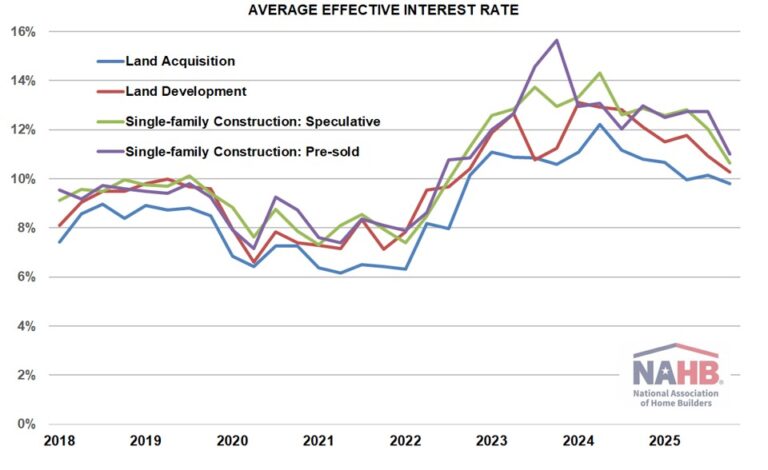

The cost of credit for residential construction and development declined in the fourth quarter of 2025,  according to NAHB’s quarterly survey on Land Acquisition, Development & Construction (AD&C) Financing. In particular, the average contract rate declined on all four categories of loans tracked in the survey: from 7.95% in the third quarter to 7.61% on loans for land acquisition, from 7.68% to 7.44% on loans for land development, from 7.89% to 7.47% on loans for speculative single-family construction, and from 7.90% to 7.16% on loans for pre-sold single-family construction.   

Meanwhile, the average initial points paid by builders and developers fell on three of the four types of AD&C loans: from 0.83% to 0.44% on loans for land development, from 0.75% to 0.34% on loans for speculative single-family construction, and from 0.67% to 0.37% on loans for pre-sold single-family construction. The only exception was loans specifically for land acquisition, on which the average initial points increased slightly—from 0.66% to 0.70%.

The small increase in points on land acquisition loans was not enough to offset the drop in the contract interest rate, however, so the average effective interest rate (which takes both the contract rate and initial points into account) declined across the board: from 10.15% to 9.81% on loans for land acquisition, from 10.92% to 10.28% on loans for land development, from 12.04% to 10.64% on loans for speculative single-family construction, and from 12.74% to 11.01%  on loans for pre-sold single-family construction.

In all four cases, this was the lowest the average effective rate has been since the period of generally rising interest rates in 2022.

Notwithstanding the drop in rates, builders and developers continued to report tightening credit conditions in the fourth quarter of 2025. The net easing index derived from NAHB’s AD&C survey posted a reading of -9.3 (the negative number indicating that credit has tightened since the previous quarter). This is quite similar to the results from the perspective of lenders reported in the Federal Reserve’s survey of senior loan officers. The net easing index derived from the Fed survey posted a reading of -1.8 in the fourth quarter. Both the NAHB and Fed survey have now reported consistently tightening credit conditions for 16 consecutive quarters. In both cases, however, the net easing index in Q4 2025  came closer to the break-even point of zero (between tightening and easing) than it has at any time since the first quarter of 2022. 

More details from the Fed’s survey of lenders—including measures of demand and net easing for residential mortgages—appeared in a previous post.

Also, in the NAHB AD&C survey, 35% of respondents who built single-family homes during the fourth quarter of 2025 reported financing some of the construction with a construction-to-permanent (one-time-close) loan made to the ultimate home buyer. On average, 59% of the homes these respondents built were financed in this manner.

More detail on credit conditions for residential builders and developers is available on NAHB’s AD&C Financing Survey web page.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


Construction costs account for 64.4% of the average price of a home, according to NAHB’s most recent Cost of Construction Survey.  In 2022, the share was 3.6 points lower, at 60.8%.  The latest finding marks a record high for construction costs since the inception of the series in 1998 and the fifth instance where construction costs represented over 60% of the total sales price.

The finished lot was the second largest cost at 13.7% of the sales price, down more than four percentage points from 17.8% in 2022.  The share of finished lot to the total sales price has fallen consecutively in the last three surveys, reaching a series low in 2024.

The average builder profit margin was 11.0% in 2024, up less than a percentage point from 10.1% in 2022.  

At 5.7% in 2024, overhead and general expenses rose when compared to 2022 (5.1%).  The remainder of the average home sale price consisted of sales commission (2.8%), financing costs (1.5%), and marketing costs (0.8%).  Marketing costs were essentially unchanged while sales commission and financing costs decreased compared to their 2022 breakdowns.

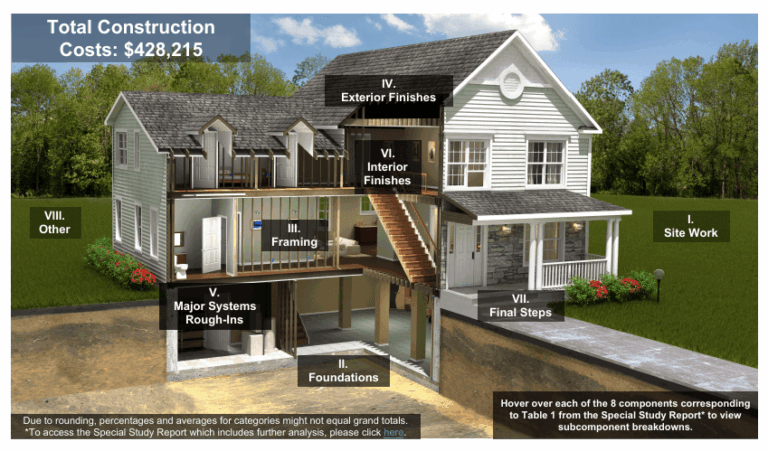
Construction costs were broken down into eight major stages of construction. Interior finishes, at 24.1%, accounted for the largest share of construction costs, followed by major system rough-ins (19.2%), framing (16.6%), exterior finishes (13.4%), foundations (10.5%), site work (7.6%), final steps (6.5%), and other costs (2.1%).

Explore the interactive dashboard below to view the costs and percentage of construction costs for the eight stages and their 36 components.

Table 1 shows the same results as the dashboard above in table format.  Please click here to be redirected to the full report (which includes historical results back to 1998).


This article was originally published by a
eyeonhousing.org . Read the Original article here. .


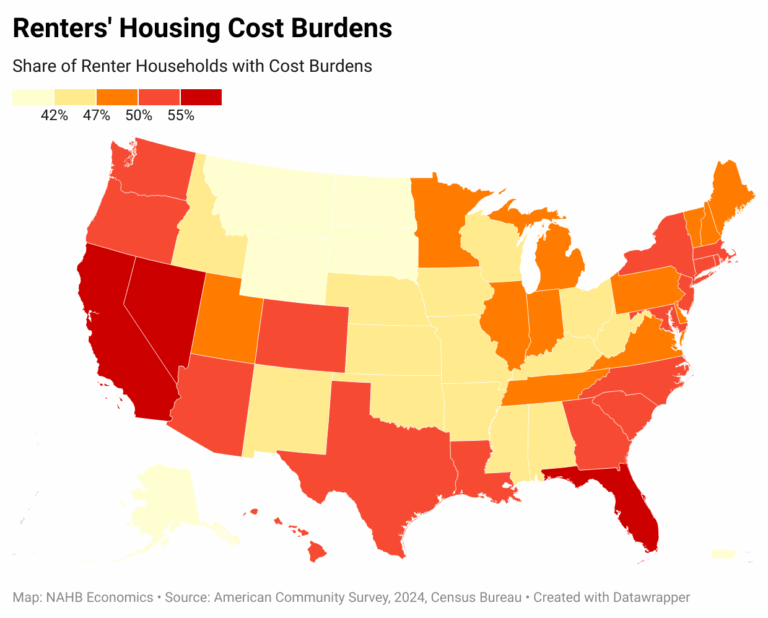
The housing affordability crisis continues to disproportionately affect renters, with more than half of renter households experiencing high-cost burdens — i.e., paying 30% or more of their income on rent and utilities. At the same time, current home owners, buoyed by significant home equity gains and locked in by below-market mortgage rates, are in a more advantageous financial position to weather the growing affordability crisis. According to the latest 2024 American Community Survey (ACS), more than half of all renter households (50.3%), or 23.2 million, are burdened by housing costs. Among home owners, this share is less than a quarter (24.3%) representing 21 million households. As a result, states and counties with higher shares of renters in their housing markets are more likely to have higher overall shares of households with cost burdens.

Geographically, Florida, Nevada, and California have the largest concentration of cost-burdened renters. In Florida, 60% of all renters pay more than 30% of their income on rent and utilities. In Nevada, the share is 57%, and in California, 55% of renters experience housing cost burdens. Even in states with comparatively low renter cost-burden rates—such as South Dakota, Alaska, and North Dakota—more than one-third of renters still spend 30% or more of their income on housing.

For home owners, cost-burden rates are generally lower, but the geographic pattern mirrors that of renters. California, Florida, and several Northeastern states report the highest shares of cost-burdened home owners. California faces the most severe affordability challenges, with one in three owners paying more than 30% of their income for housing. Florida and Hawaii follow closely, with 31% of existing home owners struggling to afford their homes.

At the opposite end of the spectrum, nine states in the Midwest and South report that fewer than 20% of homeowners are cost-burdened. West Virginia and North Dakota have the lowest rates, at just 16%.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


The cost of credit for residential Land Acquisition, Development & Construction (AD&C) eased in the first quarter of 2025, according to NAHB’s survey on AD&C Financing. During the quarter, the average contract interest rate declined on three of the four categories of loans tracked in the NAHB survey: from 8.48% in 2024 Q4 to 8.23% on loans for land acquisition, from 8.28% to 7.86% on loans for land development, and from 8.34% to 8.08% on loans for speculative single-family construction. The average rate on loans for pre-sold single-family construction meanwhile bucked the trend, increasing from 7.75% to 7.96%.

In addition to interest, lenders also typically charge initial points on the loans. The points can affect credit costs as much as the interest rate—especially for loans paid off as quickly as most of those for single-family construction. In the first quarter of 2025, average points declined from 0.75% to 0.74% on loans for land development, and from 0.67% to 0.45% on loans for pre-sold single-family construction; but increased from 0.55% to 0.71% on loans for land acquisition, and from 0.64% to 0.68% on loans for speculative single-family construction.

The change in points was sufficient to offset the increase in interest rates on loans for pre-sold single-family construction, but not the reduction in rates on the other three categories of AD&C loans. As a result, the average effective interest rate (calculated taking both the contract rate and initial points into account) declined in all four cases: from 10.79% to 10.68% on loans for land acquisition, from 12.12% to 11.50% on loans for land development, from 12.86% to 12.59% on loans for speculative single-family construction, and from 12.98% to 12.49% on loans for pre-sold single-family construction.

Except for what now looks like a temporary reversal for construction loans in 2024 Q4, the average effective rate on AD&C loans has been trending downward for about a year. This stands in contrast to the average rate on 30-year fixed-rate mortgages, which has levelled off and even started to edge up again after coming off its 2023 peak.

While the cost of AD&C credit was declining, the NAHB survey shows that lending standards on AD&C loans were still tightening in the first quarter, although the reports of tightening were less widespread than they had been at any other time over the past three years. The net easing index derived from the survey posted a 2025 Q1 reading of -10.0 (the negative numbers indicating that net credit had become tighter since the previous quarter). This is the closest the NAHB index has come to hitting the break-even point of zero since the first quarter of 2022.

At the same time, the similar net easing index derived from the Federal Reserve’s survey of senior loan officers posted a 2025 Q1 reading of -11.1. This is down slightly from the previous quarter, but still ranks as the second highest reading for the Fed index since the first quarter of 2022. The Fed survey of lenders and the NAHB survey of builders and developers have been telling very similar stories recently, especially over the past five quarters. More details from the Fed’s survey of lenders—including measures of demand and net easing for residential mortgages—are discussed in a previous post.

Perhaps surprisingly, given the above results on declining credit costs, raising interest rates (cited by 57% of builders and developers who reported that availability of credit had worsened in the first quarter) has displaced lowering the loan-to-value or loan-to-cost ratio (50%) as the number-one way NAHB members say lenders are tightening conditions on AD&C loans. It is important to remember that relatively few NAHB members reported worse credit availability in the first place in 2025 Q1, so these percentages are based on a relatively small sample. Tied for third place, each cited by 43% of builders and developers, are increasing documentation requirements and requiring personal guarantees or collateral not related to the project. Meanwhile, the share of builders and developers who say lenders are reducing the amount they are willing to lend fell to 36%—the lowest percentage for this mode of tightening since 2018.

More detail on credit conditions for residential builders and developers is available on NAHB’s AD&C Financing Survey web page.

Discover more from Eye On Housing

Subscribe to get the latest posts sent to your email.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


Kirk Riley DesignSave Photo
5. Tile With Restraint

Unless you’re planning a wet room, you don’t need to cover every inch with tile, Ghaly says. Not only is tiling just part of the room cheaper, both in terms of labor and materials, but also it’s often more practical.

“The advantage of part-tiling is that the bathroom becomes much more flexible,” he says. “For example, you can paint the rest of the walls, which means the bathroom can be redesigned more easily in the future, using different colors.

“Hanging pictures on bathroom walls is also becoming popular, and part-tiling gives you this option,” he adds.

When it comes to tile prices, Ghaly says, ceramic tiles are generally cheaper. “Imitation tiles — marble-look, for example — can be inexpensive yet will give your bathroom a similar luxury look and feel like the real thing.”

Shop for bathroom tile on Houzz


This article was originally published by a
www.houzz.com . Read the Original article here. .


Economic uncertainty, the threat of tariffs and elevated construction costs pushed builder sentiment down in March even as builders express hope that a better regulatory environment will lead to an improving business climate.

Builder confidence in the market for newly built single-family homes was 39 in March, down three points from February and the lowest level in seven months, according to the National Association of Home Builders (NAHB)/Wells Fargo Housing Market Index (HMI).

Builders continue to face elevated building material costs that are exacerbated by tariff issues, as well as other supply-side challenges that include labor and lot shortages. At the same time, builders are starting to see relief on the regulatory front to bend the rising cost curve, as demonstrated by the Trump administration’s pause of the 2021 IECC building code requirement and move to implement the regulatory definition of ‘waters of the United States’ under the Clean Water Act consistent with the U.S. Supreme Court’s Sackett decision.

Construction firms are facing added cost pressures from tariffs. Data from the HMI March survey reveals that builders estimate a typical cost effect from recent tariff actions at $9,200 per home. Uncertainty on policy is also having a negative impact on home buyers and development decisions.

The latest HMI survey also revealed that 29% of builders cut home prices in March, up from 26% in February. Meanwhile, the average price reduction was 5% in March, the same rate as the previous month. The use of sales incentives was 59% in March, unchanged from February.

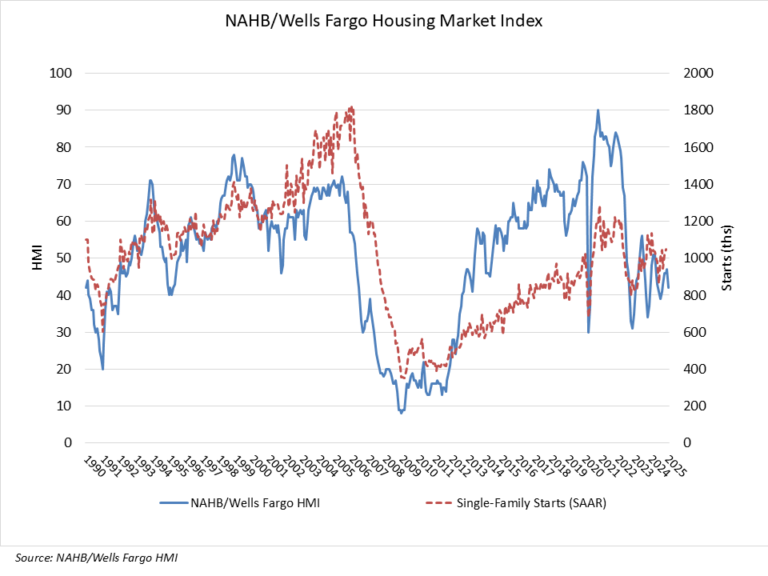
Derived from a monthly survey that NAHB has been conducting for more than 35 years, the NAHB/Wells Fargo HMI gauges builder perceptions of current single-family home sales and sales expectations for the next six months as “good,” “fair” or “poor.” The survey also asks builders to rate traffic of prospective buyers as “high to very high,” “average” or “low to very low.” Scores for each component are then used to calculate a seasonally adjusted index where any number over 50 indicates that more builders view conditions as good than poor.

The HMI index gauging current sales conditions fell three points to 43 in March, its lowest point since December 2023. The gauge charting traffic of prospective buyers dropped five points to 24 while the component measuring sales expectations in the next six months held steady at 47.

Looking at the three-month moving averages for regional HMI scores, the Northeast fell three points in March to 54, the Midwest moved three points lower to 42, the South dropped four points to 42 and the West posted a two-point decline to 37. The HMI tables can be found at nahb.org/hmi.

Discover more from Eye On Housing

Subscribe to get the latest posts sent to your email.


This article was originally published by a eyeonhousing.org . Read the Original article here. .

Builder sentiment fell sharply in February over concerns on tariffs, elevated mortgage rates and high housing costs.

Builder confidence in the market for newly built single-family homes was 42 in February, down five points from January and the lowest level in five months, according to the National Association of Home Builders (NAHB)/Wells Fargo Housing Market Index (HMI).

While builders hold out hope for pro-development policies, particularly for regulatory reform, policy uncertainty and cost factors created a reset for 2025 expectations in the most recent HMI. Uncertainty on the tariff front helped push builders’ expectations for future sales volume down to the lowest level since December 2023.

With 32% of appliances and 30% of softwood lumber coming from international trade, uncertainty over the scale and scope of tariffs has builders further concerned about costs. Reflecting this outlook, builder responses collected prior to a pause for the proposed tariffs on goods from Canada and Mexico yielded a lower HMI reading of 38, while those collected after the announced one-month pause produced a score of 44. Addressing the elevated pace of shelter inflation requires bending the housing cost curve to enable adding more attainable housing.

Incentive use may also be weakening as a sales strategy as elevated interest rates reduce the pool of eligible home buyers. The latest HMI survey also revealed that 26% of builders cut home prices in February, down from 30% in January and the lowest share since May 2024. Meanwhile, the average price reduction was 5% in February, the same rate as the previous month. The use of sales incentives was 59% in February, down from 61% in January.

Derived from a monthly survey that NAHB has been conducting for more than 35 years, the NAHB/Wells Fargo HMI gauges builder perceptions of current single-family home sales and sales expectations for the next six months as “good,” “fair” or “poor.” The survey also asks builders to rate traffic of prospective buyers as “high to very high,” “average” or “low to very low.” Scores for each component are then used to calculate a seasonally adjusted index where any number over 50 indicates that more builders view conditions as good than poor.

All three of the major HMI indices posted losses in February. The HMI index gauging current sales conditions fell four points to 46, the component measuring sales expectations in the next six months plunged 13 points to 46, and the gauge charting traffic of prospective buyers posted a three-point decline to 29.

Looking at the three-month moving averages for regional HMI scores, the Northeast fell three points in February to 57, the Midwest moved two points lower to 45, the West edged one-point lower to 39 and the South held steady at 46. The HMI tables can be found at nahb.org/hmi.

Discover more from Eye On Housing

Subscribe to get the latest posts sent to your email.


This article was originally published by a eyeonhousing.org . Read the Original article here. .

Pin It