Tag

Weak

Browsing


Economic uncertainty and persistent affordability challenges driven by rising material prices, high land costs, and elevated mortgage rates continue to weigh on builder sentiment.

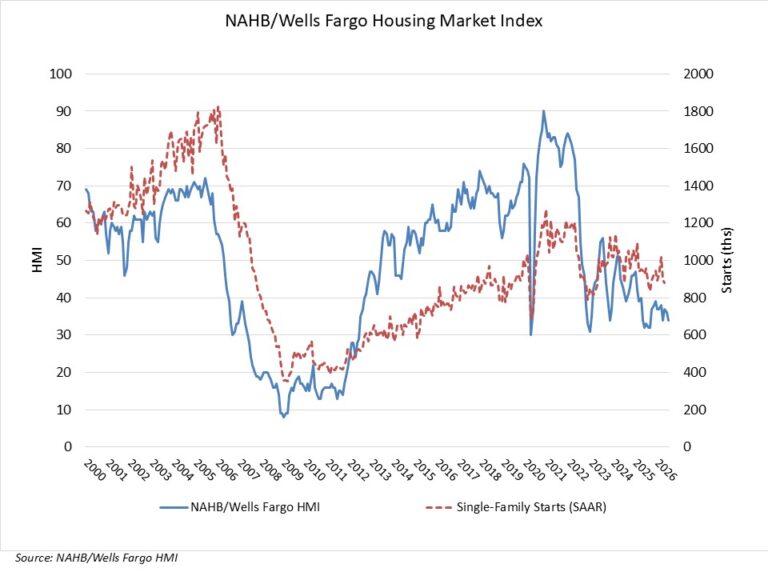
Builder confidence in the market for newly built single-family homes fell two points to 34 in July, down from an upwardly revised reading of 36 in June, according to the National Association of Home Builders (NAHB)/Wells Fargo Housing Market Index (HMI). Sentiment has remained below 40 for 15 consecutive months, the longest such stretch since 2012.

With the HMI below 40 for 15 straight months, affordability remains the home building industry’s primary challenge, as elevated mortgage rates, costly land, rising material prices, and persistent skilled labor shortages continue to affect the market. Looking ahead, the newly enacted 21st Century ROAD to Housing Act is a positive step that will help expand housing supply and lower overall housing costs, although more policy change is needed at the state and local level.

The latest HMI survey also revealed that 37% of builders cut prices in July, up from 35% in June and 32% in May. The average price reduction was 6% in July, the same rate as the previous month. The use of sales incentives was 63% in July, up slightly from 62% in June, and marking the 16th consecutive month this share has reached 60% or higher.

Derived from a monthly survey that NAHB has been conducting for more than 40 years, the NAHB/Wells Fargo HMI gauges builder perceptions of current single-family home sales and sales expectations for the next six months as “good,” “fair” or “poor.” The survey also asks builders to rate traffic of prospective buyers as “high to very high,” “average” or “low to very low.” Scores for each component are then used to calculate a seasonally adjusted index where any number over 50 indicates that more builders view conditions as good than poor.

All of the HMI sub-indices posted declines in July. The HMI index gauging current sales conditions fell one point to 37, the index measuring future sales dropped two points to 43 and the index charting traffic of prospective buyers posted a two-point decline to 23.

Looking at the three-month moving averages for regional HMI scores, the Northeast rose one point to 45, the Midwest increased two points to 45, the South fell one point to 33 and the West dropped one point to 26. The HMI tables can be found at nahb.org/hmi.


This article was originally published by a eyeonhousing.org . Read the Original article here. .

Builder sentiment remains subdued as rising material costs, elevated mortgage rates and ongoing affordability challenges continue to strain the housing market.

Builder confidence in the market for newly built single-family homes fell two points to 35 in June, according to the National Association of Home Builders (NAHB)/Wells Fargo Housing Market Index (HMI). This is the 14th straight month that sentiment has remained below 40, a streak not seen since 2011-2012 during the foreclosure crisis.

Costly and inefficient regulatory policy is clearly impeding the ability of builders to increase the housing supply. According to a new NAHB study, government regulation, taxes, fees and other costs add more than 26% to the price of an average single-family home. Easing permitting bottlenecks, density limits and inefficient zoning rules would help reduce costs and support the housing growth the nation needs.

The latest HMI survey also revealed that 35% of builders cut prices in June, up from 32% in May. The average price reduction was 6% in June, the same rate as the previous month. The use of sales incentives was 62% in June, up slightly from 61% in May, and marking the 15th consecutive month this share has reached 60% or higher.

Derived from a monthly survey that NAHB has been conducting for more than 40 years, the NAHB/Wells Fargo HMI gauges builder perceptions of current single-family home sales and sales expectations for the next six months as “good,” “fair” or “poor.” The survey also asks builders to rate traffic of prospective buyers as “high to very high,” “average” or “low to very low.” Scores for each component are then used to calculate a seasonally adjusted index where any number over 50 indicates that more builders view conditions as good than poor.

The HMI index gauging current sales conditions fell two points to 38 in June, the index measuring future sales held steady at 45 and the index charting traffic of prospective buyers remained unchanged at 25.

Looking at the three-month moving averages for regional HMI scores, the Northeast rose two points to 44, the Midwest held constant at 43, the South fell two points to 33 and the West dropped one point to 27. The HMI tables can be found at nahb.org/hmi.

Discover more from Eye On Housing

Subscribe to get the latest posts sent to your email.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


Even though garden/low-rise continues to be strong, overall confidence in the market for new multifamily housing decreased year-over-year in the fourth quarter, according to the Multifamily Market Survey (MMS) released today by the National Association of Home Builders (NAHB). The MMS produces two separate indices. The Multifamily Production Index (MPI) had a reading of 45, down three points year-over-year, while the Multifamily Occupancy Index (MOI) had a reading of 74, down seven point year-over-year.

Multifamily developers are somewhat less optimistic than they were at this time last year, except in the market segment for garden/low-rise apartments. This suggests that the 2025 trend of gains in multifamily market share for outlying metro and non-metro counties—where garden and low-rise structures are more common—is likely to continue in 2026.

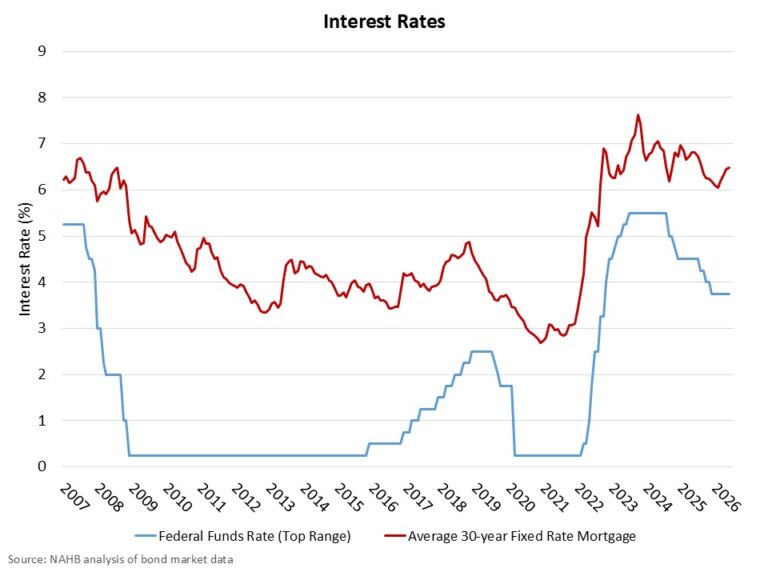
Elevated construction costs and the local regulatory environment continue to be major headwinds to faster growth. While interest rates eased slightly in 2025, they still need to come down further to significantly spur new construction.

Multifamily Production Index (MPI)

The MMS asks multifamily developers to rate the current conditions as “good”, “fair”, or “poor” for multifamily starts in markets where they are active.  The index and all its components are scaled so that a number above 50 indicates that more respondents report conditions as good rather than poor. The MPI is a weighted average of four key market segments: three in the built-for-rent market (garden/low-rise, mid/high-rise, and subsidized) and the built-for-sale (or condominium) market.

The component measuring garden/low-rise was the only one to experience an increase year-over-year in the fourth quarter of 2025, rising two points to 54. This component has been above 50 every quarter in 2025. The other three components experienced year-over-year declines during the quarter. The component measuring mid/high-rise fell eight points to 31, the component measuring built-for-sale units dropped six points to 36, and the component measuring subsidized units decreased five points to 47.

Multifamily Occupancy Index (MOI)

The survey also asks multifamily property owners to rate the current conditions for occupancy of existing rental apartments in markets where they are active as “good”, “fair”, or “poor”.  Like the MPI, the MOI and all its components are scaled so that a number above 50 indicates more respondents report that occupancy is good than poor.  The MOI is a weighted average of three built-for-rent market segments (garden/low-rise, mid/high-rise, and subsidized). 

All three MOI components experienced year-over-year decreases in the fourth quarter of 2025; the mid/high-rise component plummeted 12 points to 62, the garden/low-rise component decreased five points to 76, and the subsidized component dipped three points to 88. Nevertheless, all three MOI components remain well above the break-even point of 50.

The MMS was re-designed in 2023 to produce results that are easier to interpret and consistent with the proven format of other NAHB industry sentiment surveys. Until there is enough data to seasonally adjust the series, changes in the MMS indices should only be evaluated on a year-over-year basis.

Please visit NAHB’s MMS web page for the full report.


This article was originally published by a eyeonhousing.org . Read the Original article here. .

High interest rates for construction and development loans as well as ongoing challenges regarding labor shortages and higher prices for many building materials continued to slow the building market this summer.

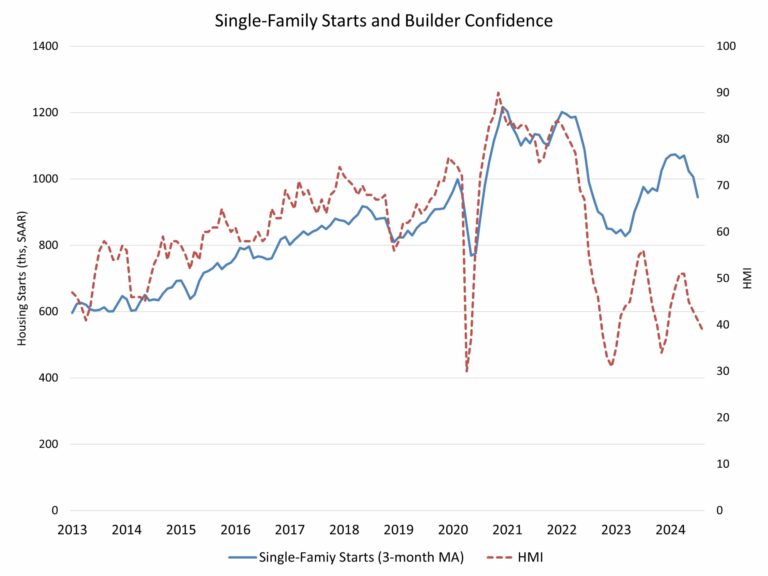
Overall housing starts decreased 6.8% in July to a seasonally adjusted annual rate of 1.24 million units, according to a report from the U.S. Department of Housing and Urban Development and the U.S. Census Bureau. This is the lowest pace since May 2020.

The July reading of 1.24 million starts is the number of housing units builders would begin if development kept this pace for the next 12 months. Within this overall number, single-family starts decreased 14.1% from an upwardly revised June figure to an 851,000 seasonally adjusted annual rate. However, on a year-to-date basis, single-family starts are up 11.4%.

The multifamily sector, which includes apartment buildings and condos, increased 14.5% to an annualized 387,000 pace.

The decline in new home construction mirrors our latest builder surveys (the NAHB/Wells Fargo HMI), which show that buyers remain concerned about challenging affordability conditions and builders are grappling with elevated rates for builder loans, a shortage of workers and lots, and supply chain concerns for some building materials.

Better inflation data points to the Federal Reserve moving to cut interest rates possibly as early as September, and with interest rates expected to moderate in the months ahead, this will help both buyers and builders who are dealing with tight lending conditions.

On a regional and year-to-date basis, combined single-family and multifamily starts are 1.3% lower in the Northeast, 5.1% lower in the Midwest, 5.4% lower in the South and 5.1% lower in the West.

Overall permits decreased 4.0% to a 1.40 million unit annualized rate in July. Single-family permits decreased 0.1% to a 938,000 unit rate. Multifamily permits decreased 11.1% to an annualized 458,000 pace.

Looking at regional data on a year-to-date basis, permits are 1.1% higher in the Northeast, 3.2% higher in the Midwest, 0.3% lower in the South and 4.1% lower in the West.

Single-family homes under construction fell back to a count of 653,000—down 4.1% compared to a year ago. The number of multifamily units under construction fell to an 886,000 count—down 13.2% compared to a year ago. The number of multifamily units under construction is now the lowest since July 2022.

Discover more from Eye On Housing

Subscribe to get the latest posts sent to your email.


This article was originally published by a eyeonhousing.org . Read the Original article here. .
Pin It