Tag

Real

Browsing


CHICAGO (WLS) — Things are about to change when it comes to buying and selling a home.

ABC7 Chicago is now streaming 24/7. Click here to watch

Starting Saturday, August 17, 2024, new rules will take effect regarding real estate commissions.

The change comes as part of a settlement of class action lawsuits filed by homeowners against the National Association of Realtors.

Those lawsuits claimed homeowners were forced to pay inflated commissions to sell their homes.

The National Association of Realtors has denied any wrongdoing.

“As a result of the NAR settlement, buyers are going to be asked to sign a representation agreement with the brokerage where their agent works,” real estate Lawyer Heather Neveu with Chilton Yambert Porter LLP said. “It’s going to be an agreement where the buyer is agreeing to compensate the realtor for the work they’re performing.

New rules will take effect regarding real estate commissions, after a settlement was reached against the National Association of Realtors.

Co-Founder of Weinberg Choi Residential Tommy Choi said this type of agreement is not new.

“It’s something that’s always been around, a buyer-broker agreement,” Choi said. “It’s something most real estate agents have practice. Now, it’s just something that’s going to become even more clear. And part of the process when it comes to homebuying.”

New rules will take effect regarding real estate commissions, after a settlement was reached against the National Association of Realtors.

“I think it’s going to be a short-term thing because I don’t think it was wisely used,” Neveu said. “I think there might just be a learning curve involved as buyers are going to be now across the board shown this agreement. The responsibility for paying their realtor is now going to shift to the buyer where before an agent representing a buyer was able to honestly tell their client you don’t have to pay me.”

She added that buyers are now going to have to learn about their options concerning how realtors are paid.

Another change is the offers of compensation, which can no longer take place on the MLS.

Choi explained there’s been a lot of misinformation about these changes.

“The biggest thing is that consumers think commissions go away. Sellers don’t have to pay the buyers. They never really had to. It’s in their best interest because if they don’t it limits the buyer pool. And the biggest challenge this could pose in that situation, is affordability for a buyer,” Choi said.

Copyright © 2024 WLS-TV. All Rights Reserved.


This article was originally published by a abc7chicago.com . Read the Original article here. .


HOUSTON – A massive settlement that changes the way homes are bought and sold goes into effect August 17. In the spring, the National Association of Realtors agreed to a $418 million settlement and rule changes to answer a class-action suit alleging a fee conspiracy to inflate broker commissions. 

The settlement is supposed to make home buying more transparent, but adds another complication to an already-tight housing market.

SUGGESTED: Here’s where you can get the most (and least) apartment space for $1,500 a month

Houston real estate agent Tricia Turner says tight inventory, high prices, and inflated interest rates are already making home sales a tough-sell for many, “50% of all real estate agents have not sold a single home this year. Not one single home. So, they are already struggling.”

The Houston Association of Realtors reports June sales were down more than 11%, over a year ago. Now, the new settlement rules will add work and costs to would-be buyers.

Before the agreement, when a house went on the market, the seller typically paid the cost of all of the agents involved. It was usually about 6%; 3% for each side, and that information was stipulated on the listing. Specifically, it stipulated how much the buyers agent would receive for finding someone to buy the home. 

That’s what’s changing. 

Now, if you want to buy a home, you’ll have to find your own agent or broker, negotiate how much money they will earn, and sign an agreement every time you come to look at a house.

FOX 26 Houston is now on the FOX LOCAL app available through Apple TV, Amazon FireTV, Roku, Google Android TV, Samsung TV, and Vizio!

It will all mean a lot of extra work just to view a potential purchase, as brokers will have to justify what they earn for what they do. All of it is designed to give buyers and sellers flexibility over what they pay. 

“If you’re a buyers agent, you’re going to want something rather than nothing, so you’re going to have to make the deal work,” says Turner. “(But) those buyers agreements can be amended.  So, just because a buyers agent says, ‘I want you to pay me 2%,’ and the buyer agrees, those can be amended and changed.”

The net-effect is that sellers will generally make a little more money on the sale of their home. Buyers, meantime, will often have to pay for a professional service that was previously rolled-into the deal. Consequently, they’ll want to find someone who knows what they’re doing. That’s where research and recommendations will be vital.


This article was originally published by a www.fox26houston.com . Read the Original article here. .


As a result of the March 2024 agreement by the National Association of Realtors to settle one of several class action lawsuits brought against them and a variety of large national real estate firms and Multiple Listing Services, things in real estate are about to change in a big way. August 17, 2024 is the deadline for certain practice changes to begin in the real estate industry across the country.

Some of those changes include a prohibition of any offers of compensation (by a selling firm to a buyer’s agent’s firm) from being displayed on any MLS listing as happens now, and more specific disclosures regarding agent representation and real estate commissions. Such as, clear reminders to consumers that commissions charged by brokers for selling your property or acting as a buyer’s agent are not set by law and are fully negotiable.

For several years, Maine Realtors have been required to present to everyone they have a substantive interaction with about buying or selling real estate, a written explanation of the types of agent representation available. This common disclosure details the difference between remaining an unrepresented “customer” and becoming a represented client. Still, there is much confusion about the process. 

In Maine, we have used written Buyers Representations Agreements for many years, but states elsewhere are only beginning to. And, while in Maine it has always been that an interested party could view a listed home with an agent without ever signing anything, after Aug. 17, 2024, that can no longer happen (in all but limited scenarios). All real estate agents will be prohibited from showing you a listed property without a signed written agreement between you and the agent detailing the terms of representation and potential compensation (you can limit that agreement to just one property, and for just that day, if you choose). To be sure, there are many great reasons to have a trusted Realtor by your side guiding you and representing your interests when buying or selling real estate. That will not change, and in fact, it will be more important than ever after Aug 17.  

There is an expectation that these practice changes will enhance transparency going forward, and maybe even lower the cost of selling real estate for consumers. At Newcastle Realty, our old model called for standard listing commission tiers of some percentage of the sold price; it might have been 5%, 6%, 7%, or 8%, depending on whether we were marketing land, a home, a business, or commercial property for the client. Of that, we used to offer a portion to agents representing buyers, as an additional incentive (that used to be 50% of what we were charging our seller client). Now, we offer a modified option where our listing and marketing services cost half what they used to, and the seller decides how much (if any) additional compensation they wish to offer to a buyer’s agent, and we add those together. The result is often lower than what we might have expected to see in the past. 

Yes, this can and will have the effect of transferring some or all the cost for the buyer’s agent services (that used to be paid by the seller), onto the buyer’s side of the settlement statement—and that is a potential disadvantage for first-time home buyers without extra funds beyond their downpayment. It will take time for us to see the full impact of this evolution.

To be sure, there is a lot of confusion among consumers, and frankly, there is a lot of concern among some Realtors. At my firm, we have accepted and embraced these changes. We are ready to guide buyers and sellers through this new, exciting landscape. This is the future of real estate, and it begins Aug. 17. There are some very good sources of additional information available online if you want to learn more, such as www.nar.realtor/the-facts/home-sellers-what-the-nar-settlement-means and www.nar.realtor/the-facts/homebuyers-what-the-nar-settlement-means. 


This article was originally published by a www.boothbayregister.com . Read the Original article here. .


The summer slowdown is slowly uncovering some interesting pricing opportunities across Manhattan. … [+] The data suggests now might be an opportune time to buy homes others paid significantly more for not too long ago.

getty

As the summer heat intensifies, the Manhattan real estate market is cooling down, and the languid season could present unexpected opportunities for savvy buyers. An emerging trend shows an increasing number of properties being listed at prices lower than their previous sale prices. This phenomenon offers a chance to secure homes with potentially less downside risk and more upside potential should the market’s nascent pricing recovery continue.

Pricing Opportunities

Recent Manhattan data indicates a significant upward trend in the percentage of new listings priced below their previous sale prices. This trend has accelerated in 2024, reaching 9.5% by the third quarter. Historically, this is a marked increase from just 1.7% back in Q1 2014. This data underscores a growing opportunity for buyers as the market adjusts and consolidates from its previous highs.

Percentage of Quarterly New Listings in Manhattan Priced Below Previous Sale Price (2014-2024)

UrbanDigs

Condos and Co-ops by Neighborhood
#1: Condos

The trend of condo listings below previous sale prices varies across Manhattan neighborhoods. Downtown, Midtown, the Upper East Side, the Upper West Side, and Upper Manhattan all show significant increases, with the Upper East Side peaking at 31.6% in July 2023.

Percentage of Condo Listings Below Previous Sale Price by Neighborhood (2014-2024)

UrbanDigs

#2: Co-ops

The more stable co-op market mirrors this trend, albeit at lower levels, with notable increases across all neighborhoods. Midtown and Downtown have seen substantial jumps, reaching 18.7% and 21.0% respectively by Q2 2024.

Percentage of Co-op Listings Below Previous Sale Price by Neighborhood (2014-2024)

UrbanDigs
Year of Previous Sale

Analyzing the data further, we see a pattern where the majority of listings now priced below their previous sale were originally purchased during market peaks. The period of 2014 to 2018, which saw a frenzied rally peaking in the years 2016 and 2017, represents the bulk of units, with nearly 600 homes listed for sale this year seeking to sell at a loss.

Number of Listings in 2024 Priced Below Their Previous Sale Price by Year of Previous Sale

UrbanDigs

Brooklyn Value Creation

While Manhattan has seen a notable increase in the percentage of new listings priced below their previous sale prices, Brooklyn tells a different story. The percentage in Brooklyn remains significantly lower, speaking to the incredible value creation in the borough over the last decade as prices have steadily risen in response to incessant demand. Despite market peaks and troughs, over the last decade, buyers in Brooklyn have done exceedingly well and may continue to do so even if prices remain stable, hence the level of units selling at a loss in Brooklyn remains far lower than that of Manhattan.

Percentage of New Listings in Brooklyn Priced Below Previous Sale Price (2014-2024)

UrbanDigs
Risk Padding

When markets are hot, buy-side competition is at its most intense, supply is scarce, and asking prices tend to rise quickly, reflecting a seller’s market premium over and above the fair market price that buyers have to pay if they want a deal. However, as markets slow, that premium is the first to evaporate. Slower markets, like the one we are experiencing today, offer buyers a chance to buy without having to embed a premium in their price due to intense buy-side competition, offering a kind of risk padding as there is likely to be less price volatility in the near future due to a downshift in market sentiment. This risk padding means that buyers who enter the market now could see more stable property values over time, reducing the chances of sharp price drops that were more common following the market peaks of the past.

Current Manhattan Market

A look at what’s currently on offer shows a handful of opportunities for buyers. Out of nearly 6,800 active listings, 537 are priced lower than their previous sale prices, reflecting an average loss of 12% compared to the previous sale price. In particular, homes sold in 2017 and 2018 make up the largest segments of such listings, with 81 and 45 units on the market, respectively. For those hunting for bargains, the data implies that focusing on properties bought between 2015 and 2018, particularly in areas with higher inventory, might yield the best opportunities for finding a new home at a reduced price relative to what it once traded at and could potentially trade at again.

Conclusion

In conclusion, the summer slowdown is slowly uncovering some interesting pricing opportunities across Manhattan. Whether you’re eyeing a condo or a co-op, the data suggests now might be an opportune time to buy homes others paid significantly more for not too long ago.

Moreover, today’s market slowdown may offer an additional layer of security for Manhattan buyers. With less frothiness and reduced competition, there is likely to be less price volatility in the future, providing a cushion against market fluctuations. Meanwhile, Brooklyn’s relatively low percentage of new listings priced below their previous sale prices showcases the borough’s unrelenting demand and highlights its strength.

Ultimately, current market conditions may provide a unique opportunity for some buyers to secure properties at attractive prices, with reduced risk and potential for future value appreciation.


This article was originally published by a www.forbes.com . Read the Original article here. .


This is Part 1 of Federal News Network’s special report looking at agency efforts to shrink the federal real estate footprint.  Click here for Part 2. 

A six-year experiment meant to help the federal government quickly sell or dispose of its underutilized real estate is running out of time.

Congress created the Public Buildings Reform Board as a small, independent agency under the 2016 Federal Assets Sale and Transfer Act (FASTA), to help the federal government’s landlord, the General Services Administration, identify federal buildings and properties that agencies no longer need, and to sell or repurpose them.

In fiscal 2022, the 24 largest federal agencies owned nearly a quarter million buildings, covering more than 2.4 billion square feet, according to the latest GSA data. That portfolio of owned buildings accounts for more than $16 billion in annual costs.

The federal footprint of owned buildings has steadily decreased over the past decade. But the Government Accountability Office says agencies holding onto excess and underutilized office space is one of the main reasons it’s kept federal real property management on its High-Risk List since 2003.

The PBRB got started in 2019. In those early days, its backers compared the scope of the board’s work to the controversial Base Realignment and Closure (BRAC) that shook up the Defense Department’s footprint of military bases across the country.

Members of the board, so far, have given the Office of Management and Budget two rounds of recommendations. Along the way, OMB blocked the board-recommended sale of a National Archives and Records Administration facility in Seattle, after tribal governments sued the Biden administration over the site’s disposal.

The board also lost, and then regained a quorum in 2022.

Meanwhile, the COVID-19 pandemic created uncertainty over what space agencies still deemed underutilized. It also kicked off an ongoing conversation about the future workforce for federal employees, and changed expectations of how often a telework-adept workforce needs to be in the office.

Under the FASTA, the board will disband in May 2025. But current and former federal real estate experts say the board’s work has grown exponentially, and in unimaginable ways from when lawmakers first passed the legislation.

Those experts — while mixed on the PBRB’s results to date — say the federal government faces a once-in-a-generation opportunity to shed underutilized property, after the pandemic gave the federal workforce greater flexibility to telework. Now they’re pushing Congress to reauthorize the PBRB, and to expand its authorities to take on this work.

A ‘once-in-a-lifetime opportunity’

PBRB members, at their last public meeting last September, gave measured praise to their work to date, but also expressed frustration with the hurdles they’ve encountered to get this far, and the challenges that remain.

Among their challenges, board members say agencies aren’t forthcoming with providing data on underutilized or excess property, and that GSA’s real estate data, as captured in the Federal Real Property Profile, gives an incomplete picture of what space is actually underutilized.

“Just because it’s underutilized in the database doesn’t mean it’s ready for repurposing,” Paul Walden, the board’s executive director, said in an interview.

Meanwhile, OMB rejected a whole slate of recommendations from the PBRB in January 2022, on the grounds that it was “unable to conclude that the risks to the government posed by the disposition of the proposed properties are acceptable to the taxpayer.”

Members of the board, so far, have given OMB two rounds of recommendations. Its third, and final round of recommendations, is due December 2024.

Board member Talmage Hocker, founder of a private real estate firm in Lexington, Kentucky, said at the PBRB’s Sept. 28, 2023 meeting that that agency, since the COVID-19 pandemic,  faces an “extraordinary, once-in-a-lifetime opportunity for the federal government to right-size its portfolio.”

Hocker added that, “given the low occupancy of federal property, stronger leadership is needed from OMB and GSA” to accelerate the pace of consolidation efforts.

“We have some buildings that are 10% utilized — that means 90% empty — and we can’t get people to work with us to consolidate these buildings,” he said.

The benefit of doing so, he added, will be reduced costs, better offices for federal employees and reduced utility costs across the federal government.

As of September 2023, GSA has sold 10 of 12 properties from its “high-value asset” round of recommendations, and received $194 million in proceeds. But members of the board say there are plenty more opportunities to sell excess federal real estate.

Board member David Winstead, a former commissioner of GSA’s Public Buildings Service, estimated about a 40% vacancy rate of office buildings in D.C.

“We really continue to try to seek ways in which to incentivize agencies to consider more rapid consolidation, working with GSA … and trying to create incentives to do that,” Winstead said.

Former Rep. Michael Capuano (D-Mass.), another member of the board, said it’s clear that agencies have more office than they need. He cited GSA’s own downtown D.C. headquarters as a prime example of underutilized office space.

Data from GAO shows GSA’s headquarters had an 11% utilization rate in early 2023.

“You could throw a bowling ball down the hall, and not a single person will be hit. This is not because they’re screwing off. It’s because they’re home working, in the field working. There are no people to populate the space,” Capuano said. “Those people are doing their job, they just aren’t doing it from a desk like they usually do. I don’t know if that’s going to change, but I do know it’s an incredible, immense, massive waste of taxpayer dollars, a waste of opportunity.”

While PBRB members see plenty of opportunities to right-size federal real property, members of the board fear the federal government, as a whole, isn’t moving fast enough to seize on this window of opportunity.

The $194 million in the proceeds from the high-value asset round, so far, fall far short of the board’s sales target of $500-$700 million, according to a 2021 GAO report.

PBRB expected its following round of recommendations in December 2021, once sold by GSA, would bring in about $2.5 billion in total proceeds, but OMB rejected the board’s list in its entirety.

“We have a unique opportunity to reduce the footprint of the federal government,” said board member Jeff Gural, a New York real estate developer. “We’re going to look like fools if we don’t.”

Pandemic ‘added momentum’ to right-size real estate footprint

With the Biden administration focused on bringing more federal employees back to the office, it remains unclear if PBRB missed its window to offload underutilized office space, or how close the board will reach its financial targets before it sunsets in May 2025.

Walden said in an interview that efforts to shrink the federal real estate footprint have been in the works for more than a decade, and that a hybrid federal workforce increases opportunities to reduce office space.

Under the Obama administration, the OMB in 2013 issued a “Freeze the Footprint” initiative aimed at reducing a year-over-year increase in agency-leased and owned office space. Subsequent administrations have built on those plans, and focused on shrinking federal office space.

“COVID just added momentum to that,” Walden said. “Agencies are still looking at downsizing [and] consolidating; this has just added fuel to the fire. But as far as definite plans, it’s too early to say, because there’s sensitivity when you talk about moving an employee’s work location. I don’t think the agencies are at the point where they can really discuss that too much openly.

Federal agencies see less need for office space — but private-sector businesses are also shedding offices.

Former Rep. Nick Rahall (D-W.V.), another PBRB member, said large corporations are downsizing their office space at a historic pace, “as it becomes clear that the workforce will not return to a five-day-a-week office routine.”

Rahall said that agency reluctance to sell underutilized space, plus a “lack of preparedness to seize the opportunities of this moment and lack of leadership on the part of OMB and GSA … are resulting in a sluggish response simply not felt in a commercial real estate market.”

“It’s obvious to the board that the federal government is not meeting the moment as efficiently as it should, or as it could,” Rahall said.

Renewed focus

Despite the board’s challenges, agencies and Congress have renewed their focus on right-sizing federal real estate.

GSA announced last November that it’s putting 23 additional properties through its disposal process.

That’s a much higher volume of properties than what the agency put through this process last fiscal year, and sets a higher bar for what GSA expects to offload in the coming years. Next steps include selling, transferring or exchanging them to another federal agency, or state or local government or to the public.

The same day as GSA’s announcement, members of the House Transportation and Infrastructure Committee introduced a slew of bills focused on agencies selling or making better use of its underutilized office space.

One of the bills, the FASTA Reform Act, would extend the termination date of the PBRB to Dec. 31, 2026, and would give the board additional authority.

“The process has not worked as originally envisioned,” Rep. Scott Perry (R-Pa.), chairman of the committee’s panel that oversees public buildings, said last November during a markup of his bill.

A few days later, OMB Deputy Director Nani Coloretti pushed for a renewed focus on right-sizing the federal real estate portfolio at a meeting of the Federal Real Property Association.

“Within two days, you got the three key players — Congress, OMB and GSA — all saying disposal is important and they want to create more authorities to do it,” former PBS Commissioner Dan Mathews, who was appointed a member of the PBRB in February, said in an interview. “I’m optimistic —  they’re going to get more authority. GSA is going to get more involved. OMB seems to be focused on it.”

Lawmakers took action yet again this week. Sens. Kevin Cramer (R-N.D.) and Mark Kelly (D-Ariz.) introduced similar legislation on Wednesday. Their bill would also extend PBRB’s end date to December 2026.

Keeping unneeded federal buildings open for no reason is costing American taxpayers hundreds of millions of dollars each year. It’s ridiculous and must be fixed,” Cramer said in a statement.

The Congressional Research Service, in a November 2022 report, found federal agencies owned 7,697 vacant buildings and 2,265 partially vacant buildings.

“Abandoned and unused federal buildings are an eyesore for communities, yet too often, bureaucratic red tape makes it difficult for federal agencies to sell these buildings—even when a community could find a better use for them,” Kelly said.

‘High-value’ properties are selling

Flavio Peres, GSA’s assistant commissioner of real property disposition, said the agency received $194 million for selling 10 of 12 properties on the board’s high-value asset list of recommendations. The proceeds of those sales, he added, are 10% higher than GSA’s internal appraisals for the properties.

“Obviously, COVID had a big impact on real estate markets,” Peres said at the PBRB’s September meeting.

The properties, previously owned by seven different agencies, account for about 4 million square feet of federal building space. The board recommended the sale of these buildings as part of its “High-Value Asset” round  — one of three rounds of recommendations required under FASTA.

These GSA-sold properties include Pacific Point in Auburn, Washington, which previously served as the Social Security Administration’s main processing center on the West Coast.

The 1.5 million square foot property covers 11 buildings. But Peres said some of the warehouses on the site were in “unoccupiable” condition, and required significant investment to rehabilitate.

“That really showed the benefits of FASTA and PBRB, where we had funds to move these agencies, in order to make the project viable,” Peres said.

GSA also sold a former National Oceanic and Atmospheric Administration facility in Pacific Grove, California. Peres said GSA and PBRB worked with tribal governments, as well as members of Congress, looking to preserve a mural on the former NOAA building.

Two federal properties from PBRB’s “high-value” list remain on the market.

GSA is still trying to sell the Laguna Nigel Federal Building in Orange County, California. Peres said the agency set a minimum bid of $70 million for the 92-acre property, but “we did not get anybody to jump in at that value.”

GSA is still trying to sell the Laguna Nigel Federal Building in Orange County, California. The building is unique among federal buildings with its ziggurat-style architecture (Source: GSA)

GSA is also still trying to sell a Coast Guard facility in Menlo Park, California. Peres said the Coast Guard planned to move personnel to the nearby Moffett Federal Airfield, but that the planned move was delayed because of the pandemic.

Peres said the site requires decommissioning, including environmental cleanup, but added that GSA expects to sell the property in early 2025.

“Their move got delayed, and those delays did cause a ripple effect on the timing of this sale. Because the move got delayed, the decommissioning got delayed,” Peres said.

Copyright
© 2024 Federal News Network. All rights reserved. This website is not intended for users located within the European Economic Area.

This article was originally published by a federalnewsnetwork.com . Read the Original article here. .


Homeowners who decline to use a real estate agent to sell their property are twice as likely to say they weren’t satisfied with the selling experience, according to a new survey from Clever Real Estate of 1,000 home sellers in 2022 and 2023. Survey respondents say they realize they likely made less money on their home sale and faced more stress by not having a professional representative.

Those who didn’t use a real estate agent said before their transaction that they think pros are overpaid for what they do and are not more knowledgeable about the homeselling process than the average seller. However, when these respondents reflected on their experience after the transaction, they admitted that they made some mistakes without the help of a pro.

More than a third of non-agent sellers, such as FSBOs or those selling to an iBuyer, said the process was more difficult than they expected. What’s more, these sellers admitted:

Buyers distrusted them because they didn’t have an agent (43%).
They struggled to understand their contract (40%).
They made legal mistakes because they didn’t use an agent (36%).

The survey also found other consequences of going it alone as a seller:

Lower sales price: Homeowners who sold without a real estate agent are three times more likely to say they lost money on their home sale. The Clever Real Estate survey found that those who sold their home with an agent tended to earn $46,603 more in average profits than those who sold without an agent in 2022 and 2023. About half of unrepresented sellers say they wish they had priced their home differently, and nearly half now believe their home would have sold for more if they would have used an agent.
Longer selling process: Home sellers without an agent are nearly twice as likely to say they didn’t accept an offer for at least three months; 53% of sellers who used an agent say they accepted an offer within a month of listing their home. Ironically, many homeowners who didn’t use an agent said the primary reason for going it alone was to sell faster.
More stress: Half of home sellers who did not use an agent admit to crying at some point in the process. Fifty-two percent of unrepresented home sellers said they felt overwhelmed by the entire sales process. On the flip side, homeowners who hired an agent were more likely to say they felt good about their sale and expressed less stress.

To be fair, home sellers who used an agent also had some gripes about their experience, albeit much fewer. But those who were unhappy with their agent experience expressed feelings like their agent was only looking to make a sale and didn’t care about their interests, their agent “annoyed” them, or they thought the agent pressured them into decisions, the survey found. That said, 77% of respondents who used an agent say they were satisfied, and 72% say they would use their agent again.

Even as the vast majority of home searches start online, most consumers still use real estate agents to buy or sell a home. Indeed, the National Association of REALTORS®’ 2023 Profile of Home Buyers and Sellers found that 89% of buyers and sellers in the last year used a real estate agent, up from the previous year.

Only 7% of homeowners sold as a FSBO over the last year—which matches the all-time low recorded in 2021, according to NAR data. FSBOs continue to not fare as well in the market as professionally represented homes: FSBOs sold at a median price of $310,000 in the last year, compared to $405,000 for listed homes, NAR’s data shows.

“Having a REALTOR® help you navigate the homebuying and selling process provides peace of mind, especially in a challenging market with high prices, elevated mortgage rates and limited inventory,” says NAR President Tracy Kasper.


This article was originally published by a www.nar.realtor . Read the Original article here. .


Tiago Ribeiro paced the lobby of the Four Points by Sheraton hotel in Tampa on Saturday night searching for a miracle. He had 24 hours to find someone who could lend him $30,000 to buy a foreclosed property in Fort Myers.

“Ask me about a 35% APY (investment) opportunity,” read the laminated sign hanging from his neck.

Tiago Ribeiro wears a sign enticing attendees to an investment opportunity at the Real Estate Raw seminar hosted by Ben Mallah on Feb. 24 in Tampa. [ LUIS SANTANA | Times ]

Ribeiro and 160 others paid $250 a pop to attend an event put on by Tampa Bay real estate mogul and YouTube personality Ben Mallah.

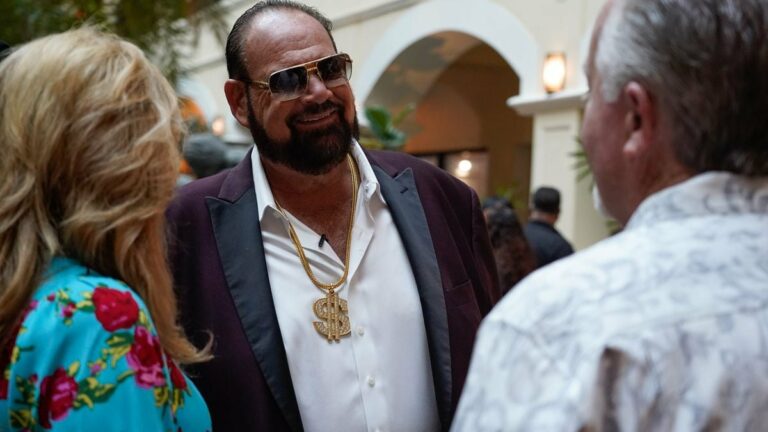
A high school dropout, Mallah got his start buying dilapidated apartments, fixing them up and renting them through Section 8 and other federal government programs. Now he lives in a $16.5 million gulf-front mansion, drives a Rolls-Royce (or a Bentley, depending on the day) and wears a thick gold chain with a blingy medallion in the shape of a dollar sign.

“You can do it,” Mallah preached to the crowd from behind his signature aviator sunglasses. “I know it, I’ve seen it, I’ve done it.”

Since the start of the COVID-19 pandemic, droves of wannabe real estate investors have flocked to Florida chasing the promise of streets paved with gold. But rising interest rates, home prices and insurance costs have created hurdles for newcomers looking to get rich quick.

“It’s a very tough market right now,” Mallah told the Tampa Bay Times. “It’s impossible to find a decent deal.”

Ben Mallah, left, speaks on stage with his sons during his Real Estate Raw seminar on Feb. 24 in Tampa. [ LUIS SANTANA | Times ]

Last year, Mallah sold off some of his assets, including an $8.7 million home in Belleair, a $28 million hotel in Fort Lauderdale and several shopping plazas.

He started holding events like this one to connect with fans and maybe help some people along the way.

There was no rehearsal beforehand. Mallah and his sons got up on stage and spoke to the crowd off the cuff. They pledged to stay as late as they needed to take make sure everyone would get their chance to chat with them and snap a photo.

A group of dancers in colorful showgirl outfits came out to shake and shimmy for the crowd during a break.

The point is to have a good time, Mallah said. He’s not interested in selling his followers instructional courses or raising money for his real estate ventures, he said. That’s already a crowded space.

Catch up on top stories before rush hour

Become a Times subscriber to get our afternoon newsletter, The Rundown

We’ll break down Tampa Bay’s biggest environment, politics, business, education and culture news every weekday.

You’re all signed up!

Want more of our free, weekly newsletters in your inbox? Let’s get started.

Explore all your options

“It’s not a gimmick,” he said. “It’s not a seminar. It’s about meeting people, networking.”

This message has helped him gain a loyal following. On Saturday, there were fans that flew in from New York, Pennsylvania, Ohio and Michigan to see him.

Elizabeth Robles, 35, said she’s been watching Mallah’s videos and attending his events for a decade. He was the one who inspired her to move from Las Vegas to Clearwater and purchase her first condo.

“He’s very motivational,” she said. “He makes you want more from life.”

Even if, in this economy, that means working harder to get it.

Elizabeth Robles listens to Ben Mallah speak during his Real Estate Raw seminar on Feb. 24 in Tampa. [ LUIS SANTANA | Times ]

For Ribeiro, success came easy at first.

The Orlando native took advantage of historically low interest rates in 2021 and snagged his first home in Orange County for $200,000. He then bought his parents a home in Osceola County and moved in with them so he could rent out the first house.

He figured buying a third property would be a breeze. But it hasn’t panned out that way.

“Sellers have us in a chokehold right now,” he said. “There’s really nothing good available for a fair price.”

Adriana Crisanti, a bartender in St. Petersburg, attended Saturday’s event seeking guidance. During the height of the pandemic, her bar was flooded with real estate agents bragging about how much money they were making.

“I thought I could do the same,” said the 28-year-old.

Adriana Crisanti listens to Ben Mallah speak during his Real Estate Raw seminar on Feb. 24 in Tampa. [ LUIS SANTANA | Times ]

Crisanti got her real estate license seven months ago but still hasn’t sold her first home. It’s been discouraging, both for her and for her clients who have lived in the area for a long time.

“They’re not accustomed to the change that’s going on,” she said.

In January 2019, the median sale price across Tampa, St. Petersburg and Clearwater was $225,280. Now it’s $400,000, according to the most recent data from Greater Tampa Realtors.

While higher home values can lead to more profits, it also makes it harder to get started, said Casey Lawhorn, 31. After building a sizable portfolio of rental properties in his home state of Kentucky, he was inspired in part by Mallah to start doing business in the Tampa Bay area in 2020. He moved down last year.

Finding deals has been a challenge in an increasingly crowded market. Sometimes he feels like David battling Goliath, competing for the same homes as large investment firms.

“Back home you could offer under listing,” he said. “Here you could offer $80k over listing and still be outbid.”

Attendees to a Real Estate Raw seminar by Ben Mallah make their way to the ballroom on Feb. 24 in Tampa. [ LUIS SANTANA | Times ]

Mallah told the crowd it’s something he’s dealt with too — corporations coming in with cash offers that the average person could not afford. Sometimes you can beat the big guys by being more nimble — offering better terms and shorter time frames to close the deal. Other times, there’s nothing you can do.

That’s because making money in real estate often comes down to timing, Mallah said.

“Sometimes you’ve got to be patient and you’ve got to wait.”

Ribeiro, 25, wasn’t able to find an investor Saturday but he’s not giving up. Even if this property doesn’t pan out, he has faith the next one will.

He didn’t grow up rich. He has a day job as a consultant but 75% of his net worth comes from his real estate holdings, he said.

Though he’s faced more obstacles than he initially bargained for, real estate still feels like an industry where it’s possible to make something out of nothing.

“Anyone can get into it,” he said. “All you have to do is work hard and learn the market.”

Tiago Ribeiro listens during a Real Estate Raw seminar hosted by Ben Mallah on Feb. 24 in Tampa. [ LUIS SANTANA | Times ]


This article was originally published by a www.tampabay.com . Read the Original article here. .


“I want to buy a house soon, but I read that real estate commissions are going down. Should I wait until the new rules are in place?”

You’re right to step back and re-strategize your home purchase after the National Association of Realtors’ recent legal settlement. If it’s approved by the court, the real-estate industry is on the precipice of change that could impact the home buying process and what you pay for it. Whether it’s best to act now or to wait, though, will depend on your budget, how much work you want to put into the process and your need for certainty.

Here’s the gist of what’s happening: Lawsuits were filed against NAR, a trade group representing 1.5 million real-estate agents, questioning its cooperative-compensation rule. Under this rule, sellers cover the commissions for both their agent and the buyer’s, with the cut offered to buyer’s agents advertised in an agent-facing database known as a multiple listing service, or MLS. Critics say the practice reduces competition and inflates commissions and home prices.

In March, plaintiffs accepted a settlement proposed by NAR, which would remove offers of compensation from the MLS and require agents to sign contracts with buyers. The rules are expected to ultimately lower costs, however, buyers may need to pay agents out of pocket. If approved by the court, the changes are set to go into effect in August.

With this all in mind, there is no hard-and-fast answer as to whether you should buy now or wait until those changes roll around. There are, however, cases for both paths.

The case for buying now

If you want a full-service agent and assurance that the seller will foot the bill—then buying before July is probably best.

“The NAR settlement is creating lots of uncertainty, and if there’s anything people don’t like when making major life decisions and purchases, it’s that,” says Dana Bull, a real-estate agent and consultant in Massachusetts. “If you buy right now, you’ll have a greater sense of what to expect.”

By buying now, you’ll likely fall under the existing agent commission model where the seller pays. The total is usually 5% to 6% of the home price—with 2.5% to 3% going to each agent. In exchange for that cut, your agent will usually suggest listings, tour properties with you and negotiate on your behalf. Depending on what state you live in, they may also draw up contracts and attend your closing.

“The home buying journey will not be altered—at least for the next few months,” says Alyssa Brody, co-founder of Development Marketing Team, a real-estate brokerage with branches in New York City and Miami.

The case for waiting

If you’re comfortable negotiating and willing to handle some of the home-search process on your own, waiting to buy could pay off. “If you’re more focused on maximizing your investment and minimizing costs, waiting until the new rules come into play could be beneficial,” Brody says.

Starting in mid-August, buyers will sign a separate contract with their agent, opening the door for negotiation. Some agents may charge an hourly rate or offer a la carte services. This would allow buyers to choose which services they want to do themselves (browsing listings and touring homes, perhaps) and which they want to pay for (maybe negotiating and drawing up the contract).

Additional savings could come from lower home prices. With sellers no longer footing the bill for buyer agents, some experts believe they will sell their homes for less.

This all depends on market conditions, though, and agents broadly agree that prices are unlikely to drop much in the short-term. By summer, the Federal Reserve is expected to start cutting interest rates, which means lower mortgage rates and higher demand. “With our limited inventory, competition will be fierce,” says Bret Weinstein, founder of Guide Real Estate in Englewood, Colo.

If you choose to wait, be ready for a bumpy ride. “It will cause a shake-up, and no one knows exactly how the open market will react,” Bull says. “There will be lots of confusion, and as a buyer, you could be stuck in the crosshairs while the entire industry adjusts to the change.”

To sell or not to sell

The considerations are similar if you’re on the fence about selling. If you are comfortable with the existing model, sell now. For the lowest costs, you might want to wait until August.

Take note, though: Not everyone is convinced things will change once the new rules are in place. “I believe sellers will continue to pay buyer agents in big markets like Los Angeles, because it’s in their best interests,” says Michael Nourmand, president of real-estate firm Nourmand & Associates in Beverly Hills, Calif. “It’s best for buyer affordability, they don’t want to limit their buyer pool, and negotiating a commission is another variable that could derail the transaction.”

Talk to a few real-estate agents about the pros and cons of skipping the buyer-agent commission in your area. They can advise you on what it might mean for your sale, given current market conditions.


This article was originally published by a www.wsj.com . Read the Original article here. .


CHICAGO (August 1, 2024) – The National Association of Realtors® reminds members, real estate professionals, and consumers that on August 17, 2024 the practice changes following NAR’s Settlement Agreement that would resolve claims brought on behalf of home sellers related to broker commissions will be implemented across the country.

NAR recommends all MLSs implement practice changes by August 17. Realtor® MLSs (those owned exclusively by one or more Realtor® Associations) must implement the changes by this date to remain in compliance with NAR policy.

Under the settlement, the following practice changes will take effect:

Offers of compensation will be prohibited on Multiple Listing Services (MLSs). Offers of compensation will continue to be an option consumers can pursue off-MLS through negotiation and consultation with real estate professionals. Offers of compensation help make homeownership and the benefits of professional representation more accessible to buyers—especially first-time homebuyers—increase homeownership opportunities for historically underserved groups, and benefit sellers by expanding the potential buyer pool and ensuring they receive the best offer possible for their property.
Agents working with a buyer must enter into a written buyer agreement before touring a home. The practice changes do not require an agency agreement or dictate any type of relationship. NAR encourages all members to address form changes and prepare to educate real estate professionals and consumers about revised forms as soon as possible ahead of August 17. NAR policy does not dictate terms of buyer agreements, but NAR has created resources to assist with implementation of the settlement terms—such as tips on clarity and emphasizing consumer choice and a “Written Buyer Agreements 101” resource.

“NAR members are dedicated, intelligent, and highly adaptable experts in their fields—that’s why Realtors® are such an integral part of the homebuying and selling process,” said Kevin Sears, President of NAR. “These changes help to further empower consumers with clarity and choice when buying and selling a home. As the August 17 practice change implementation date approaches, I am confident in our members’ abilities to prepare for and embrace this evolution of our industry and help to guide consumers in the new landscape.”

Consumers can find additional information on what these changes mean for their homebuying and selling experiences in NAR’s buyers and sellers guides. For NAR members, the practice changes are outlined in detail here, and detailed information is available in NAR’s FAQ. Please visit facts.realtor for the latest updates on the settlement and practice changes.

About the National Association of Realtors®

The National Association of Realtors® is America’s largest trade association, representing 1.5 million members involved in all aspects of the residential and commercial real estate industries. The term Realtor® is a registered collective membership mark that identifies a real estate professional who is a member of the National Association of Realtors® and subscribes to its strict Code of Ethics.

# # #


This article was originally published by a www.nar.realtor . Read the Original article here. .


Photo: Drew Angerer/Getty

How much money is Rudy Giuliani worth? Ever since he filed for bankruptcy after a judge ruled last December that he owed two former Georgia election workers $148 million in damages as part of their defamation-suit victory, that has been the open question. (He claimed to have only $1 million to $10 million in assets and $153 million in debts.) Now we may never know. After months of spending tons of money while claiming he has no money, a judge dismissed his bankruptcy case, but Giuliani’s lawyers claimed he couldn’t even pay the fees he owed to his creditors’s financial adviser, a basic condition of closing the case. The latest chapter in this saga has concluded with the former mayor agreeing to a last-minute deal to pay off the $400,000 he owes to the adviser. He’ll have to pay $100,000 in cash up front and then pay the rest in profits from a sale of either his Upper East Side apartment or his Florida condo. (The judge still has to sign off on the agreement.)

The stately living room of Rudy Giuliani’s apartment featured in this listing photo is a great place to record a Cameo if you’re strapped for cash.
Photo: Sothebys

Which one will sell first? Giuliani listed his three-bedroom, three-bathroom Upper East Side apartment last year for $6.5 million with the price dropping to $5.7 million earlier this year. Locationwise, it’s just steps from Central Park, and its rooms, while dated, include a wood-paneled library and a grand dining room with a conservatory — all of it suitable for a mayor but perhaps too grandiose for a podcast host. So far, he hasn’t been forced to list the two-bedroom lakefront Palm Beach condo he plans to live in full time, but it’s estimated to be worth around $3.5 million. (Giuliani’s lawyer wrote in a motion in March, “Surely the committee does not intend the debtor to join the ranks of the homeless?”) The new deal allows Giuliani to avoid testifying under oath about his finances, but it doesn’t absolve him of the roughly $540,000 he owes the IRS in back taxes or the multiple legal debts he’s still on the hook for. With the bankruptcy case settled, the former election workers, Ruby Freeman and Shaye Moss, will now be able to move forward in the D.C. court system to seek the $148 million they are still owed. And Giuliani will have to hunker down in whatever multimillion-dollar property he has left and appeal — or figure out more ways (perhaps more profitable than coffee) to make up the rest of what he owes.

Related


This article was originally published by a www.curbed.com . Read the Original article here. .

Pin It