Tag

Reaches

Browsing


In 2025, the number of women employed in the construction industry rose to around 1.37 million, an increase of about 31,000 from 2024. Women accounted for 11.3% of total construction employment, the highest share in the past 20 years.  

The growing presence of women in construction aligns with the expansion of white-collar jobs in the industry. As the industry continues to face a persistent shortage of skilled labor, expanding the workforce remains one of the top priorities of the industry. Increasing the participation of women into the construction labor force represents a potential opportunity for future growth. This article uses labor force statistics from the Current Population Survey (CPS) to examine the role of women in construction employment and the occupations in which women are most highly represented.

The number of women working in construction has increased substantially since the Great Recession. As shown in the figure below, the number of women working in construction declined from more than 1.1 million in 2007 to roughly 807,000 in 2010, as the housing recession sharply reduced construction activity. Since then, women’s employment in construction has generally trended upward. From 2010 to 2017, the number gradually rose to around 970,000 but remained below the peak of pre-recession levels. The number surpassed 1 million again in 2018, reached 1.24 million in 2021, and continued rising to 1.37 million in 2025.

The share of women in construction workforce has also increased. After remaining around 9% after the Great Recession, the share began picking up noticeably in 2017. By 2025, women represented 11.3% of the construction workforce, marking the highest share over the 2004-2025 period.

Although women’s share in construction workforce has increased, their participation in construction varies widely by occupations. According to the CPS data, most women are employed in occupations such as office and administrative support, management, and and business and financial operations. Women accounted for 78% of office and administrative support occupations within the construction industry, the highest share among major construction occupational groups. Women also represented 40% of workers in service occupations (excluding protective services), and 35% of workers in protective service occupations. Women also made up 24% of construction workers in professional occupations, 19% in sales occupations, and 16% in management, business, and financial operations occupations.

By contrast, women remained much less common in construction and maintenance occupations, which account for the largest number of employees in construction and are where additional workers are most needed. Women comprised only 4% of workers in construction and extraction occupations, 3% in installation, maintenance, and repair occupations, and 6% in production occupations. Increasing women’s participation in these occupations could help expand the pool of skilled workers available to the construction industry.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


Multifamily units completed in 2024 recorded their highest level since 1986 at 608,000 units, according to NAHB analysis of the Census Bureau’s Survey of Construction. For the eighth consecutive year, most multifamily units were in buildings with 50 or more units (these will be labeled as high-density buildings).

As shown below, this trend is relatively new. Dating back to the earliest estimates in the series (1972), most multifamily units were historically located in buildings with less than 50 units (low-medium density buildings). Of the total 608,000 multifamily units completed in 2024, 330,000 (54%) were in high-density buildings while the remaining 278,000 (46%) were in low-medium density buildings.

Regional Distribution

The South continued to be the leading region in terms of units completed, rising from 212,000 in 2023 to 292,000 completions in 2024. The South accounted for 48% of the total number of completions; the West held 27% (163,000), the Midwest 14% (87,000), and the Northeast 11% (68,000). Singularly, the South was the only region where the number of units completed in low-medium density buildings outpaced the number in high-density buildings. The South had 147,000 completions in low-medium density compared to 145,000 units in high-density.

Conversely, in the Midwest and Northeast the number of units in high-density buildings nearly doubled those of low-medium density buildings. For the Midwest, there were 58,000 units in high-density buildings and 29,000 low-medium density units. The Northeast had 45,000 units in high-density buildings and 23,000 low-medium density units. The West featured an almost 50/50 split with 82,000 high-density units and 81,000 low-medium density.

Built-for-Rent

Among multifamily units completed in 2024, 95% were built-for-rent at a level of 580,000. Over half of these units (55%) were in a building with 50 units or more. This is a seismic shift towards high-density buildings, as this share was only 25% in 2004. Over the past twenty years, there has consistently been a falling share of units in buildings with 10-19 units, as the share in 2004 was 24%, while in 2024 this share only accounts for 4% of completed units.

Built-for-Sale

The number of multifamily units built-for-sale rose from 20,000 in 2023 to 29,000 in 2024. High-density buildings continued to be the primary type of building where these units were built, with 40% of built-for-sale units being completed in buildings with 50+ units. This share was up from 28% in 2023. The largest loss in market share for multifamily built-for-sale units was for buildings with 10-19 units, dropping from 23% in 2023 to just 13% in 2024.

Discover more from Eye On Housing

Subscribe to get the latest posts sent to your email.


This article was originally published by a eyeonhousing.org . Read the Original article here. .
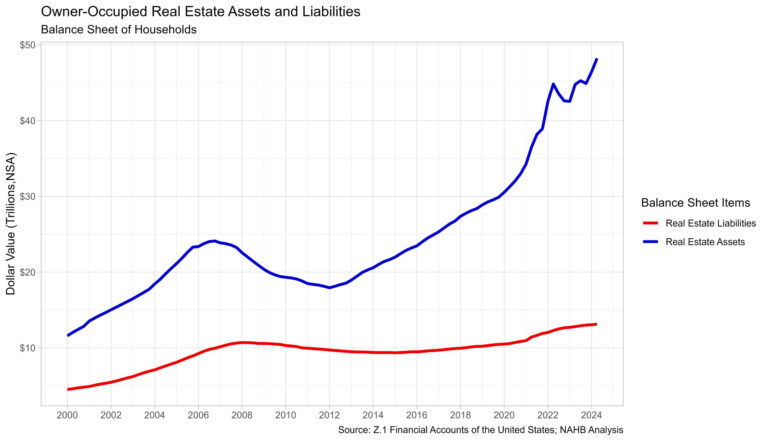

Owners’ equity share of household real estate assets remained above 70% for the tenth straight quarter, continuing to mark the highest levels of this share since the late 1950s. The share in the second quarter of 2024 was 72.7%, up from a year ago when it stood at 71.4%. Notably, this is the highest reading of owners’ equity share since the fourth quarter of 1958, when it was 73.3%.

Household real estate assets represent all types of owner-occupied housing including farm houses and mobile homes, as well as second homes that are not rented, vacant homes for sale, and vacant land at current market value. Household real estate liabilities represent all outstanding residential mortgages as well as loans made under home equity lines of credit and home equity loans secured by junior liens. Owners’ equity is the difference between the current market value of the household’s property and the existing debt secured by the property (assets – liabilities).

The market value of household real estate assets rose from $46.4 trillion to $48.2 trillion in the second quarter of 2024 according to the most recent release of U.S. Federal Reserve Z.1 Financial Accounts. Over the year, household real estate assets were 7.7% higher in the second quarter following a 9.2% increase in the first quarter.

Household real estate secured liabilities, i.e. mortgages, home equity loans, and HELOCs, increased 0.8% over the second quarter to $13.1 trillion. This level is 2.6% higher than the second quarter of 2023, the same as the increase in the first quarter of 2.6%.

Discover more from Eye On Housing

Subscribe to get the latest posts sent to your email.


This article was originally published by a eyeonhousing.org . Read the Original article here. .

Pin It