Tag

Quarter

Browsing


Lending standards for most types of residential mortgages were essentially unchanged but overall demand was weaker in the fourth quarter of 2025, according to the recent release of the Senior Loan Officer Opinion Survey (SLOOS). However, for commercial real estate (CRE) loans, lending standards for multifamily were looser, while standards for construction & development were essentially unchanged. Demand for construction & development loans was stronger, while demand for multifamily loans was essentially unchanged for the quarter. 

After three consecutive 25 basis point cuts to finish 2025, the Federal Reserve decided to maintain its key short-term interest rate (i.e., Federal Funds) unchanged during its first meeting of 2026. Participants on the Federal Open Market Committee (FOMC) continue to assess how to weigh the components of its dual mandate, as inflation continues to be above the stated target of 2% (i.e., the case for higher rates) while the economy is experiencing further deceleration in job growth (i.e., the case for lower rates). Given the current macroeconomic landscape and a change in leadership at the Fed as Jerome Powell’s term as Chair ends in May, NAHB anticipates that any further rate cuts will occur in the latter half of this year.

Residential Mortgages

In the fourth quarter of 2025, three of seven residential mortgage loan categories; GSE-eligible, Qualified Mortgage (QM) non-jumbo non-GSE eligible, and Government, saw a positive net easing index for lending conditions with an additional two (non-QM non-jumbo and QM jumbo) recording a neutral reading (i.e., 0). Subprime and non-QM jumbo loans experienced tighter lending conditions, as evidenced by a negative value, -8.3 and -4.2 respectively.

All seven residential mortgage loan categories reported weaker demand in the fourth quarter of 2025, with the weakest demand coming from subprime loans. This category has experienced weaker demand for 22 consecutive quarters.

Commercial Real Estate (CRE) Loans

For the CRE loan categories, multifamily registered a net easing index of +5.5 for the fourth quarter of 2025, indicating looser credit conditions for the first time since Q1 2022. As a reminder, this was when the Federal Reserve began their aggressive rate hiking path, which saw the Federal Funds rate increase by 525 basis points over a year and a half period. For construction & development loans, the net easing index was -1.8, or essentially unchanged.

The net percentage of banks reporting stronger demand was 8.9% for construction & development loans, with a positive number indicating stronger demand. This is the first time construction & development has been positive since Q4 2021. For multifamily loans, demand was -1.9% in the fourth quarter of 2025, which is essentially unchanged according to the Fed’s classification scheme (i.e., between -5.0% and +5.0%).


This article was originally published by a eyeonhousing.org . Read the Original article here. .
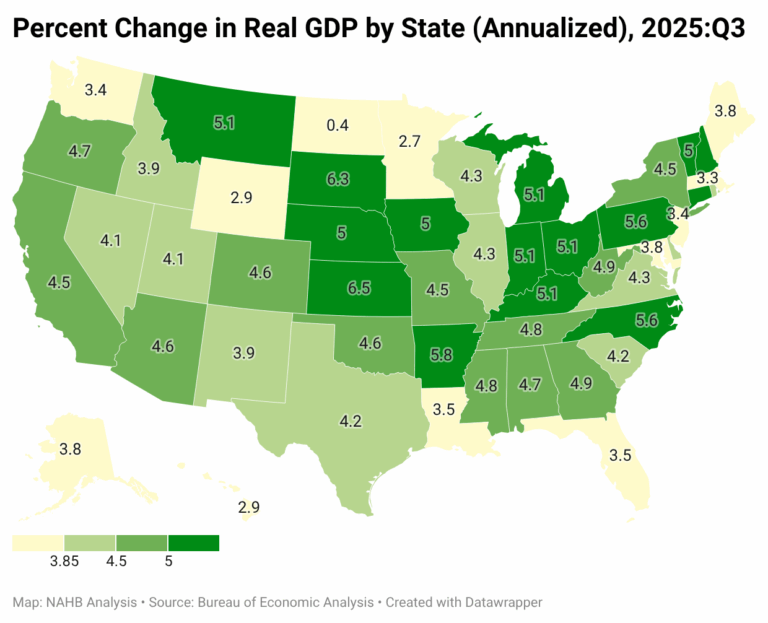

In the third quarter of 2025, the Bureau of Economic Analysis (BEA) reported that real gross domestic product (GDP) expanded nationally, with growth recorded across all states and the District of Columbia. The increase in GDP reflected broad-based economic momentum, supported by contributions from several major industries. At the state level, real GDP growth ranged from a 6.5 percent increase in Kansas to a 0.4 percent increase in North Dakota.

Nationally, real GDP, measured at a seasonally adjusted annual rate, increased 4.4 percent in the third quarter of 2025, led by growth in information; finance and insurance; and professional, scientific, and technical services.

Regionally, real GDP increased in all eight regions between the second and the third quarters of 2025. Growth was widespread, with regional gains ranging from a 4.2 percent increase in the New England region to a 4.8 percent increase in the Great Lakes region, underscoring broad economic strength across the country.

Service-providing sectors, including information, finance and insurance, and professional and business services, were key drivers of growth across many states. Agriculture and related industries played an especially important role in select states, including Kansas and South Dakota, which recorded the two highest growth rates in real GDP during the quarter. Manufacturing activity, particularly in durable goods, also contributed to higher output in several regions, including Arkansas and Connecticut, which posted the third- and fourth-largest increases in real GDP, respectively. While most states experienced strong expansion, a small number of states and the District of Columbia posted more modest gains, highlighting regional differences in economic performance.

At the industry level, information services, finance and insurance, and professional, scientific, and technical services were the most consistent contributors to GDP growth nationwide. However, several sectors weighed on growth in specific regions, including management of companies and enterprises; government and government enterprises; nondurable goods manufacturing; and construction, all of which contracted during the third quarter.

Overall, the third quarter state GDP data point to a broadly expanding U.S. economy, with growth evident across all states and supported by a diverse mix of industries. Although the drivers of growth varied by region, reflecting differences in industrial composition, the widespread gains in economic output underscore resilient economic activity at both the state and national levels and suggest continued momentum in overall GDP.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


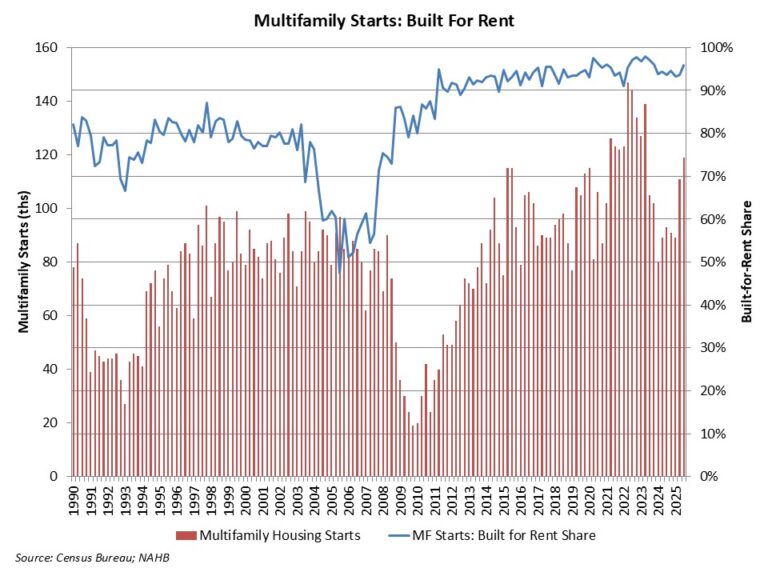
According to NAHB analysis of quarterly Census data, the count of multifamily, for-rent housing starts increased during the third quarter of 2025. For the quarter, 119,000 multifamily residences started construction. Of this total, 114,000 were built-for-rent. This built-for-rent total was 31% higher than the third quarter of 2024. This marks a significant increase, and it is possible these numbers will be revised lower in future Census data given other multifamily data reporting.

The market share of rental units of multifamily construction starts was 95% for the third quarter. A historical low market share of 47% for built-for-rent multifamily construction was set during the third quarter of 2005, during the condo building boom. An average share of 80% was registered during the 1980-2002 period.

For the third quarter, there were 5,000 multifamily condo unit construction starts, a decrease from a year ago.

An elevated rental share of multifamily construction is holding the typical apartment size below levels seen during the pre-Great Recession period. According to the third quarter 2025 data, the average square footage of multifamily construction starts decreased to 1,052 square feet. The median declined to 1,006 square feet. These measures are consistent with the elevated share of multifamily built-for-rent construction.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


In the third quarter of 2025, the NAHB/Westlake Royal Remodeling Market Index (RMI) posted a reading of 64, increasing four points compared to the previous quarter.

Most remodelers are finding reasonably strong market conditions, even with the normal seasonal slowdown during the holidays.  The major headwinds the industry is experiencing continue to be rising costs and potential customers hesitating due to policy and economic uncertainty.  Demand for remodeling is being supported by an aging housing stock, strong homeowner equity and increasing need for aging-in-place improvements.

The RMI is based on a survey that asks remodelers to rate various aspects of the residential remodeling market “good”, “fair” or “poor.”  Responses from each question are converted to an index that lies on a scale from 0 to 100. An index number above 50 indicates a higher proportion of respondents view conditions as good rather than poor.

Current Conditions

The Remodeling Market Index (RMI) is an average of two major component indices: the Current Conditions Index and the Future Indicators Index. 

The Current Conditions Index is an average of three subcomponents: the current market for large remodeling projects ($50,000 or more), moderately-sized projects ($20,000 to $49,999), and small projects (under $20,000).  In the fourth quarter of 2025, the Current Conditions Index averaged 71, increasing three points from the previous quarter.  All three components increased quarter-over-quarter and remained above the break-even point of 50.  Large remodeling projects saw the largest increase, rising five points to 69, followed by small remodeling projects adding two points to 73, and moderately-sized projects, inching up one point to 70.

Future Indicators

The Future Indicators Index is an average of two subcomponents: the current rate at which leads and inquiries are coming in, and the current backlog of remodeling projects. 

In the fourth quarter of 2025, the Future Indicators Index averaged 56, up four points from the previous quarter.  Both components increased quarter-over-quarter and are above the break-even point of 50.  The component measuring the current rate at which leads and inquiries are coming in rose five points to 54 while the component measuring backlog of remodeling jobs added two points to 58.

For the full set of RMI tables, including regional indices and a complete history for each RMI component, please visit NAHB’s RMI web page.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


The market value of household real estate assets fell to $48.0 trillion in the third quarter of 2025, according to the most recent release of U.S. Federal Reserve Z.1 Financial Accounts. The third quarter value is 0.7% lower than the second quarter but is 1.5% higher than a year ago.

This measure of market value estimates the value of all owner-occupied real estate nationwide. The calculation combines both repeat-home sales data with estimates of additions to the housing stock, essential measuring both price changes and the change in quantity of housing assets. This approach explains why household real estate wealth can continue to rise even as other measures may show a slowing in home price growth.

Real estate secured liabilities of households’ balance sheets, i.e. mortgages, home equity loans, and HELOCs, increased 0.8% in the third quarter to $13.6 trillion. This level is 2.8% higher compared to the third quarter of 2024.

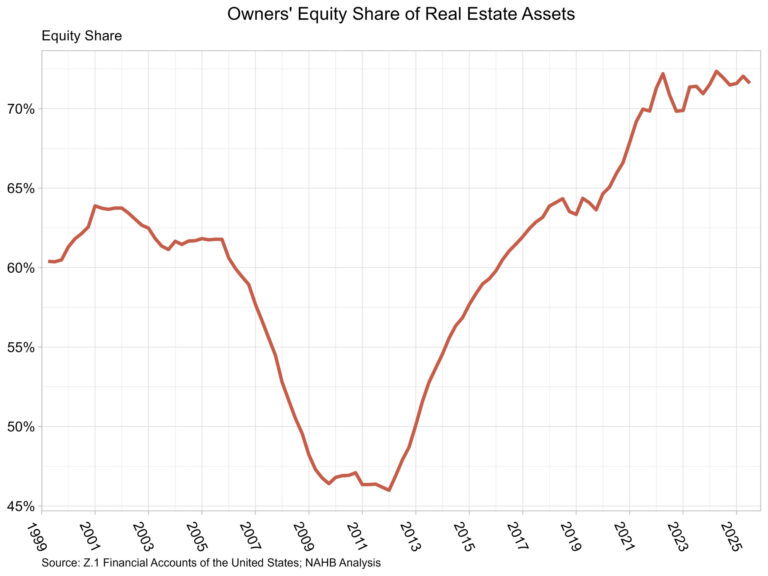
Owners’ equity share of real estate assets was 71.6% in the third quarter, slightly lower than the second quarter due to the decline in real estate asset values. The share in the third quarter of 2024 was 72.0% and has been above 70% for 15 consecutive quarters, the longest stretch since the 1950s. Owners’ equity in real estate was $34.4 trillion in the third quarter.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


A belated GDP report shows that the U.S. economy expanded at a strong pace in the third quarter–July through September–before signs of cooling appeared in the labor market and consumer confidence weakened.

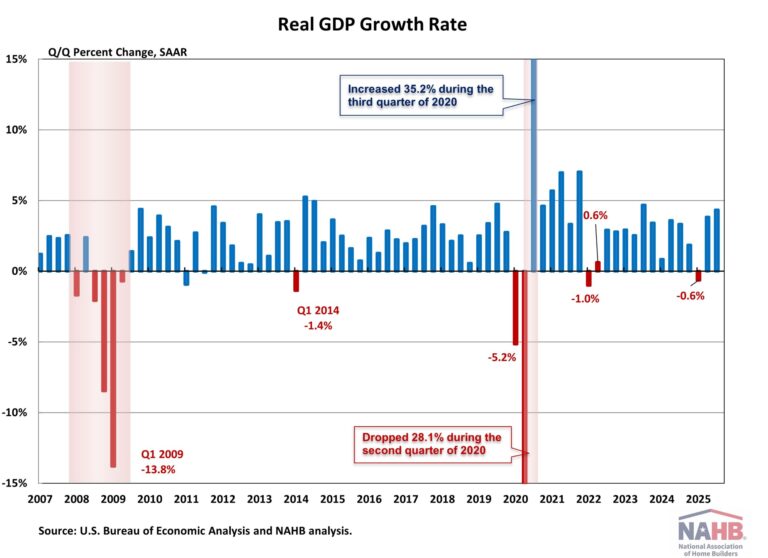
According to the “advance” estimate released by the Bureau of Economic Analysis (BEA), real gross domestic product (GDP) expanded at an annual rate of 4.3% in the third quarter of 2025, accelerating from a 3.5% increase in the second quarter. This marks the strongest pace of annual economic growth in the past two years. This growth rate was above the NAHB forecast for the quarter as well.

Furthermore, the latest data from the GDP report indicates that inflationary pressures intensified over the quarter. The GDP price index rose 3.8% for the third quarter, up from a 2.1% increase in the second quarter of 2025. The Personal Consumption Expenditures Price (PCE) Index, which measures inflation (or deflation) across various consumer expenses and reflects changes in consumer behavior, increased 2.8% during the quarter. This is higher than a 2.1% rise in the previous quarter.

This quarter’s increase in real GDP primarily reflected stronger consumer spending, exports, and government spending, which were partially offset by a decrease in investment. Imports, which are a subtraction in the calculation of GDP, decreased during the quarter as tariffs had measurable effects.

Consumer spending, the backbone of the U.S. economy, rose at an annual rate of 3.5% in the third quarter, its strongest rate since the fourth quarter of 2024. Both goods and services contributed to the gain, with spending on goods rising at a 3.1% annual rate and spending on services increasing 3.7%.

Government spending also added to economic growth, reflecting increases in both state and local government spending (led by higher consumption expenditures) as well as increased federal government spending, driven by defense consumption expenditures. 

Nonresidential fixed investment increased 2.8% in the third quarter. The increases in equipment (+5.4%) and intellectual property products (+5.4%) offset the decrease in structures (-6.3%). Meanwhile, residential fixed investment (RFI) continued to contract, declining 5.1% for the second consecutive quarter. Within the residential category, single-family structures fell 8.9% at an annual rate, multifamily structures declined 2.9%, and spending on home improvements dropped 7.6%.

For the common BEA terms and definitions, please access bea.gov/Help/Glossary.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


House prices continued to rise in the third quarter of 2025, though the pace of growth slowed as elevated mortgage rates, affordability challenges, and persistent economic uncertainty weighed on consumer demand. After several years of rapid growth, Hawaii and 38 metro areas saw house price declines this quarter, highlighting significant regional variations in market conditions.

Nationally, according to the quarterly all-transactions House Price Index (HPI) released by the Federal Housing Finance Agency (FHFA), U.S. house prices rose 3.3% in the third quarter of 2025, compared to the same period in 2024. This represents the slowest year-over-year price appreciation since 2013, indicating a cooling in the housing market following a decade of robust price growth.

The FHFA’s all-transactions HPI tracks average price changes based on repeat sales and refinancings of the same single-family properties. It offers insights not only at the national level but also across states and metropolitan areas.

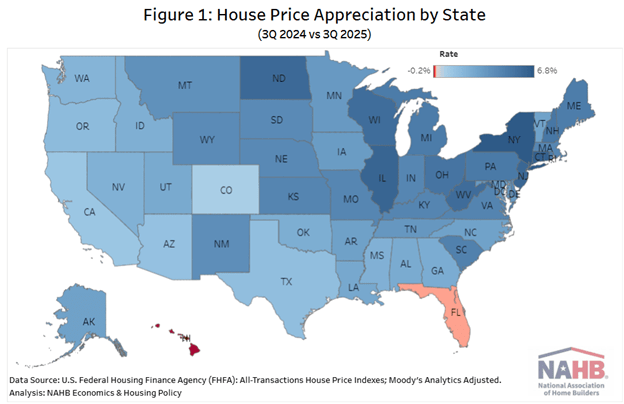
Between the third quarter of 2024 and the third quarter of 2025, 48 states and the District of Columbia experienced positive year-over-year (YoY) house price appreciation, with gains ranging from 0.6% to 6.8%. Hawaii was the only state to record a decline, while Florida posted no growth. New York led all states with a 6.8% gain, followed by Connecticut with a 6.5% gain and Illinois with a 6.2% gain. On the opposite end, Colorado posted the lowest house price appreciation at 0.6%. Notably, out of all 50 states and the District of Columbia, 29 states exceeded the national YoY growth rate of 3.3%. However, on a quarterly basis, home price appreciation decelerated in 45 states compared to the second quarter of 2025, highlighting a broad-based deceleration in the housing market.

House price growth also varied widely across U.S. metro areas, ranging from a 7.8% decline to a 16.0% increase year-over-year. Punta Gorda, FL recorded the steepest drop, while Farmington, NM posted the strongest gains over the previous four quarters. In the third quarter of 2025, 34 metro areas, in reddish color on the map above, experienced negative house price growth, while 351 metro areas posted increases.

Since the onset of the COVID-19 pandemic, house prices have surged nationally. Between the first quarter of 2020 and the third quarter of 2025, house prices climbed 54.9% nationwide, with more than half of metro areas exceeding this rate. However, 226 metro areas have seen varying degrees of decline from their post-COVID peaks, ranging from -0.1% to -12.7%.

The map below presents the top ten and bottom ten markets for house price appreciation over the past five years. Among all the metro areas, house price appreciation ranged from 18.3% to 88.4%. Knoxville, TN topped the list with the highest house price appreciation, while Odessa, TX posted the lowest appreciation, ending Lake Charles, LA’s five-quarter run at the bottom.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


Single-family construction lending picked up in the third quarter, amidst the overall cooling lending environment. Loan balances for 1-4 family construction grew to $91.2 billion in the third quarter, registering the first annual increase in over two years. However, across all acquisition, development and construction (AD&C) loans, the total volume fell for the seventh straight quarter.

According to data from the Federal Deposit Insurance Corporation (FDIC), the total level of outstanding AD&C loans fell to $463.0 billion in the third quarter of 2025, down 5.6% from one year ago. This year-over-year decrease was led by a drop in other real estate development loans, which decreased 7% over the year to $371.8 billion. Meanwhile, the volume of 1-4 family residential construction and land development loans rose to $91.2 billion in the third quarter, up 0.5% from one year ago.

It is worth noting, the FDIC data represent only the stock of loans, not changes in the underlying flows, so it is an imperfect data source. Nonetheless, lending remains much reduced from years past. The current amount of existing 1-4 family residential AD&C loans now stands 56% lower than the peak level of residential construction lending of $204 billion reached during the first quarter of 2008. Alternative sources of financing, including equity partners, have supplemented this capital market in recent years.

Quality Metrics of Construction Loans

While the total volume of 1-4 family residential construction loans rose, the volume of loans 30+ days past due or nonaccrual status fell slightly to $1.1 billion over the quarter. As a share of the total 1-4 family residential construction loan volume, this accounts for 1.2%.

Breaking this out further, the level of loans 30-89 days past due was $418.1 million, while the volume in nonaccrual status was $593.4 million. The nonaccrual loan status volume increased from $572.4 million in the second quarter and the 30-89 past due fell from $469.2 million.

Loans are classified as nonaccrual when one or more of the following conditions apply: the loan is 90 days or more past due on principal or interest (unless it is well-secured and in the process of collection); the bank no longer expects full repayment of principal and interest; or the borrower’s financial condition has significantly deteriorated, warranting cash-basis accounting.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


Lending standards for most types of residential mortgages were essentially unchanged, according to the recent release of the Senior Loan Officer Opinion Survey (SLOOS). For commercial real estate (CRE) loans, lending standards for construction & development were modestly tighter, while multifamily was essentially unchanged.  Demand for both CRE categories was essentially unchanged for the quarter. 

Two weeks ago, the Federal Reserve eased its key short-term interest rate (i.e., Federal Funds) by 25 basis points for the second consecutive meeting, establishing an upper bound of 4.00%.  While the causal link between the Federal Funds rate and the 30-year fixed rate mortgage is minimal, these cuts will have a more tangible impact for private home builders through lower rates on acquisition, development, & construction (AD&C) loans.  Roughly 60% of single-family starts are built by private builders. With pressure from both sides of their dual mandate as the job market cools and inflation remains sticky, NAHB is forecasting a measured approach from the Fed when it comes to further rate cuts next year.

Residential Mortgages

In the third quarter of 2025, four of seven residential mortgage loan categories saw a positive net easing index for lending conditions with an additional two recording a neutral reading (i.e., 0).  Only subprime loans experienced tighter lending conditions, as evidenced by a negative value (-6.3).  Nevertheless, based on the Federal Reserve classification of any reading between -5.0 and +5.0 as “essentially unchanged,” all but subprime fell within this range.

Five of the seven residential mortgage loan categories reported stronger demand in the third quarter of 2025, with the strongest demand coming from Government, GSE-eligible, and Qualified Mortgage (QM) non-jumbo, non-GSE eligible loans.  Non-QM jumbo was essentially unchanged for the quarter, while subprime loans were the only category to experience weaker demand, which has been the case since Q3 of 2020.

Commercial Real Estate (CRE) Loans

For the CRE loan categories, construction & development loans registered a net easing index of -6.6 for the third quarter of 2025, indicating modestly tighter credit conditions.  For multifamily loans, the net easing index was -1.6, or essentially unchanged.  Both categories of CRE loans show tightening of lending conditions (i.e., net easing indexes below zero) since Q2 2022.  However, the tightening has become less defined recently for multifamily, with its net easing index essentially unchanged (i.e., between -5.0 and +5.0) for four consecutive quarters.

The net percentage of banks reporting stronger demand was -4.9% for construction & development loans, with a negative number indicating weaker demand.  For multifamily, demand was neutral (i.e., 0) in the third quarter of 2025, with the same number of banks that reported weaker demand as those who reported stronger demand.  However, demand for CRE loans within both categories has experienced unchanged conditions (i.e., between -5.0% and +5.0%).


This article was originally published by a eyeonhousing.org . Read the Original article here. .

Confidence in the market for new multifamily housing increased year-over-year in the third quarter, according to the Multifamily Market Survey (MMS) released today by the National Association of Home Builders (NAHB). The MMS produces two separate indices. The Multifamily Production Index (MPI) had a reading of 46, up six points year-over-year, while the Multifamily Occupancy Index (MOI) had a reading of 74, down one point year-over-year.

The MPI and MOI are giving a mixed picture, creating a bifurcation of the multifamily market.  While MPI is still in negative territory, developers of low-rise market-rate and subsidized rental properties express increased optimism, with both components above 50 for the quarter.  Weakness is concentrated in the mid-to-high-rise and condominium developments which tend to be common in high-density metro areas.  This is consistent with NAHB’s Home Building Geography Index where multifamily construction activity is growing in areas with low population densities but weakening in the larger metros. 

Even though MOI is in positive territory and existing apartment owners are positive about occupancy overall, this is the lowest reading since NAHB redesigned the survey starting in Q1 2023.  Sentiment for mid/high-rise apartment occupancy is noticeably weaker than it is for the other two rental market segments.

Multifamily Production Index (MPI)

The MMS asks multifamily developers to rate the current conditions as “good”, “fair”, or “poor” for multifamily starts in markets where they are active.  The index and all its components are scaled so that a number above 50 indicates that more respondents report conditions as good rather than poor. The MPI is a weighted average of four key market segments: three in the built-for-rent market (garden/low-rise, mid/high-rise, and subsidized) and the built-for-sale (or condominium) market.

All four components experienced year-over-year increases in the third quarter of 2025: both the components measuring mid/high rise and subsidized units jumped up nine points to 37 and 55, respectively, the component measuring built-to-sale units increased six points to 35, and the component measuring garden/low-rise units increased three points to 51.

Multifamily Occupancy Index (MOI)

The survey also asks multifamily property owners to rate the current conditions for occupancy of existing rental apartments, in markets where they are active, as “good”, “fair”, or “poor”.  Like the MPI, the MOI and all its components are scaled so that a number above 50 indicates more respondents report that occupancy is good than as poor.  The MOI is a weighted average of three built-for-rent market segments (garden/low-rise, mid/high-rise and subsidized). 

Two of the three MOI components experienced year-over-year decreases in the third quarter of 2025; the component measuring subsidized units fell by five points to 81 and the garden/low-rise component dipped one point to 76.  Meanwhile, the component measuring mid/high-rise units was unchanged at 66.  All three MOI components remain well above the break-even point of 50.

The MMS was re-designed in 2023 to produce results that are easier to interpret and consistent with the proven format of other NAHB industry sentiment surveys.  Until there is enough data to seasonally adjust the series, changes in the MMS indices should only be evaluated on a year-over-year basis.

Please visit NAHB’s MMS web page for the full report.

Discover more from Eye On Housing

Subscribe to get the latest posts sent to your email.


This article was originally published by a eyeonhousing.org . Read the Original article here. .
Pin It