Tag

Quarter

Browsing


Real GDP growth slowed in the second quarter of 2026, as a pullback in government spending and slower growth in investment and exports, more than offset stronger consumer spending. Business investment continued to support growth, particularly through equipment and intellectual property products, while imports increased and remained a drag on headline GDP.

According to the “advance” estimate released by the Bureau of Economic Analysis (BEA), real gross domestic product (GDP) expanded at an annual rate of 1.5% in the second quarter, down from a 2.1% increase in the first quarter of 2026.

The latest GDP report also showed that inflationary pressures remained elevated. The price index for gross domestic purchases rose 5.7% in the second quarter, up from 3.6% in the first quarter. The Personal Consumption Expenditures (PCE) Price Index, which measures inflation (or deflation) across various consumer expenses and reflects changes in consumer behavior, increased 5.1%, compared with a 4.6% increase in the previous quarter. Excluding food and energy, the core PCE price index increased 3.4%, easing from 4.4% in the first quarter.

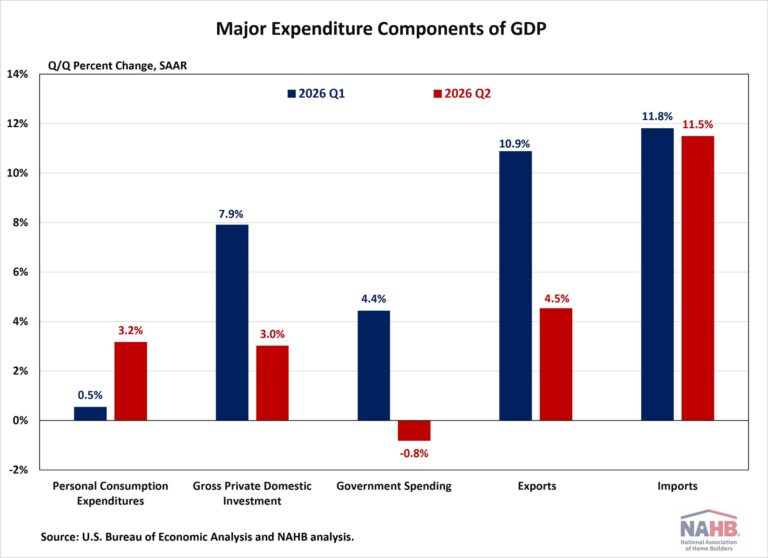
Breaking down the second-quarter data further, growth in real GDP primarily reflected gains in consumer spending, investment, and exports, which were partly offset by a decrease in government spending. Imports, which are a subtraction in the calculation of GDP, increased during the quarter.

Consumer spending, the backbone of the U.S. economy, accelerated in the second quarter, rising at an annual rate of 3.2% after a 0.5% increase in the first quarter. This acceleration helped offset weakness in other components of GDP and supported the broader measure of underlying private demand.

Real final sales to private domestic purchasers, the sum of consumer spending and gross private fixed investment, increased 3.9% in the second quarter, up from 1.7% in the first quarter. This measure suggests that private domestic demand strengthened even as headline GDP growth slowed.

Gross private domestic investment continued to expand in the second quarter, although at a slower pace than in the first quarter. Gains in equipment and intellectual property products supported business investment, while private inventories and some structures categories weighed on growth.

Nonresidential fixed investment increased 8.4% in the second quarter. Strong gains in equipment (+15.2%) and intellectual property products (+8.8%) offset a decrease in structures (-5.0%). Meanwhile, residential fixed investment (RFI) rose 1.5%, making its first positive contribution after five consecutive quarters of weakness. Within the residential category, investment in single-family permanent site structures rose 4.4% at an annual rate, multifamily permanent site structures declined 1.8%, and spending on improvements fell 5.0%.

Government spending declined 0.8% in the second quarter, reversing the prior quarter’s boost and contributing to the slowdown in overall economic growth.

Trade activity remained positive but less supportive of GDP growth. Exports continued to increase, although at a slower pace than in the first quarter, while imports accelerated. Because imports are subtracted from GDP, the increase in imports reduced second-quarter headline growth.

For the common BEA terms and definitions, please access bea.gov/Help/Glossary.


This article was originally published by a eyeonhousing.org . Read the Original article here. .
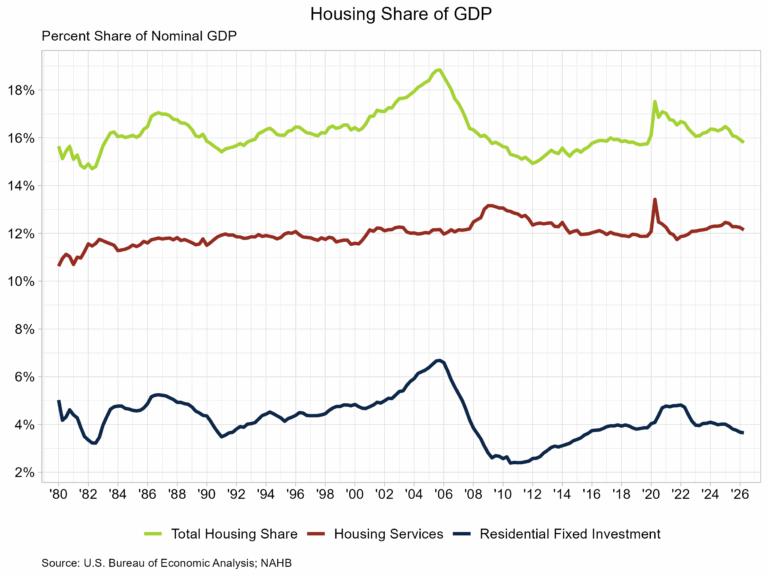

Housing’s share of the economy was 15.8% in the second quarter of 2026, according to the latest estimates of GDP produced by the Bureau of Economic Analysis. This share is down from 15.9% in the first quarter and is at the lowest level since 2019. Residential construction, measured by residential fixed investment, rose for the first time in over a year, while households’ expenditure on housing services fell due to lower household consumption of utilities.

The more cyclical home building and remodeling component–residential fixed investment (RFI)–was 3.7% of GDP, even with the previous quarter. The second component, housing services, was 12.1% of GDP, down from 12.2% in the previous quarter. The graph below plots the share for housing services and RFI, along with housing’s total share of nominal GDP.

Housing service expenditures are much less volatile when compared to RFI due to the cyclical nature of RFI. Historically, RFI has averaged roughly 5% of GDP, while housing services have averaged between 12% and 13%, for a combined 17% to 18% of GDP. These shares tend to vary over the business cycle. However, the housing share of GDP lagged during the post-Great Recession period due to underbuilding, particularly in the single-family sector.

Residential Fixed Investment

In the second quarter, RFI contributed 5 basis points to the headline GDP growth rate. This was the first positive contribution to GDP from RFI since the fourth quarter of 2024. RFI was 3.7% of the economy, recording a $1.2 trillion seasonally adjusted annual pace.

RFI can be split into two segments, structures and equipment. Residential structure investment not only consists of new single-family and multifamily units but also includes manufactured homes, improvements, and dormitories. Residential equipment, which accounts for under 2% of total RFI, consists of furniture or household appliances that are purchased by landlords for rental to tenants. Real private investment in structures rose 1.3%, while investment in residential equipment rose 12.1%.

Breaking down the components of residential structures, single-family RFI rose 4.4%, while multifamily RFI fell 1.8%. Permanent site structure RFI, which is made up of single-family and multifamily RFI, rose 1.3%. The “other structures” RFI category was down 0.1% in the second quarter. This component consists primarily of manufactured homes, improvements, and dormitories. On a seasonally adjusted annual basis in the second quarter, private investment in permanent site structures was at $523.8 billion, while other structures totaled $639.3 billion.

Housing Services

The second impact of housing on GDP is the measure of housing services. Similar to RFI, housing services consumption can be broken into two components. The first component, housing, includes gross rents paid by renters, owners’ imputed rent (an estimate of how much it would cost to rent owner-occupied units), rental value of farm dwellings, and group housing. The inclusion of owners’ imputed rent is necessary from a national income accounting approach, because without this measure, increases in homeownership would result in declines in GDP. The second component, household utilities, is composed of consumption expenditures on water supply, sanitation, electricity, and gas.

For the second quarter, housing services represented 12.1% of the economy or $3.9 trillion on a seasonally adjusted annual basis. Real housing services expenditure declined 0.1% at an annual rate in the second quarter. Real personal consumption expenditure for housing grew 1.1%, while real household utilities expenditures declined 8.2%.

Personal consumption expenditure (PCE) on housing services is the largest component of PCE, making up 17.9% in the second quarter. The second largest component of PCE is health care services, at 16.8%. Expenditure on services was $15.2 trillion on a seasonally adjusted annual basis in the second quarter, more than double the expenditure on goods ($6.9 trillion).


This article was originally published by a eyeonhousing.org . Read the Original article here. .


In the second quarter of 2026, the NAHB Remodeling Market Index (RMI) posted a reading of 61, down one point compared to the previous quarter. The RMI has remained in the low 60s consistently over the past year.

Even with this slight decline from the previous quarter, remodeler sentiment remains the standout sector within the housing industry, outperforming both its single-family and multifamily counterparts.  

With current mortgage rates above the median outstanding rate for existing homeowners, the incentive to remodel instead of purchasing a new home given the low levels of existing inventory persists due to this lock-in effect. Additionally, homeowners are sitting on record high real estate asset gains which they are able to tap into making it easier to fund remodeling projects. However, ongoing economic uncertainty and current cost pressures due to inflation are causing project delays, especially for larger ones. In the latest RMI survey, 74% of remodelers reported that their suppliers have increased prices of materials since March due to higher fuel costs, with the average increase in materials prices over that span being 6.7%. 

Nevertheless, based on the positive sentiment from the RMI and structural demand tailwinds, NAHB’s forecast for remodeling spending remains robust both in the short-term and over the long run.

The RMI is based on a survey that asks remodelers to rate various aspects of the residential remodeling market “good”, “fair” or “poor.” Responses from each question are converted to an index that lies on a scale from 0 to 100. An index number above 50 indicates a higher proportion of respondents view conditions as good rather than poor.

Current Conditions

The Remodeling Market Index (RMI) is an average of two major component indices: the Current Conditions Index and the Future Indicators Index. 

The Current Conditions Index is an average of three components: the current market for large remodeling projects ($50,000 or more), moderately-sized projects ($20,000 to $49,999), and small projects (under $20,000).

In the second quarter of 2026, the Current Conditions Index averaged 70, unchanged from the previous quarter. The component measuring moderately-sized remodeling projects increased four points to 73, while the small projects component remained unchanged at 74 and the large projects component decreased three points to 64. 

Future Indicators

The Future Indicators Index is an average of two components: the current rate at which leads and inquiries are coming in, and the current backlog of remodeling projects.

In the second quarter of 2026, the Future Indicators Index averaged 52, down two points from the previous quarter. Both components decreased quarter-over-quarter but still remain above the break-even point of 50. The component measuring backlog of remodeling jobs was down two points to 54, while the component measuring the current rate at which leads and inquiries are coming in edged down one point to 51.

For the full set of RMI tables, including regional indices and a complete history for each RMI component, please visit NAHB’s RMI web page.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


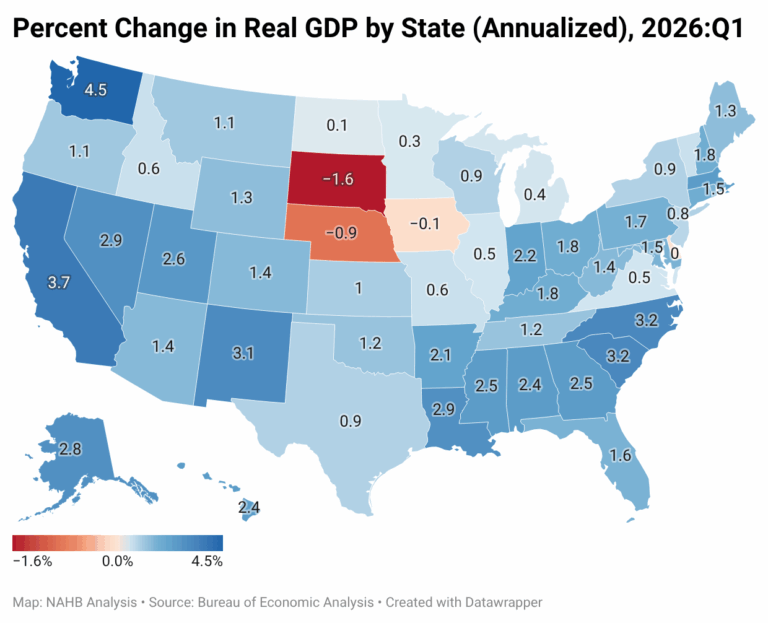
State economic growth strengthened in the first quarter of 2026, with real GDP increasing in 46 states and the District of Columbia. According to the Bureau of Economic Analysis (BEA), state-level growth rates ranged from a 4.5% annualized increase in Washington to a 1.6% decline in South Dakota, while Delaware’s economy was essentially unchanged during the quarter.

Nationally, real GDP, measured at a seasonally adjusted annual rate, increased by 2.1% in the first quarter of 2026, led by downward revisions to imports, which are a subtraction in the GDP equation and nonresidential investments. Consumer spending, which is the backbone of the U.S. economy, was revised lower in the third estimate.   

Regionally, real GDP increased in all eight regions between the last quarter of 2025 and the first quarter of 2026. Growth was comparatively higher compared to the previous quarter, with regional gains ranging from a 0.2% increase in the Plains region to a 3.6% increase in the Far West.           

The Pacific Northwest led state economic performance in the first quarter, with Washington (+4.5%) posting the strongest growth rate among all states. BEA reported that the information sector was the largest contributor to Washington’s economic expansion, reflecting continued strength in technology-related activity. California came in second with 3.7% real GDP growth, followed by North Carolina and South Carolina tied for third place with 3.2% real GDP growth. In contrast, South Dakota recorded the weakest performance, declining 1.6%, driven by the agriculture, forestry, fishing, and hunting sector. Nebraska and Iowa declined by 0.9% and 0.1% respectively, while Delaware was unchanged.

The broad-based nature of growth across states suggests that economic activity improved considerably from the slower pace recorded at the national level in late 2025. While growth was widespread geographically, state-level results continued to reflect differences in industrial composition. States with significant exposure to information and professional services industries generally outperformed, while states more dependent on agriculture faced greater headwinds during the quarter.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


U.S. house prices continued to rise in the first quarter of 2026, but appreciation slowed markedly from the rapid pace seen during the pandemic-era housing boom. Higher mortgage rates, persistent affordability challenges, and softer demand weighed on price growth nationally. At the same time, local market conditions varied considerably. Some states and metropolitan areas continued to post solid gains, while others experienced flat or declining house prices.

According to the quarterly purchase-only House Price Index1 (HPI) released by the Federal Housing Finance Agency (FHFA), national house prices rose 1.7% in the first quarter of 2026 from a year earlier. This growth rate represented the slowest annual appreciation since the second quarter of 2012, signaling the continued cooling of house price growth after more than a decade of strong gains. On a quarterly basis, house prices increased a modest 0.5% from the fourth quarter of 2025.

The FHFA’s purchase-only HPI tracks average price changes using more than six million repeat-sales transactions involving the same single-family properties. In addition to the national picture, the index provides valuable insight into house price trends across states and metropolitan areas.

At the state level, house price performance remained positive across most of the country in the first quarter of 2026, although appreciation rates varied widely. Annual appreciation ranged from a 2.4% decline to a 16.3% gain.

Puerto Rico recorded the strongest annual appreciation, with house prices surging 16.3% from a year earlier. Among the 50 states and the District of Columbia, Illinois posted the largest gain (7.3%), followed by Alaska (5.5%), Vermont (4.9%), and Connecticut (4.7%). More broadly, many states across the Midwest and Northeast continued to outperform the national average.

At the other end of the spectrum, Colorado recorded the largest annual decline, with house prices falling 2.4% from a year earlier. Texas and the District of Columbia also posted modest declines, while several Western and Sun Belt states saw only limited appreciation. Many of the markets that experienced some of the strongest price growth during 2021–2022 continue to face affordability pressures and softer buyer demand.

Overall, 42 states and Puerto Rico reported annual house price gains. In addition, 31 states and Puerto Rico matched or exceeded the national appreciation rate of 1.7%, underscoring the resilience of many regional housing markets despite challenging financing conditions.

House price performance varied even more widely across metropolitan areas than at the state level. Among the nation’s 100 largest metro areas tracked by FHFA, annual house price appreciation ranged from a decline of 6.9% to an increase of 10.8% in the first quarter of 2026.

The strongest-performing metro areas were concentrated primarily in the Midwest and Northeast, where limited housing supply continued to support price growth. Several metro areas in Pennsylvania, New York, Ohio, and Illinois posted especially strong annual gains, reflecting continued demand amid limited supply.

In contrast, some of the weakest-performing markets were located in Florida, Texas, and parts of the Mountain West. Austin-Round Rock-San Marcos, Texas, recorded the steepest annual price decline among the top 100 metro areas, continuing a correction after several years of exceptionally rapid house price growth. Cape Coral–Fort Myers, Florida, also remained among the nation’s weakest housing markets, extending a trend of price declines amid cooling demand and a gradual rebalancing of market conditions.

Overall, one-third of the 100 largest metro areas posted annual price declines in the first quarter of 2026, while the remaining two-thirds recorded either positive appreciation or essentially flat price growth.

Note:

Unless otherwise noted, this blog post uses the quarterly purchase-only House Price Index (HPI), which measures the sales prices of homes that are bought and sold, rather than the broader all-transactions HPI. The purchase-only HPI provides a more precise view of current market conditions.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


Multifamily missing middle construction declined at the start of 2026.

The missing middle construction sector includes development of medium-density housing, such as townhouses, duplexes and other small multifamily properties. The multifamily segment of the missing middle (apartments in 2- to 4-unit properties) has generally disappointed since the Great Recession.

For the first quarter of 2026, there were 4,000 2- to 4-unit housing unit construction starts. This was down significantly compared to the first quarter of 2025.

Over the last four quarters, there were 23,000 such starts, down slightly from the prior four quarter period (24,000). Despite some gains in 2025, this subsector of residential construction continues to underperform relative to its potential, due in part to zoning restrictions.

As a share of all multifamily production, 2- to 4-unit development was just 4% of total multifamily development for the fourth quarter. This remains lower than recent historical trends. From 2000 to 2010, such home construction made up a little less than 11% of total multifamily construction.

Construction of the missing middle has clearly lagged during the post-Great Recession period and will continue to do so without zoning reform focused on light-touch density.


This article was originally published by a eyeonhousing.org . Read the Original article here. .

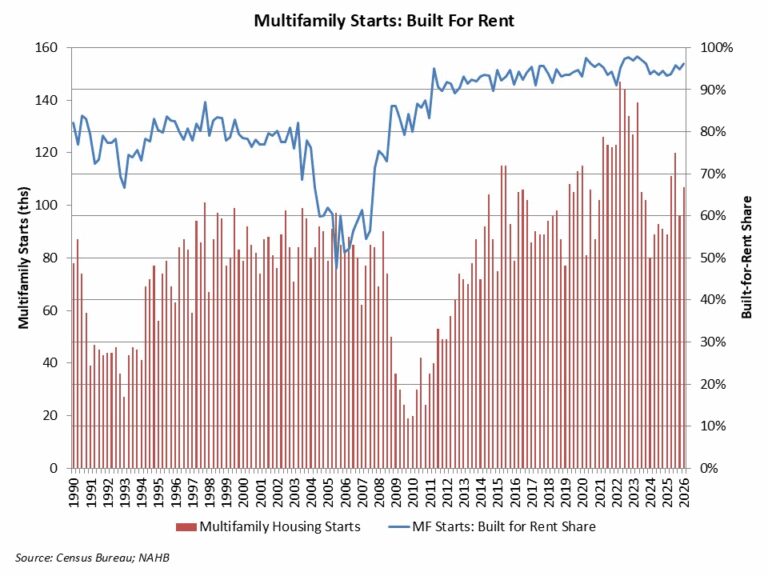
According to NAHB analysis of quarterly Census data, the count of multifamily, for-rent housing starts increased year-over-year during the first quarter of 2026. For the quarter, 107,000 multifamily residences started construction. Of this total, 103,000 were built-for-rent. This built-for-rent total was 21% higher than in the first quarter of 2025. Prior NAHB analysis suggests this expansion primarily occurred in smaller metro areas and lower density markets, given ongoing weakness in urban core areas.

The market share of rental units of multifamily construction starts was 96% for the first quarter. A historical low market share of 47% for built-for-rent multifamily construction was set during the third quarter of 2005, during the condo building boom. An average share of 80% was registered during the 1980-2002 period.

For the first quarter, there were 4,000 multifamily condo unit construction starts, down significantly from a year ago (7,000) given ongoing housing affordability challenges.

An elevated rental share of multifamily construction is holding typical apartment size below levels seen during the pre-Great Recession period. According to the first quarter 2026 data, the average square footage of multifamily construction starts declined to 1,047 square feet. The median, or typical unit, posted a large decline to 960 square feet, the lowest on record. These measures are consistent with the elevated share of multifamily built-for-rent construction.


This article was originally published by a eyeonhousing.org . Read the Original article here. .

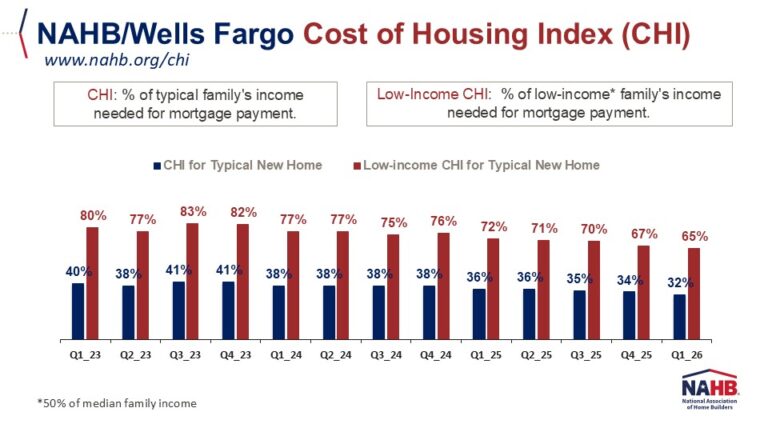
While housing affordability remains out of reach for millions of Americans, particularly first-time and entry-level buyers, conditions have improved modestly in the last year, according to the latest data from the National Association of Home Builders (NAHB)/Wells Fargo Cost of Housing Index (CHI). The CHI results from the first quarter of 2026 show that a family earning the nation’s median income of $106,800 needed 32% of its income to cover the mortgage payment on a median-priced new home. Low-income families, defined as those earning only 50% of median income, would have to spend 65% of their earnings to pay for the same new home.

In the last year, the income share needed to buy a new home declined from 36% in the second quarter of 2025, to 35% in the third quarter, 34% in the fourth quarter, and to 32% in the first quarter of 2026. Although home buyers continue to grapple with elevated mortgage rates and economic uncertainty, these figures indicate a modest improvement in affordability.

The same trend holds true for existing homes. A typical family would have had to pay 37% of their income for a median-priced existing home in the second quarter of 2025, 36% in the third quarter, 34% in the fourth quarter, and 32% in the first quarter of 2026. A low-income family would have needed to pay 65% of their earnings to make the same mortgage payment on an existing home in the first three months of 2026.

The U.S. data for the percentage of earnings needed to purchase a new home in the first quarter is based on a national median new home price of $403,200 and median income of $106,800. The first quarter median new home price is down slightly from $405,300 in the fourth quarter of 2025. Meanwhile, the corresponding price for an existing home fell more sharply in the first quarter to $404,300 from $414,900 in the previous quarter. The average 30-year mortgage rate edged slightly lower from 6.32% in the fourth quarter to 6.20% in the first quarter.

CHI is also available for 175 metropolitan areas, calculating the percentage of a family’s income needed to make the mortgage payment on an existing home based on the local median home price and median income in those markets.

In seven out of 175 markets in the first quarter, the typical family is severely cost-burdened (must pay more than 50% of their income on a median-priced existing home). In 59 other markets, such families are cost-burdened (need to pay between 31% and 50%). There are 109 markets where the CHI is 30% of earnings or lower.

The Top 5 Severely Cost-Burdened Markets

San Jose-Sunnyvale-Santa Clara, Calif., was the most severely cost-burdened market in the CHI, where 79% of a typical family’s income is needed to make a mortgage payment on an existing home. This was followed by:

Urban Honolulu, Hawaii (68%)

San Diego-Chula Vista-Carlsbad, Calif. (65%)

San Francisco-Oakland-Fremont, Calif. (63%)

Naples-Marco Island, Fla. (58%)

Low-income families would have to pay between 115% and 158% of their income in all five of the above markets to cover a mortgage.

The Top 5 Least Cost-Burdened Markets

By contrast, Decatur, Ill., was the least cost-burdened markets on the CHI, where typical families needed to spend just 12% of their income to pay for a mortgage on an existing home. Rounding out the least burdened markets are:

Peoria, Ill. (15%)

Elmira, N.Y. (16%)

Springfield, Ill. (17%)

Davenport-Moline-Rock Island, Iowa-Ill. (18%)

Low-income families in these markets would have to pay between 25% and 37% of their income to cover the mortgage payment for a median-priced existing home.

Visit nahb.org/chi for tables and details.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


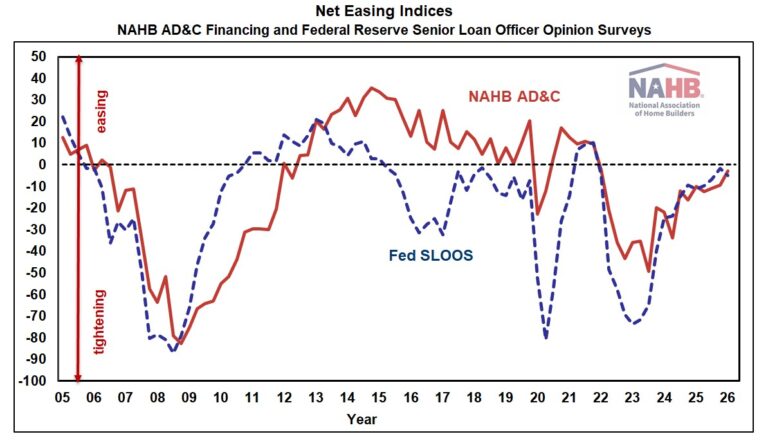
Credit conditions on loans for residential Land Acquisition, Development & Construction (AD&C) were still tightening in the first quarter of 2026, but only slightly, according to NAHB’s quarterly survey on AD&C Financing. The net easing index derived from the NAHB survey posted a first-quarter reading of -2.7. Although still negative (indicating that credit tightened since 2025 Q4), this is the closest the index has come to zero in the last four years.

Like the NAHB index derived from a survey of borrowers, a similar net easing index surveying lenders is produced from the Federal Reserve’s Senior Loan Officer Survey. This survey posted a reading of -4.9 in the first quarter of 2026, which was similarly still negative but fairly close to zero. The Fed considers anything between -5.0 and +5.0 “essentially unchanged.” Nonetheless, this marks the seventeenth consecutive quarter that both Fed and NAHB indices have been in negative territory.

More details from the Fed’s survey of lenders—including measures of demand and net easing for residential mortgages—appeared in a previous post.

Results on the cost of credit in the first quarter were mixed. The average contract rate on loans for pre-sold single-family construction increased slightly from 7.16% to 7.19% over the quarter.The other three categories of loans tracked in NAHB’s AD&C survey declined since the previous quarter: from 7.51% to 7.42% on loans for land acquisition, from 7.44% to 7.27% on loans for land development, and from 7.47% to 7.31% on loans for speculative single-family construction.   

Probably of greater significance were the changes in initial points charged on the loans, which can be particularly important on loans paid off as quickly as they typically are for single-family construction. The average initial points decreased from 0.70% to 0.50% on loans for land acquisition, but increased from some of the lowest percentages on record in the fourth quarter of 2025 for the other three categories of AD&C loans. The increases were from 0.44% to 0.50% on loans for land development, from 0.34% to 0.62% on loans for speculative single-family construction, and from 0.37% to 0.55% on loans for pre-sold single-family construction.

Those combinations of quarter-to-quarter changes caused the average effective interest rate (taking both contract rate and initial points into account) to decline from 9.81% to 9.36% on loans for land acquisition and from 10.28% to 10.15% on loans for land development, but to increase from 10.64% to 11.22% on loans for speculative single-family and from 11.01% to 11.68% on loans for pre-sold single-family construction.

Although results on the average effective interest rate were mixed on a quarter-to-quarter basis, the rate for each of the four types of AD&C loans has declined significantly since peaking in the period between 2023 Q3 and 2024 Q2.

Also in the NAHB AD&C survey, 35% of respondents who built single-family homes during the first quarter of 2026 reported financing some of their homes with a construction-to-permanent (one-time-close) loan made to the ultimate home buyer. On average, 51% of the homes these respondents built were financed in this manner.

More detail on credit conditions for residential builders and developers is available on NAHB’s AD&C Financing Survey web page.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


Lending standards and demand for most types of residential mortgages were essentially in the first quarter of 2026, according to the recent release of the Senior Loan Officer Opinion Survey (SLOOS). For commercial real estate (CRE) loans, lending standards for multifamily construction & development were essentially unchanged as well. Compared to the previous quarter, demand for construction & development loans was weaker, while demand for multifamily loans was essentially unchanged. 

The Federal Reserve has maintained its key short-term interest rate (i.e., Fed Funds) unchanged during the first three meetings of 2026. There has been growing division between FOMC participants on the appropriate trajectory of the Fed Funds rate that will satisfy their dual mandate of maximum employment and stable prices (i.e., inflation). Along with the arrival of a new Chair and the exogenous shocks to the global economy caused by the ongoing conflict in Iran, this has created a “wait-and-see” approach to monetary policy. As a result, NAHB does not forecast any changes to the Fed Funds rate until the end of the year.

Residential Mortgages

In the first quarter of 2026, three of seven residential mortgage loan categories: GSE-eligible, Qualified Mortgage (QM) non-jumbo non-GSE eligible, and Government saw a positive net easing index for lending conditions. An additional two (QM jumbo and non-QM jumbo) recording a neutral reading (i.e., 0). Subprime and non-QM non-jumbo loans continued to experience tighter lending conditions, as evidenced by a negative value, -6.3 and -2.0, respectively.

Four of the seven residential mortgage loan categories (GSE-eligible, QM Jumbo, non-QM jumbo, and Government) reported demand essentially unchanged in the first quarter of 2026. Two categories (non-QM non-jumbo and QM non-jumbo non-GSE eligible) experienced modestly weaker demand. However, the weakest demand continues to be for subprime loans, which has experienced weaker demand for 23 consecutive quarters.

Commercial Real Estate (CRE) Loans

For the CRE loan categories, multifamily registered a net easing index of 0.0, while the net easing index for construction & development loans was -4.8 in the first quarter of 2026. The Fed classifies changes between -5.0% and +5.0% as essentially unchanged.

The net percentage of banks reporting stronger demand was -11.7% for construction & development loans, with a negative number indicating weaker demand. This was a reversal for construction & development from last quarter, which saw stronger demand (+8.9%). For multifamily loans, demand was +3.3% in the first quarter of 2026, which is essentially unchanged according to the Fed’s classification scheme,  as it has been for six consecutive quarters.


This article was originally published by a eyeonhousing.org . Read the Original article here. .
Pin It