Tag

House

Browsing


U.S. house prices continued to rise in the second quarter of 2026, with most states and metropolitan areas recording annual gains. Elevated borrowing costs and affordability constraints remained important headwinds, while limited housing supply continued to support prices in many markets, particularly across parts of the Midwest and Northeast.

According to the Federal Housing Finance Agency’s (FHFA) quarterly purchase-only House Price Index (HPI), national house prices increased 2.1% in the second quarter of 2026 from a year earlier. This was slightly faster than the 1.9% annual gain reported for the first quarter. On a quarter-over-quarter basis, house prices rose 0.3%, moderating from the 0.6% increase in the previous quarter.

The FHFA’s purchase-only HPI tracks average price changes using more than six million repeat-sales transactions involving the same single-family properties. In addition to the national picture, the index provides valuable insight into house price trends across states and metropolitan areas.

At the state level, house price performance remained positive across most of the country. Among the 50 states and the District of Columbia, 47 states recorded year-over-year gains, while four posted declines. Thirty states matched or exceeded the national appreciation rate of 2.1%. Puerto Rico also registered an annual increase.

Alaska led the nation, with house prices rising 8.3% from a year earlier. Vermont followed with a 7.3% gain, while prices increased 5.8% in Hawaii. Illinois and West Virginia each posted gains of approximately 5.6%.

Other strong-performing states included Wisconsin and North Dakota, where prices rose about 4.8%, followed by Connecticut, Rhode Island, and New Jersey. Although the strongest gains were not concentrated in a single region, many Midwest and Northeast states continued to outperform the national average.

At the other end of the spectrum, New Mexico recorded the largest annual decline, with house prices falling 1.2%. Washington declined 0.9%, Colorado fell 0.5%, and California edged down 0.2%.

Several other states, including Oregon, North Carolina, Texas, Mississippi, and Arizona, recorded annual appreciation of less than 1%. These results point to continued softness in several Western and Sun Belt markets, including some areas that experienced rapid price growth during the pandemic-era housing boom.

Quarterly performance was similarly uneven. Hawaii recorded the largest quarter-over-quarter increase at 4.7%, followed by Rhode Island at 2.4%. Conversely, Puerto Rico declined 2.6% from the first quarter, while New Mexico fell 1.7%.

House price performance varied even more widely across the nation’s 100 largest metropolitan areas. Annual house price appreciation ranged from a decline of 3.7% to an increase of 7.7% in the second quarter of 2026.

Overall, 75 of the 100 metro areas posted year-over-year gains, while 22 recorded declines and three remained unchanged. Forty-nine metros matched or exceeded the national appreciation rate of 2.1%.

Elgin, Illinois, recorded the strongest annual appreciation among the 100 largest metros, with prices rising 7.7%. Allentown-Bethlehem-Easton, Pennsylvania–New Jersey, followed with a 7.0% increase.

Chicago, New York, Newark, and Greensboro rounded out the ten strongest annual performers. The rankings indicate continued strength in several Midwest and Northeast markets, where relatively limited housing supply may be helping support prices.

The weakest results were concentrated in portions of the West and Southwest. Everett, Washington, posted the largest annual decline at 3.7%, followed by San Antonio-New Braunfels, Texas, at 3.0%.

Bakersfield-Delano, California, declined 2.6%, while Seattle and San Francisco each fell approximately 2.4%. Tucson, Albuquerque, San Jose-Sunnyvale-Santa Clara, Washington, D.C.–Maryland, and Denver-Aurora-Centennial were also among the ten weakest-performing large metro areas.

Short-term changes sometimes diverged considerably from annual trends. Allentown posted a 4.3% quarterly increase, while Austin rose 3.7% from the first quarter despite a slight year-over-year decline.

By contrast, San Francisco posted a 9.1% quarter-over-quarter decline, the largest quarterly decline among the 100 metros, followed by Tucson at 5.3% and San Jose at 3.6%.

These large quarterly movements highlight the greater volatility in metro-level house price data. While year-over-year changes provide a better indication of underlying price trends, quarterly measures can help identify more recent shifts in local housing market conditions.

Note:

Unless otherwise noted, this blog post uses the quarterly purchase-only House Price Index (HPI), which measures the sales prices of homes that are bought and sold, rather than the broader all-transactions HPI. The purchase-only HPI provides a more precise view of current market conditions. Year-over-year change compares 2026 Q2 with 2025 Q2, while quarter-over-quarter change compares 2026 Q2 with 2026 Q1.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


In this episode of “The House Guest,” host Dorcas Adewole sits down with third-generation builder and real estate developer Matt Panella to discuss how natural disasters are changing the way homes are built. Drawing on his family’s decades of building experience in Central California, Panella, who uses Houzz Pro, shares practical ways to help protect homes from wildfires, highlighting smart upgrades like ember-resistant vents and flame-retardant siding. He also offers advice on vetting contractors, spotting red flags and keeping remodeling projects on track. To wrap up the episode, Panella tackles real-world remodeling questions in a rapid-fire Design Dilemmas segment, covering topics including structural insulated panels, or SIPs, and deck repairs.

Watch or listen to this episode on Houzz, YouTube, Spotify and Apple Podcasts. New episodes drop every Tuesday.

See show notes


This article was originally published by a www.houzz.com . Read the Original article here. .


U.S. house prices continued to rise in the first quarter of 2026, but appreciation slowed markedly from the rapid pace seen during the pandemic-era housing boom. Higher mortgage rates, persistent affordability challenges, and softer demand weighed on price growth nationally. At the same time, local market conditions varied considerably. Some states and metropolitan areas continued to post solid gains, while others experienced flat or declining house prices.

According to the quarterly purchase-only House Price Index1 (HPI) released by the Federal Housing Finance Agency (FHFA), national house prices rose 1.7% in the first quarter of 2026 from a year earlier. This growth rate represented the slowest annual appreciation since the second quarter of 2012, signaling the continued cooling of house price growth after more than a decade of strong gains. On a quarterly basis, house prices increased a modest 0.5% from the fourth quarter of 2025.

The FHFA’s purchase-only HPI tracks average price changes using more than six million repeat-sales transactions involving the same single-family properties. In addition to the national picture, the index provides valuable insight into house price trends across states and metropolitan areas.

At the state level, house price performance remained positive across most of the country in the first quarter of 2026, although appreciation rates varied widely. Annual appreciation ranged from a 2.4% decline to a 16.3% gain.

Puerto Rico recorded the strongest annual appreciation, with house prices surging 16.3% from a year earlier. Among the 50 states and the District of Columbia, Illinois posted the largest gain (7.3%), followed by Alaska (5.5%), Vermont (4.9%), and Connecticut (4.7%). More broadly, many states across the Midwest and Northeast continued to outperform the national average.

At the other end of the spectrum, Colorado recorded the largest annual decline, with house prices falling 2.4% from a year earlier. Texas and the District of Columbia also posted modest declines, while several Western and Sun Belt states saw only limited appreciation. Many of the markets that experienced some of the strongest price growth during 2021–2022 continue to face affordability pressures and softer buyer demand.

Overall, 42 states and Puerto Rico reported annual house price gains. In addition, 31 states and Puerto Rico matched or exceeded the national appreciation rate of 1.7%, underscoring the resilience of many regional housing markets despite challenging financing conditions.

House price performance varied even more widely across metropolitan areas than at the state level. Among the nation’s 100 largest metro areas tracked by FHFA, annual house price appreciation ranged from a decline of 6.9% to an increase of 10.8% in the first quarter of 2026.

The strongest-performing metro areas were concentrated primarily in the Midwest and Northeast, where limited housing supply continued to support price growth. Several metro areas in Pennsylvania, New York, Ohio, and Illinois posted especially strong annual gains, reflecting continued demand amid limited supply.

In contrast, some of the weakest-performing markets were located in Florida, Texas, and parts of the Mountain West. Austin-Round Rock-San Marcos, Texas, recorded the steepest annual price decline among the top 100 metro areas, continuing a correction after several years of exceptionally rapid house price growth. Cape Coral–Fort Myers, Florida, also remained among the nation’s weakest housing markets, extending a trend of price declines amid cooling demand and a gradual rebalancing of market conditions.

Overall, one-third of the 100 largest metro areas posted annual price declines in the first quarter of 2026, while the remaining two-thirds recorded either positive appreciation or essentially flat price growth.

Note:

Unless otherwise noted, this blog post uses the quarterly purchase-only House Price Index (HPI), which measures the sales prices of homes that are bought and sold, rather than the broader all-transactions HPI. The purchase-only HPI provides a more precise view of current market conditions.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


Purple Cherry Architecture & InteriorsSave Photo

Cherry layered in color through textiles, artwork and furnishings she collected over about five years. She made several trips to Schwung, a creative studio in High Point, North Carolina, to select antiques such as the carved door on the left. At Asia Minor Carpet, she purchased Turkish rugs that bring pattern and warmth to the floors.

Keeping the budget balanced required careful choices. “I really wanted Cor-Ten steel for the roof, and my husband really wanted [radiant-heat] floors,” Cherry says. To offset the costs of those elements, she used a commercial-grade large-format floor tile that mimics rustic wood throughout the main level. It was affordable and is durable enough to handle the dogs that fill the house — five regularly and three more when their son visits.

Other savings came from buying light fixtures from Visual Comfort on sale, cutting the number of recessed lights in half, choosing budget-friendly appliances and skipping smart home features. Cherry also found large pieces — such as the cabinet on the right side of the hallway — during a major sale at Restoration Hardware.

“Everything on the floor was 80% off, and with my trade discount it was 90%,” she says. Those savings left room in the budget for the features that mattered most to her and her husband, including the Cor-Ten steel roof and radiant floor heating throughout the home.


This article was originally published by a
www.houzz.com . Read the Original article here. .


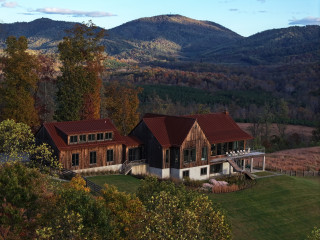
When designing a new lakeside home for repeat clients, Jean Rehkamp Larson of award-winning Minnesota firm Rehkamp Larson Architects sought to capture the grace and symmetry of an old house while ensuring all the comforts of modern living. Collaborating closely with colleague Angela Taffe Wingate, the clients, interior designer Sue Weldon of Harris Weldon Interiors, Streeter Custom Builder, landscape designers Keenan & Sveiven and a team of skilled local artisans, Rehkamp Larson not only achieved that balance but also filled the home with thoughtful, personalized details at every turn.

“Even though it’s a classic house, there are these playful moments overlaid on the classic architecture [that] make it feel couture,” she says. Scroll down to explore the house and uncover the design’s charming surprises.


This article was originally published by a www.houzz.com . Read the Original article here. .


Nationally, house prices continued to rise at a modest pace in the third quarter of 2025, as mentioned in our previous quarterly house prices post. However, this national trend masks significant variation across local markets. While many metro areas continued to see house price appreciation, others experienced notable declines following several years of rapid growth.

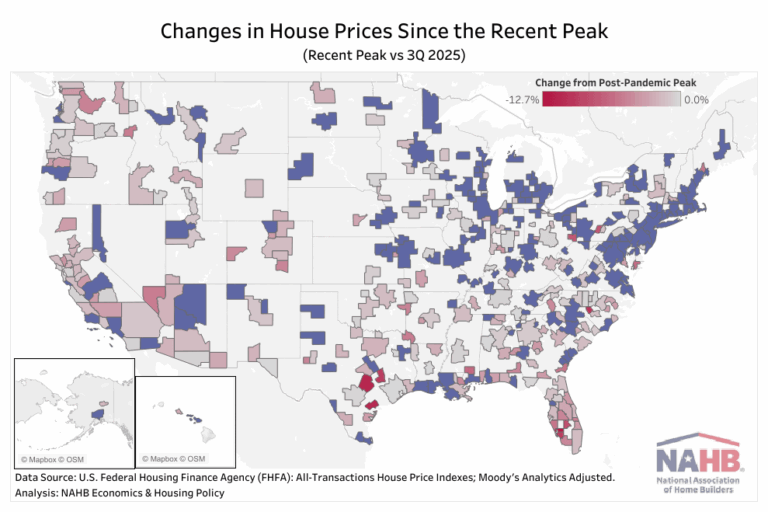
Since the onset of the COVID-19 pandemic, house prices have surged nationwide. Between the first quarter of 2020 and the third quarter of 2025, national house prices climbed 54.9%. Local markets saw broad gains as well, with cumulative appreciation ranging from 18.3% to 88.4%, and 159 metro areas reached their highest recorded house prices in the third quarter of 2025.

Yet despite these increases, more than half of metro areas have now experienced at least some decline from their recent price peak. These declines range from a slight 0.1% dip to a more substantial 12.7% decline, with most of the downward trends beginning in last 2024 or early 2025.

House price declines have been most widespread in the West and South, regions that saw some of the fastest appreciation during the pandemic boom.  Several markets stand out for their significant corrections:

Punta Gorda, FL has experienced the sharpest decline, with prices falling 12.7% since its peak in the fourth quarter of 2022.

Austin–Round Rock–San Marcos, TX, one of the nation’s hottest markets during the pandemic, has seen prices drop 11.3% since reaching a peak in the second quarter of 2022.

Victoria, TX reached its peak more recently in the fourth quarter of 2024 and has since seen prices decline 11.0% over the past three quarters.

In contrast, many metro areas in the Midwest and Northeast have avoided significant price declines. These regions continue to see slower but steady price growth, supported by persistent inventory shortages and solid demand. Their more moderate appreciation during the pandemic has also helped limit the risk of sharp price corrections. Here are some examples (listed in no particular order):

York–Hanover, PA recorded a 6.0% year-over-year increase in house prices in the third quarter of 2025, reflecting stable demand and limited housing supply.

Worcester, MA continues to experience price growth, slowing from the rapid 18.0% growth in the third quarter of 2021 to a still-solid 4.4% year-over-year gain in the third quarter of 2025.

Wausau, WI experienced a robust 9.5% year-over-year increase in home prices, standing out as one of the strongest and most resilient housing markets in the region.

Milwaukee-Waukesha, WI continue to see rising house prices, with growth easing from a peak of 16.7% growth in the second quarter of 2022 to a more sustainable 5.6% year-over-year increase in the third quarter of 2025.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


Rachel Madden InteriorsSave Photo
Built-in white oak bookcases flank a gas fireplace, above which hangs a landscape painting that Madden bought at an antique store for $85.

“It’s an amazing find,” she says. “It had a big tear, and it was just so beautiful that I decided to repair it. So I found an art restoration company that restores art at the Crocker Art Museum [in nearby Sacramento] and [they] restored that for me.” They also identified the painting as probably Scottish, from the mid-19th century.

The painting was Madden’s jumping-off point for the decorating scheme. “Once I picked the art, my color palette was pretty much set, and then I picked the pillows, the rug and I even reupholstered the living room chairs,” she says. The thick wool green rug and chairs’ performance fabric, she adds, are good options for withstanding wear and tear from kids and pets.

The art also inspired her to scour antique fairs for similarly old-world, vintage pieces, she says, including the dictionaries on the bookshelves, the pitcher on the mantel and the scalloped bowl on the coffee table.

Rug: Armadillo; chair upholstery: Rose Tarlow


This article was originally published by a
www.houzz.com . Read the Original article here. .


House price growth slowed in the first quarter of 2025, partly due to a decline in demand and an increase in supply. Persistent high mortgage rates and increased inventory combined to ease upward pressure on house prices. These factors signaled a cooling market, following rapid gains seen in previous years.

Nationally, according to the quarterly all-transactions House Price Index (HPI) released by the Federal Housing Finance Agency (FHFA), U.S. house prices rose 4.7% in the first quarter of 2025, compared to the first quarter of 2024. This year-over-year (YoY) rate was lower than the previous quarter’s rate of 5.5%. The FHFA’s all-transactions HPI tracks average price changes based on repeat sales and refinancings of the same single-family properties. It offers insights not only at the national level but also across states and metropolitan areas.

Between the first quarter of 2024 and the first quarter of 2025, all 50 states and the District of Columbia experienced positive house price appreciation, ranging from 1.0% to 8.4%. Connecticut and Rhode Island topped the house price appreciation list with an 8.4% gain each, followed by New Jersey with a 7.8% gain. On the opposite end, Louisiana recorded the lowest house price appreciation at 1.0%. Out of all 50 states and the District of Columbia, 26 states exceeded the national YoY growth rate of 4.7%. However, on a quarterly basis, home price appreciation slowed in 39 states compared to the fourth quarter of 2024, highlighting a broad-based deceleration in the housing market.

House price growth widely varied across U.S. metro areas year-over-year, ranging from -7.0% to +23.0%. Rome, GA recorded the largest decline in house prices, whereas Johnstown, PA posted the highest increase over the previous four quarters. In the first quarter of 2025, 28 metro areas, in reddish color on the map above, experienced negative house price appreciation. Meanwhile, 356 metro areas experienced price increases.

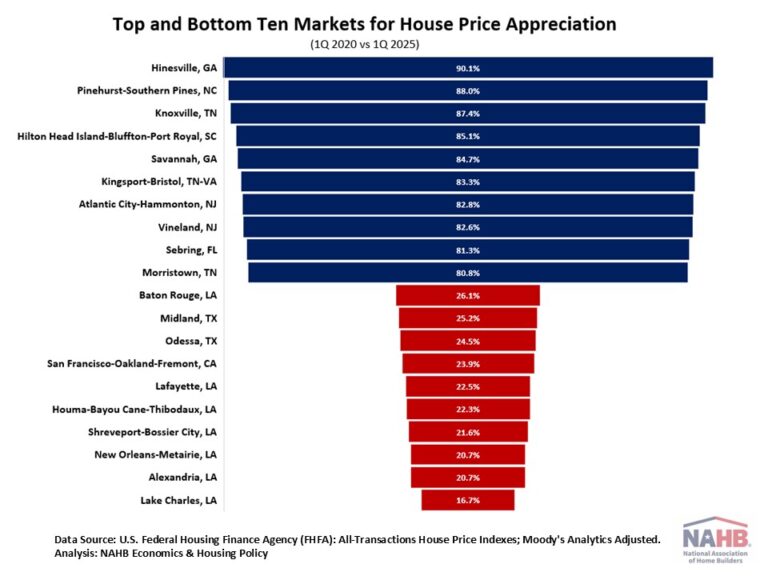
Since the onset of the COVID-19 pandemic, house prices have surged nationally. Between the first quarter of 2020 and the first quarter of 2025, house prices rose by 54.9% nationwide. More than half of metro areas outpaced this national price growth rate of 54.9%.

The table below highlights the top ten and bottom ten markets for house price appreciation during this five-year period. Among all the metro areas, house price appreciation ranged from 16.7% to 90.1%. Hinesville, GA led the nation with the highest house price appreciation. Lake Charles, LA recorded the lowest appreciation, marking its fourth consecutive quarter at the bottom.

Discover more from Eye On Housing

Subscribe to get the latest posts sent to your email.


This article was originally published by a eyeonhousing.org . Read the Original article here. .

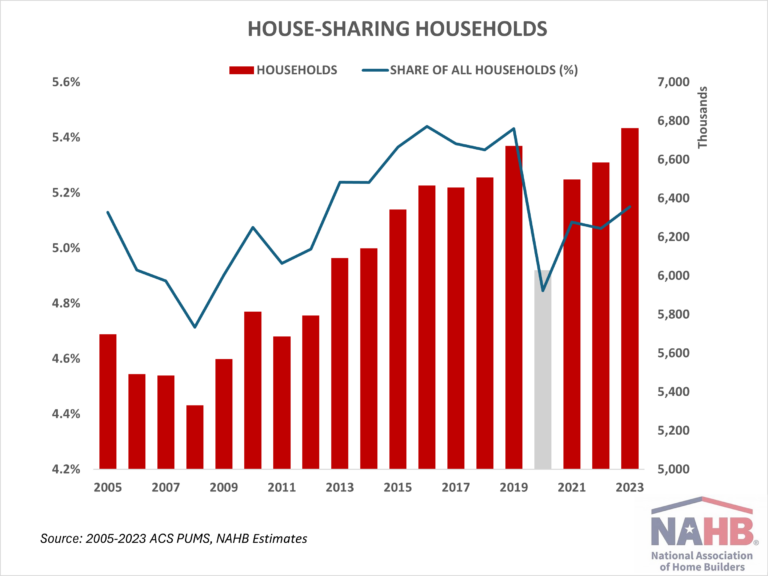
A record-high 6.8 million households shared their housing with unrelated housemates, roommates or boarders in 2023. While college-age and young adults make up the largest subset of house sharers (close to 41%), this type of living arrangement is gaining popularity among older householders fastest, with the 55+ segment accounting for 30% of all house-sharing households in 2023.

The number of households sharing housing with nonrelatives had been rising steadily since the 2008 housing crash until the COVID-19 pandemic interrupted the upward trend. During that period, the count of households with at least one unrelated member increased from 5.3 million in 2008 to over 6.7 million in 2019. At the same time, the percentage of house-sharing households grew from 4.7% to 5.4%.

The pandemic dramatically redefined living arrangement preferences. Reflecting the shift towards more spacious, lower-density independent living, the number and percentage of house-sharers collapsed in 2020 (although the data collection issues during the lockdown stages of the COVID-19 pandemic make the 2020 estimates less reliable).  While the percentage of households sharing housing has climbed since the pandemic lows, it remains below the 2019 peak. However, the count of house-sharing households in the U.S. is now at a new record-high point. This is largely reflective of a faster household formation rate since the end of the pandemic, as well as the growing popularity of home sharing arrangements.

Young Adults (25-34)

Young adults in the 25-34 age group make up the largest (close to 1.6 million, or 23%) cohort of households that share housing with unrelated housemates. Over the last two decades, amid the rising housing burdens and cost of living, house sharing became a way for young adults to afford to leave parental homes. From 2005 to 2017, as the headship rates for this age group declined precipitously and millions of young adults dropped out of the housing market, house sharing became more common among those who managed to stay out of parental homes. In 2017, when 25 to 34-year-old adults registered record low headship rates, one in eleven householders in this age group shared housing with unrelated housemates. By 2023, when the headship rates rebounded, the share of 25 to 34-year-old house-sharing householders dropped to 7.9%, on par with the 2005 reading.

While it is tempting to assume that the high prevalence of house sharing among young adults reflects a rise in unmarried partnerships, these are not considered house-sharers in this analysis.  Unmarried partners tend to function as a unit similar to a married couple, dividing their economic, social and financial responsibilities, and not just those related to house-sharing. To differentiate between these different demographic trends, unmarried partnerships are counted as independent households for the purposes of this analysis.

College-Age Adults (18-24)

College-age adults make up the second largest group of house-sharing householders (1.2 million, or 17%). While the total counts are substantial, they represent a decline since 2005 when 1.3 million 18 to 24-year-old householders shared housing with unrelated roommates, accounting for 22% of house-sharing households.  The lower counts of house sharers in this age group reflect, among other factors, the rising share of college-age adults living with parents, declining rates of college attendance in recent years, as well as slower youth population growth. Nevertheless, the youngest householders remain the age group that is most likely to share housing. As of 2023, over one in five leaseholders/homeowners in the 18-24 age group shared housing with unrelated roommates or housemates.

Older Adults 55+

Older adults ages 55 and over registered the most substantial gains in house-sharing arrangements since the housing boom of the mid-2000s[1]. The number of households lead by 55 to 64-year-old adults that shared housing almost doubled since 2005 to 1 million. Their segment increased from 9% of house-sharing households in 2005 to 14% in 2023. At the same time, the number of house-sharers among 65+ householders increased 2.7 times. These oldest householders now account for over a million, or 15% of all house-sharing households, more than doubling their share of 6.8% in 2005.

Partially, the surge in the number of older households sharing housing with nonrelatives simply reflects the aging U.S. population with numerous baby boomers filling the ranks of 55+ households. Partially, it captures the changing preferences, as the older householders are now more likely to live with unrelated members. In 2005, 3% of 55 to 64-year-old householders shared housing with nonrelatives. This share increased to 3.6% in 2013 and continued its climb to 4.1% in 2023. The increase in the percentage of 65+ householders sharing housing was similarly persistent, rising from 1.7% in 2005, to 2.3% in 2013, and climbing further to reach 2.8% in 2023.

Unlike the rates of house-sharing among younger adults, the rates for the 55+ age group appear less cyclical. While still largely unconventional among 55 and older householders, house sharing is on the rise, potentially offering a cost-effective option for older adults to stay in place as they age.

Discover more from Eye On Housing

Subscribe to get the latest posts sent to your email.


This article was originally published by a eyeonhousing.org . Read the Original article here. .
Pin It