Tag

Eye

Browsing


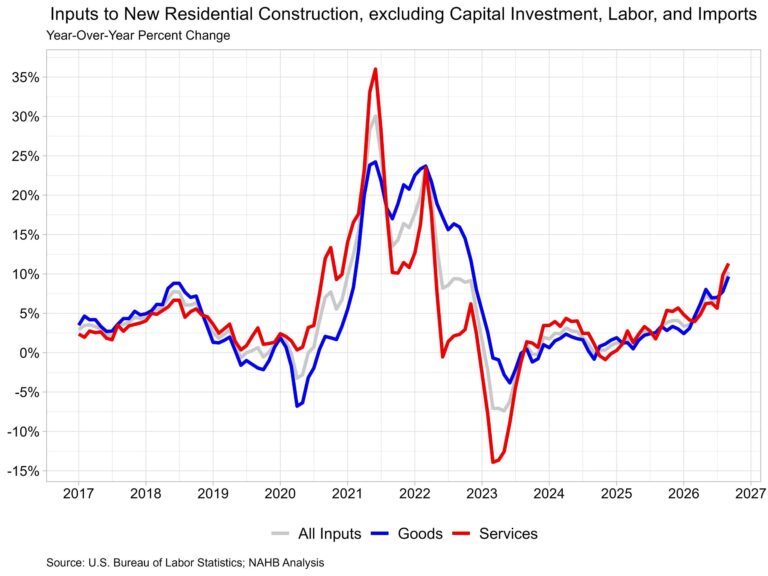
The Producer Price Index for final demand was up 1.3% in September, after rising 0.5% in August. Compared to a year ago, final demand prices were up 6.3%. The price of goods used in new residential construction (including energy) was up 1.8% over the month and up 9.7% from last year, while the price of services was up 2.2% over the month and up 11.3% from last year. Combining goods and services, the price index for inputs to new residential construction was up 2.0% in September and 10.3% higher than last year.

Input Goods

The goods component has a larger importance to the inputs to residential construction price index, representing around 60% of the total. On a monthly basis, the price of input goods to new residential construction was up 1.8% in September after rising 0.9% in August.

The input goods to residential construction index can be further broken down into two separate components, one measuring energy inputs with the other measuring remaining goods. The latter of these two components simply represents building materials used in residential construction, which makes up around 93% of the goods index.

Energy input prices rose 13.0% in September and were 64.1% higher than a year ago. Building material prices were up 0.4% in September and up 5.5% compared to one year ago, the highest level since 8.0% in December 2022.

Price increases for energy products outpaced other materials. No. 2 diesel fuel prices were up 24.2% over the month and 115.2% higher than a year ago. Unleaded regular gasoline prices rose 13.0% over the month and were 66.1% higher than a year ago. Outside of energy products, particleboard and fiberboard prices rose 3.5% over the month and were up 7.8%, meanwhile prices for mineral wool (f[RD2.1]or insulation) rose 2.8% over the month and were up 1.6% from a year ago. Softwood veneer and plywood prices were up 2.7% over the month and 15.9% higher than a year ago.

Input Services

Prices for service inputs to residential construction rose 2.2% in September. On a year-over-year basis, service input prices were up 11.3%, the highest since April 2022 when service prices rose 17.7% year-over-year. The price index for service inputs to residential construction can be broken out into three separate components: a trade services component, a transportation and warehousing services component, and a services excluding trade, transportation, and warehousing component (other services).

The most significant component is trade services (around 60%), followed by other services (around 29%), and finally transportation and warehousing services (around 11%). The largest component, trade services, was up 14.0% from a year ago. The price of transportation and warehousing services has risen 19.3% over the year, while prices for other services were up 3.1% over the year.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


A previous post examined the median age of the overall construction workforce and how it compares with workers in all industries. This analysis takes a closer look at workers in construction trades, where the median ages differ considerably across occupations.

According to NAHB analysis of the 2024 American Community Survey (PUMS data), the median age of construction trades workers is 40, two years younger than the median age of all workers employed in the construction industry. However, median age varies substantially across individual construction trades. Construction and building inspectors and plasterers and stucco masons share the highest median age at 46. Highway maintenance workers follow closely, with a median age of 45, while carpet, floor and tile installers and finishers have a median age of 44. At the younger end of the spectrum, roofers have a median age of 35, followed by pipelayers at 34, and helpers in construction trades at 32. With a median age of just 27, solar photovoltaic installers represent the youngest occupational group among the construction trades.

This wide variation in the median age shows that the workforce aging is not uniform across construction trades. Of the 27 construction trades analyzed, 12 have a median age above the overall median of 40 for construction trades workers. While some occupations have a relatively young workforce, others have a larger concentration of older workers.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


Labor shortages in the home building industry are becoming more widespread, according to recent results from the NAHB/Well Fargo Housing Market Index (HMI) survey.

The September 2026 HMI survey asked builders about shortages in 16 specific trades. The percentage of builders reporting a shortage (either serious or some) of labor they employ directly ranged from a low of 33% for excavators and building maintenance managers to a high of 58% for workers who perform finished carpentry.

The shortage percentages were generally up from the last time NAHB conducted the survey, in April of 2025. The shortage percentages for plumbers and HVAC workers were unchanged at 45% and 43%, respectively, but were up at least slightly for each of the other 14 listed trades. The three trades seeing the largest spikes in shortages are framing crews (up 9 percentage points to 57%), landscaping workers (up 7 pp to 39%), and roofers (up 6 pp to 36%). Averaged across the 9 trades NAHB has been covering in a consistent fashion since 1996, the shortage percentage was 47% in September 2026—up from 42% in April 2025.

At 47%, the current 9-trade shortage percentage is now higher than it had been at any time during the boom period of 2004-2006, when total housing starts were consistently over 1.8 million annually. In contrast, starts in August of 2026 came in at a seasonally adjusted annual rate of under 1.3 million.

After peaking during the COVID pandemic, the reported shortages of residential construction labor declined consistently between 2022 and 2025, before rising back up in the latest survey.

The recent uptick in the percentage of home builders reporting labor shortages is not surprising, given that employment in residential construction has been trending downward, as home building competes for labor with other segments of the construction industry—particularly data centers. Immigration enforcement is also heightening worker fears and further contributing to the shortage.

Along with the shortages, home builders also reported rising labor costs in the September HMI survey. The median increase in the cost of labor for the same home over the previous 12 months was 4.2%.

In the typical case, a substantial share of the physical work required to build a home is performed not by laborers employed directly by the builders, but by subcontractors. As a 2020 NAHB study showed, builders on average use two dozen different subcontractors and subcontract out 84% of their total construction costs to build a single-family home.

NAHB’s HMI survey asks home builders a separate set of questions about shortages of subcontractors. From 2012 through 2020, as home building began the long process of recovery from the Great Recession, shortages of subcontractors were consistently more widespread than shortages of labor directly employed by builders. However, that difference has vanished, and the graph for subcontractor shortages now closely mirrors the equivalent graph for directly employed labor. In fact, more than 50% of builders report shortages of subcontractors and direct laborers in the same five trades: framers, rough and finished carpenters, bricklayers, and concrete workers.

For more detail—including the complete history for every question in the HMI labor availability survey going back to 1996—please consult the September 2026 HMI Special Questions report.


This article was originally published by a eyeonhousing.org . Read the Original article here. .
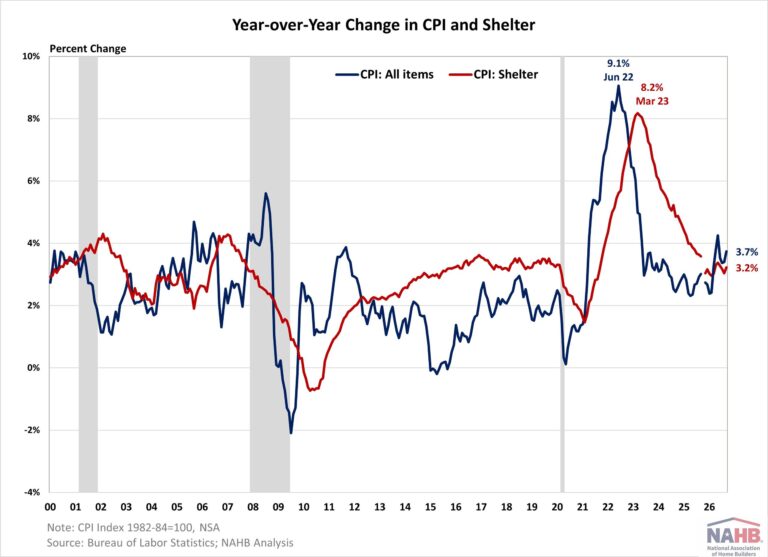

Higher energy prices pushed inflation to a four-month high in September, keeping pressure on the Fed as inflation has remained above its 2% target for more than five years. Gasoline prices remained the largest driver of headline inflation, accounting for over half of the monthly increase.

On a non-seasonally adjusted basis, the Consumer Price Index (CPI) rose by 3.7% in September from a year ago, following a 3.4% increase last month, according to the BLS latest report. The “core” CPI, excluding the volatile food and energy components, increased by 2.6% over the past twelve months, following a 2.4% increase in August. The housing shelter index, which makes up a large portion of the core CPI, rose 3.2% over the year, following a 3.0% increase last month. The component index for food rose by 2.5% over the year, and the energy component index increased by 20.4%. Meanwhile, technology prices continued to climb amid strong AI demand, with price indexes for computers and software increasing 9.7% and 28.4% from a year ago.

On a monthly basis, the CPI rose by 0.6% in September (seasonally adjusted), while the “core” CPI increased by 0.3%.

The price index for a broad set of energy sources increased by 5.2% in September, as decline in natural gas (-0.3%) was offset by increases in fuel oil (+15.3%), gasoline (+9.1%) and electricity (+0.2%). Meanwhile, the food at home index fell by 0.1% and the food away from home index rose by 0.2 in September.

Outside of energy, other top contributors that rose in September included indexes for recreation (+0.5%), used cars and trucks (+0.7%), education (+0.6%), airline fares (+1.2%), medical care (+0.1%) and apparel (+0.3%). Meanwhile, the index for communication (-0.2%) was among the major indexes that decreased over the month.

The index for shelter, which makes up more than 40% of the “core” CPI, rose by 0.4% in September, following a 0.3% increase last month. The index for owners’ equivalent rent (OER) and rent of primary residence (RPR) increased by 0.3% and 0.2% over the month.

NAHB constructs a “real” rent index to indicate whether inflation in rents is faster or slower than core inflation. It provides insight into the supply and demand conditions for rental housing. When inflation in rents is rising faster than core inflation, the real rent index rises and vice versa. The real rent index is calculated by dividing the price index for rent by the core CPI (to exclude the volatile food and energy components). In September, the Real Rent Index fell by 0.1%.


This article was originally published by a eyeonhousing.org . Read the Original article here. .
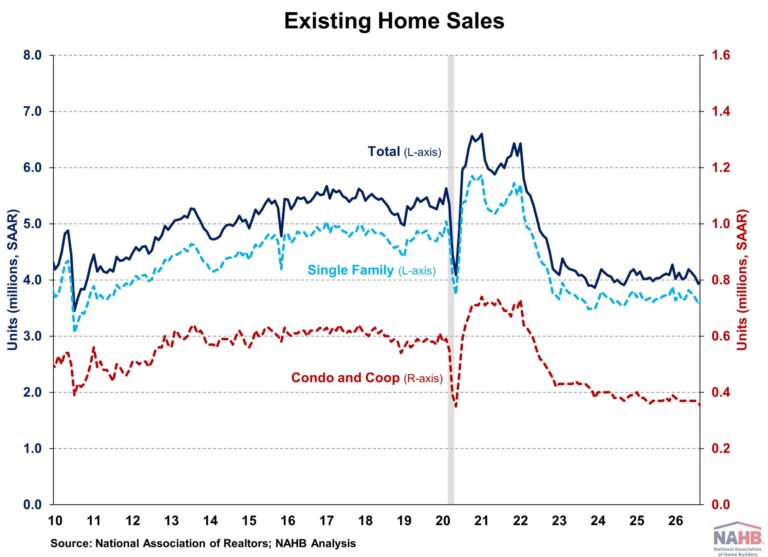

Existing home sales rose after three months of declines as improved inventory gave buyers more negotiating power. As buyers wait for rate relief, homes are sitting on the market longer and for-sale inventory reached the highest level in over a decade. Despite the increase, August and September sales remained the slowest this year. With mortgage rates back above 7% since mid-September, home sales are likely to stay sluggish over the next few months.

Total existing home sales, including single-family homes, townhomes, condominiums, and co-ops, rose 1.5% to a seasonally adjusted annual rate of 3.99 million in September, according to the National Association of Realtors (NAR). This marked the second-lowest level since July 2025 and only the third time since October 2024 that sales dropped below 4.0 million. On a year-over-year basis, sales were 2.2% lower than a year ago.

The existing home inventory level was 1.60 million units in September, up 1.9% from August and 4.6% from a year ago. At the current sales rate, September unsold inventory sits at a 4.8-months’ supply, unchanged from last month but up from 4.5-months a year ago. This matched last month and was the highest months’ supply since November 2015. Inventory between 4.5 to 6 months’ supply is generally considered a balanced market.

Homes stayed on the market for a median of 33 days in September, up from 31 days in the previous month but unchanged from September 2025.

The first-time buyer share was 31% in September. The share was up from 30% both in August and a year ago.

The September all-cash sales share was 27% of transactions, unchanged from last month and down from 30% in September 2025. All-cash buyers are less affected by changes in interest rates.

The September median sales price of all existing homes was $417,500, up 1.3% from last year. This marks the 39th consecutive month of year-over-year increases. The median condominium/co-op price in September was up 1.2% from a year ago at $363,700. Recent gains for home inventory will put downward pressure on resale home prices in most markets in 2026. Existing home sales in September were mixed across the four major regions. Sales rose in the South (2.8%) and West (2.8%), while they fell in the Northeast (-2.1%). Sales in the Midwest were unchanged. On a year-over-year basis, sales decreased in all four regions, ranging from 0.5% in the South to 2.1% in the Midwest.

The Pending Home Sales Index (PHSI) is a forward-looking indicator based on signed contracts. The PHSI rose from 71.0 to 71.2 in August. On a year-over-year basis, pending sales were 4.7% lower than a year ago according to the National Association of Realtors’ data.


This article was originally published by a eyeonhousing.org . Read the Original article here. .

The median age of construction workers is 42, one year older than a typical worker in the national labor force, according to NAHB analysis of the latest 2024 American Community Survey (ACS) data. At the same time, younger workers are becoming a growing part of the construction workforce. Despite some improvements since the peak of the skilled labor shortage in 2021, attracting and retaining skilled labor remains the primary long-term goal for the construction industry.

The median age of construction industry workers varies across states. The color coding in the map above tracks the median age of people working in the construction industry.  The state with the oldest median age (47 years old) is Rhode Island, followed by Connecticut, Illinois, New Hampshire and New Jersey, where the median age of construction workers is 44. Construction workers are younger on average in the central part of the nation. For example, half of all construction workers in Utah and Idaho are under 39.

The second data series mapped above is the difference between the median age of construction workers in each state and the median age of all industries. These estimates are reported as the numbers printed on each state. A positive number indicates that on average, construction workers are older than a typical worker in the state labor force. Rhode Island is the state where the median age of construction workers is 7 years higher than the overall median. On the other hand, a negative number indicates construction workers are, in general, younger than the state labor force.  In Vermont, the median age of construction workers is 4 years younger than the overall median.

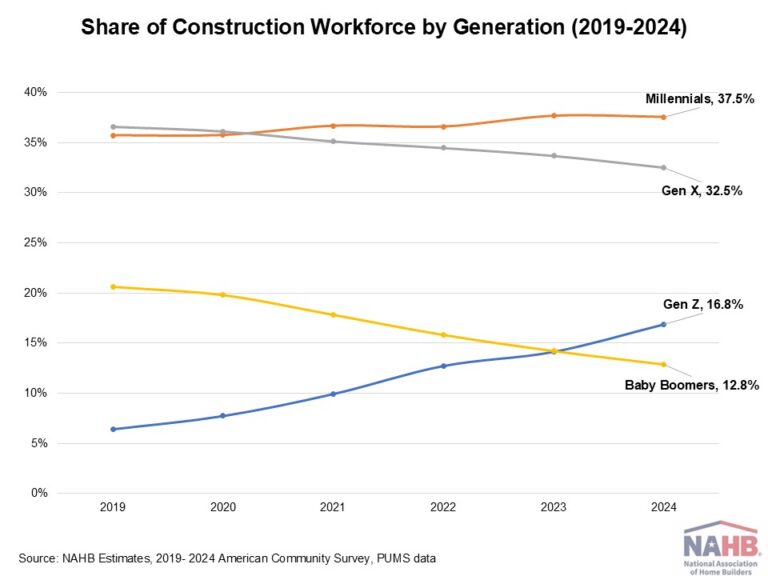
Generational shifts are reshaping the construction labor force. The share of Gen Z in construction workforce has grown rapidly, increasing from 6.4% in 2019 to 16.8% in 2024. This considerable increase over five years reflects a growing pipeline of younger workers. The Millennial generation share also rose from 35.7% to 37.5% over the same period. In contrast, the Gen X share declined from 36.6% to 32.5%, while the Baby Boomer’s share fell sharply from 20.6% to 12.8% as more retired. This shift suggests that Gen Z and Millennial workers are becoming an increasingly important part of the construction workforce. 

Compared with the workforce across all industries, construction has a relatively smaller share of younger workers, but a larger proportion of workers in their prime-working age. In 2024, only about 10.7% of construction workers were under age 25, compared with 13.7% of workers across all industries. Around 67.3% of the construction workforce were in the prime working years of 25-54, compared to 63.4% in the overall workforce.

Construction workers were especially concentrated in the 35 to 54 age group. Workers ages 35 to 44 accounted for 24.5% of the construction workforce, compared with 22.1% of workers across all industries; meanwhile, workers ages 45 to 54 represented 21.2% of construction workers, compared with 19.3% overall. At the same time, workers 55 and older made up 22% of the construction workforce. As these older workers approach retirement, attracting more skilled labor remains the primary long-term goal for the construction industry.


This article was originally published by a eyeonhousing.org . Read the Original article here. .

Only 16% of NAHB builder members reported building age-restricted housing for people age 55 or older, according to 2025 Member Census. Even though it is down one percentage point from the previous year, this share has remained within a narrow band (15%-17%) since this question was introduced in the survey in 2009.

The likelihood of building age-restricted housing generally increases with the size of the company. Among builders with fewer than 100 starts in 2025, less than 20% build this type of housing, compared to 36% among those with 100+ starts. Additionally, there is some variation by the builder’s primary business activity. Fifty-two percent of those who manufacture modular/panelized/log home build age-restricted housing, compared to 17% of single-family builders and 29% of multifamily builders. In 2025, 47,000 housing units were started in age-restricted communities, which is up over 9% from the previous year.

In 20231, there were 25,849,000 households with a person 55 or over. Of these, 15% reported living in age-restricted communities (a record high since the inception of the series in 2015) and another 23% in communities where most neighbors are 55+.

The median age of homes for households with a person 55 or over in 2023 is 37.8 years, up 1.5 years from 2021 and nearly five years older than in 2015. When analyzing senior citizen communities by year home was built, 3.4% were built in 2020 or later while 25.6% were built before 1970. When compared to the overall housing stock (median age: 42 years), the median age for homes within senior citizen communities is approximately four years lower, mainly due to a lower share of homes built before 1970 and not necessarily due to a large increase in recent production (i.e., built 2020 or later).

For more details about NAHB builder members, please visit housingeconomics.com or click here for the full article.

This is the most recent survey results as of October 12, 2026.


This article was originally published by a
eyeonhousing.org . Read the Original article here. .

The share of new single-family homes built with individual wells and septic systems increased in 2025 compared to the previous year. According to NAHB’s analysis of the Census Bureau’s Survey of Construction (SOC), approximately 10% of single-family homes started in 2025 were served by individual (private) wells, and 17% relied on individual septic systems.

Nationally, most new homes were connected to public water systems, which include community or shared supplies/wells. The remaining 10% were built with private wells, increasing one percentage point from the previous year.

The share of private wells significantly differed by Census division.  In New England, where median lot size is double the national median, 42% of new single-family homes relied on private wells, making it the division with the highest rate in the nation. The East North Central division followed with 26%, while the Middle Atlantic stood at 15%. The South Atlantic region also exceeded the national average, with 13% of new homes using private wells. In stark contrast, private wells were uncommon in the East South Central, West South Central and Pacific divisions, where they accounted for one to two percent of new homes started.

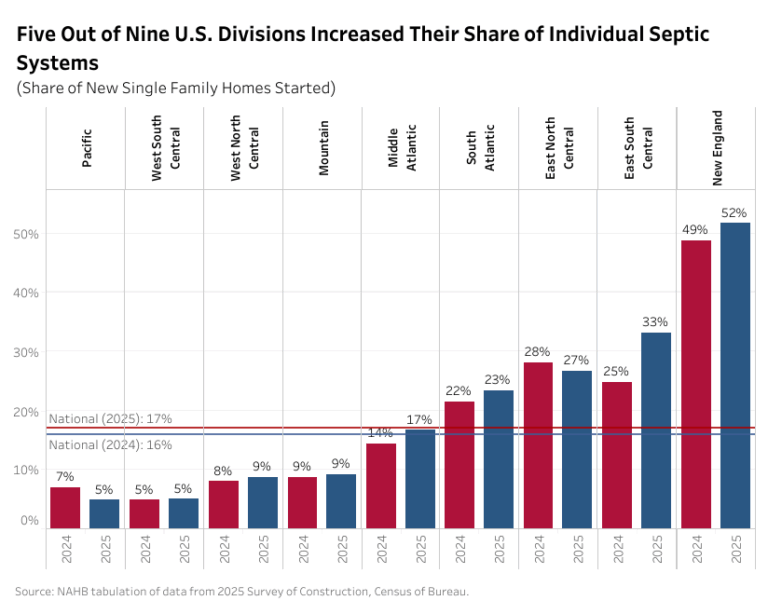
For sewage disposal, 83% of new single-family homes in 2025 were connected to public sewer systems, which include community or shared sewage/septic systems. The remaining 17% utilized individual septic systems, one percentage point higher than the previous year. As with private wells, the usage of individual septic systems varied significantly by region.

New England led the nation with 52% of new homes using individual septic systems.  The East South Central (33%), East North Central (27%), and South Atlantic (23%) divisions also reported shares above the national average. In contrast, lower usage was recorded in the Mountain (9%) and West North Central (9%) divisions, while the Pacific and West South Central divisions had the smallest shares, at 5%, respectively.

Compared to 2024, five of the nine Census divisions experienced an increase in the use of individual septic systems with four of the divisions falling below the national average of 17%. East South Central in particular saw a large increase of 8-percentage points as it surpassed East North Central as the division with the second largest share of individual septic systems. New England remained the largest shareholder with 52%, a 3-percentage point increase. Only Pacific and East North Central saw declines in shares of 2- and 1-percentage points, respectively.


This article was originally published by a eyeonhousing.org . Read the Original article here. .

In the third quarter of 2026, the NAHB Remodeling Market Index (RMI) posted a reading of 62, up one point compared to the previous quarter. The RMI has remained within a narrow band between 59 and 70 for the past four years. Remodeler sentiment remains the standout sector within the housing industry, when compared to its single-family and multifamily counterparts.

Despite sentiment remaining stable, remodelers report that economic uncertainty is making some potential customers hesitant to move forward with projects. Labor shortages, exacerbated by immigration enforcement and competition from data center construction, are extending the time it takes to complete projects. Nevertheless, remodeling is gaining share in the overall construction market, as it is somewhat less sensitive than new construction to the current elevated interest rates. NAHB’s projection for remodeling activity will remain stable in 2026 and grow slightly in 2027, which is consistent with today’s reading.

The RMI is based on a survey that asks remodelers to rate various aspects of the residential remodeling market “good”, “fair” or “poor.” Responses from each question are converted to an index that lies on a scale from 0 to 100. An index number above 50 indicates a higher proportion of respondents view conditions as good rather than poor.

Current Conditions

The Remodeling Market Index (RMI) is an average of two major component indices: the Current Conditions Index and the Future Indicators Index. 

The Current Conditions Index is an average of three components: the current market for large remodeling projects ($50,000 or more), moderately-sized projects ($20,000 to $49,999), and small projects (under $20,000).

In the third quarter of 2026, the Current Conditions Index averaged 70, which remained unchanged for the third consecutive quarter. The component measuring large remodeling projects increased two points to 66, while the small projects component inched down one point to 73, and the moderately-sized projects component decreased two points to 71.

Future Indicators

The Future Indicators Index is an average of two components: the current rate at which leads and inquiries are coming in, and the current backlog of remodeling projects. 

In the third quarter of 2026, the Future Indicators Index averaged 54, up two points from the previous quarter. Both the component measuring backlog of remodeling jobs and the current rate at which leads and inquiries increased two points to 56 and 53, respectively, for the quarter.

For the full set of RMI tables, including regional indices and a complete history for each RMI component, please visit NAHB’s RMI web page.


This article was originally published by a eyeonhousing.org . Read the Original article here. .
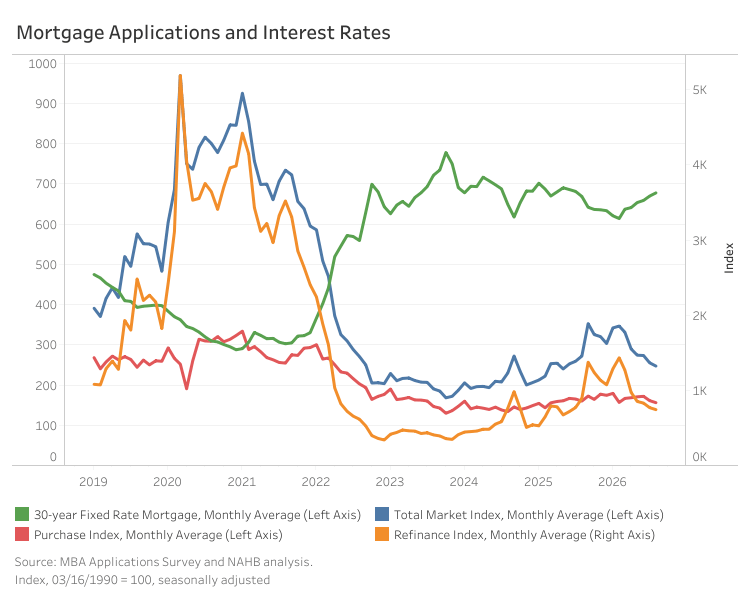

Mortgage application activity declined as the 30-year fixed mortgage rate rose sharply. The Mortgage Bankers Association’s (MBA) Market Composite Index, a measure of total mortgage application volume, decreased 7.7% month-over-month in September on a seasonally adjusted basis. Compared to a year ago, total mortgage applications were lower by 35.4%. Higher fixed mortgage rates contributed to a rise in applications for adjustable-rate mortgages (ARMs), which increased 7.6% month-over-month. As a result, the ARMs share of total applications increased to 9.3%.

The monthly decline occurred in both major components. Purchase applications decreased 1.3% from August, while refinance applications declined 16.5%. Relative to September 2025, purchase and refinance activity were also down 11.6% and 54.7%, respectively.

Market activity continued to slow as the average contract rate for a 30-year fixed-rate mortgage rose significantly in September. The mortgage rate jumped 28 basis points (bps) to 7.1% and was 64 bps higher than a year ago.

The average contract interest rate for 5/1 ARMs was 6.2% in September. The lower initial interest rate and monthly payments made ARMS relatively more attractive to borrowers, contributing to a 7.6% increase in ARMs applications during the month. Nonetheless, compared to a year ago, ARMs applications remained 40.1% lower. As a result, the ARMs share increased 1.4 percentage points to 9.3%. Meanwhile, applications for fixed-rate mortgages declined 9.1% month-over-month and 34.8% year-over-year.

Interestingly, the overall loan size increased 1.4% to $380,500. The increase was driven primarily by purchase loans, for which the average loan size increased 1.1% to $445,800. Meanwhile, the average refinance loan size edged down 1.2% to $279,500, while the average ARMs loan size declined 2.9% to $896,800.


This article was originally published by a eyeonhousing.org . Read the Original article here. .
Pin It