Tag

Building

Browsing


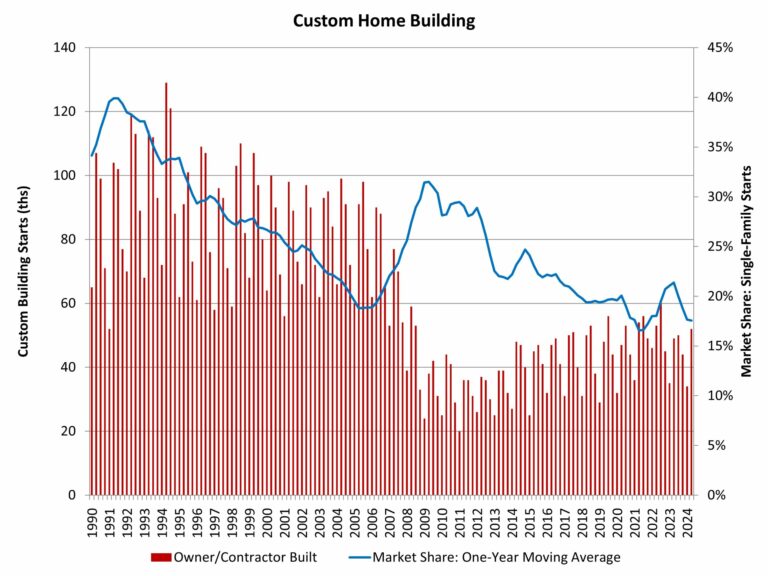
NAHB’s analysis of Census Data from the Quarterly Starts and Completions by Purpose and Design survey indicates gains for custom home building after some recent slowing. Custom home building typically involves home buyers less sensitive to changes for interest rates.

There were 52,000 total custom building starts during the second quarter of 2024. This marks an almost 6% increase compared to the second quarter of 2023 and the best reading since the third quarter of 2022. Over the last four quarters, custom housing starts totaled 180,000 homes, a 5% decline compared to the prior four quarter total (189,000) due to weakness in prior quarters.

After share declines due to a rise in spec building in the wake of the pandemic, the market share for custom homes increased until 2023 and then entered a period of retrenchment. As measured on a one-year moving average, the market share of custom home building, in terms of total single-family starts, has fallen back to just under 18%. This is down from a prior cycle peak of 31.5% set during the second quarter of 2009 and a 21% local peak rate at the beginning of 2023.

Note that this definition of custom home building does not include homes intended for sale, so the analysis in this post uses a narrow definition of the sector. It represents home construction undertaken on a contract basis for which the builder does not hold tax basis in the structure during construction.

Discover more from Eye On Housing

Subscribe to get the latest posts sent to your email.


This article was originally published by a eyeonhousing.org . Read the Original article here. .
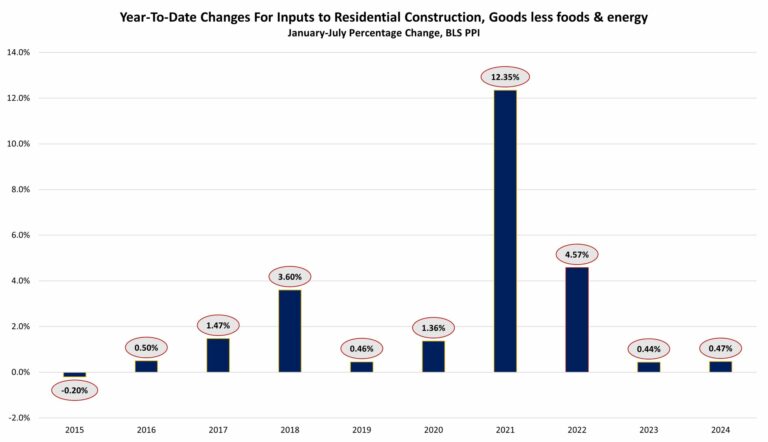

Inputs to residential construction, goods less foods and energy, decreased 0.04% over July according to the most recent Producer Price Index (PPI) report published by the U.S. Bureau of Labor Statistics (BLS). The index for inputs to residential construction, goods less food and energy, represents building materials used in residential construction. Compared to a year ago, the index is up 2.01% in July, marking the sixth straight month of above 2% growth.

Just past the midpoint of 2024, the year-to-date (YTD) increase in the index is at 0.47%. This is slightly higher yet similar to the YTD growth rate for 2023, which was 0.44%.

The seasonally adjusted PPI for final demand goods increased 0.62% in July, after decreasing a revised 0.36% in June. In July, the PPI for final demand energy increased 1.90%, final demand food also rose 0.61% and final demand goods, less food and energy, rose 0.24%. The BLS producer price indices measure the average change in selling prices that domestic producers receive for their output.

The seasonally adjusted PPI for softwood lumber fell 1.04% in July after rising 3.29% in June. Softwood lumber prices were 13.12% lower than July 2023.

The non-seasonally adjusted PPI for gypsum building materials increased 0.08% in July after no increase in June. Compared to last year, the index was up 4.25%, the highest yearly increase since April 2023 when the index was up 12.14%.

The seasonally adjusted PPI for ready-mix concrete rose 0.03% in July after falling 0.15% in June. Monthly growth in prices for read-mix concrete has been relatively flat for four consecutive months after prices peaked in March. Over the year, ready-mix concrete prices were 5.05% higher than July 2023.

The non-seasonally adjusted PPI for steel mill products fell for the second straight month, down 3.29% in July. Steel mill product prices are 13.99% lower than last year. Overall, steel mill product prices have fallen 36.99% since peaking back December of 2021.

The non-seasonally adjusted special commodity grouping PPI for copper rose 0.56% in July after falling 2.79% in June. Over the year, the index was up 14.26%. This special commodity grouping of copper includes the following commodities: copper and nickel ores, copper cathode and refined copper, copper base scrap, secondary copper (alloyed and unalloyed), copper and brass mill shapes, copper wire and cable, and copper base castings (excluding die-castings).

Discover more from Eye On Housing

Subscribe to get the latest posts sent to your email.


This article was originally published by a eyeonhousing.org . Read the Original article here. .
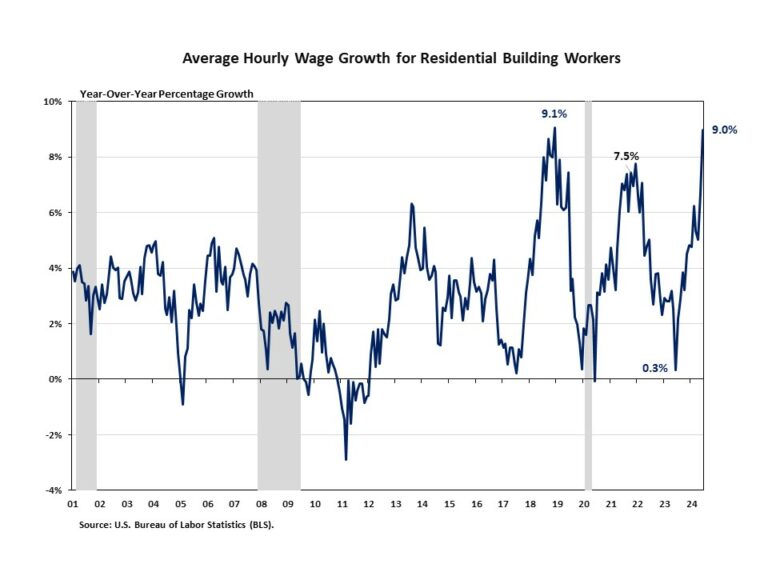

Residential building workers’ wage growth accelerated to 9.0% in June. This marks the fastest year-over-year (YOY) growth rate since December 2018. After a 0.3% increase in June 2023, the YOY growth rate for residential building worker wages have been trending upward over the past year.

The ongoing skilled labor shortage in the construction labor market and lingering inflation impacts account for the recent acceleration in wage growth. However, demand for construction labor is weakening as interest rates remain elevated. As mentioned in the latest JOLTS blog, the number of open construction sector jobs shifted notably lower from 366,000 in May to 295,000 in June. Nonetheless, the ongoing skilled labor shortage continues to challenge the construction sector.

According to the Bureau of Labor Statistics report, average hourly earnings for residential building workers* was $32.28 per hour in June 2024, increasing 9.0% from $29.62 per hour a year ago. This was 16.2% higher than the manufacturing’s average hourly earnings of $27.79 per hour, 10.6% higher than transportation and warehousing ($29.18 per hour), and 11.1% lower than mining and logging ($36.33 per hour).

Note: *Data used in this post relate to production and nonsupervisory workers in the residential building industry. This group accounts for approximately two-thirds of the total employment of the residential building industry.

Discover more from Eye On Housing

Subscribe to get the latest posts sent to your email.


This article was originally published by a eyeonhousing.org . Read the Original article here. .

Pin It